The federal government banned lead-based paint for use in homes in 1978, and the EPA says approximately three-quarters of the homes in the United States built before 1978 still contain some. If you own a pre-1978 home, lead paint may well be part of the picture, whether you can see it or not.
Here's what many sellers don't realize: you can sell a house with lead paint. Federal rules focus on disclosure. They require you to disclose what you know, hand buyers an EPA pamphlet and give them a 10-day window to inspect (which they can waive in writing). They do not require you to remove the paint. They don't even require you to test for it.
The fear that lead paint makes a home unsellable, or that you'll need to pay for expensive abatement before listing, is common but often overstated. That said, the concern isn't baseless. Lead paint can narrow your buyer pool, trigger appraisal problems on government-backed loans and add time to your sale. The question isn't whether you can sell. It's which path gets you the best net result: remediate and list, disclose and sell traditionally, or sell as-is to a cash buyer who prices the lead paint into the offer.
This guide covers the federal disclosure requirements, remediation options and what they involve, how lead paint affects FHA, VA and conventional financing, what cash buyers expect, and a step-by-step framework for deciding which path makes sense for your situation. If your home was built before 1978, and especially if paint is peeling or chipping, you'll want to read this before listing.
What You Need to Know About Lead Paint in Pre-1978 Homes
The federal government banned lead-based paint for use in homes in 1978. Any home built before that year may contain it, and the older the home, the more likely it is. But "has lead paint" and "has a lead paint hazard" are two very different things, and the distinction matters for both your disclosure obligations and your selling strategy.
Intact lead paint in good condition is far less dangerous than paint that's peeling, chipping or flaking. One scenario lets you sell with minimal friction. The other can derail financing, drive up remediation costs, and eliminate a significant portion of your buyer pool.
How Common Is Lead Paint (and Where Is It?)
The EPA's figures depend on the age of the home. It reports that before 1940, 87% of homes are likely to have lead-based paint. Between 1940 and 1959 it is 69%, and between 1960 and 1977 it is 24% (see the EPA's page on sources of lead). The older the home, the higher the share.
Where does it show up? The EPA points to surfaces that see constant friction, such as doors and window sills, where old or worn paint can produce chips and dust. Lead paint can also be hiding under newer layers. The EPA warns that renovation or repair work that disturbs painted surfaces in older homes may create large amounts of lead dust, even when the visible paint looks fine.
Intact Paint vs. Deteriorating Paint: Why the Condition Matters More Than the Presence
This is the distinction most sellers miss, and the one that changes everything about your selling strategy.
Intact lead paint (smooth surfaces, no peeling, chipping or flaking) is, in the EPA's words, usually not a problem. Known lead paint must still be disclosed in a sale, and abatement before closing is not required by the federal disclosure rule. FHA's rules direct the appraiser to look for defective paint, so intact paint is less likely to be flagged. If your pre-1978 home has intact painted surfaces, you can often sell traditionally with standard disclosure and little buyer pushback.
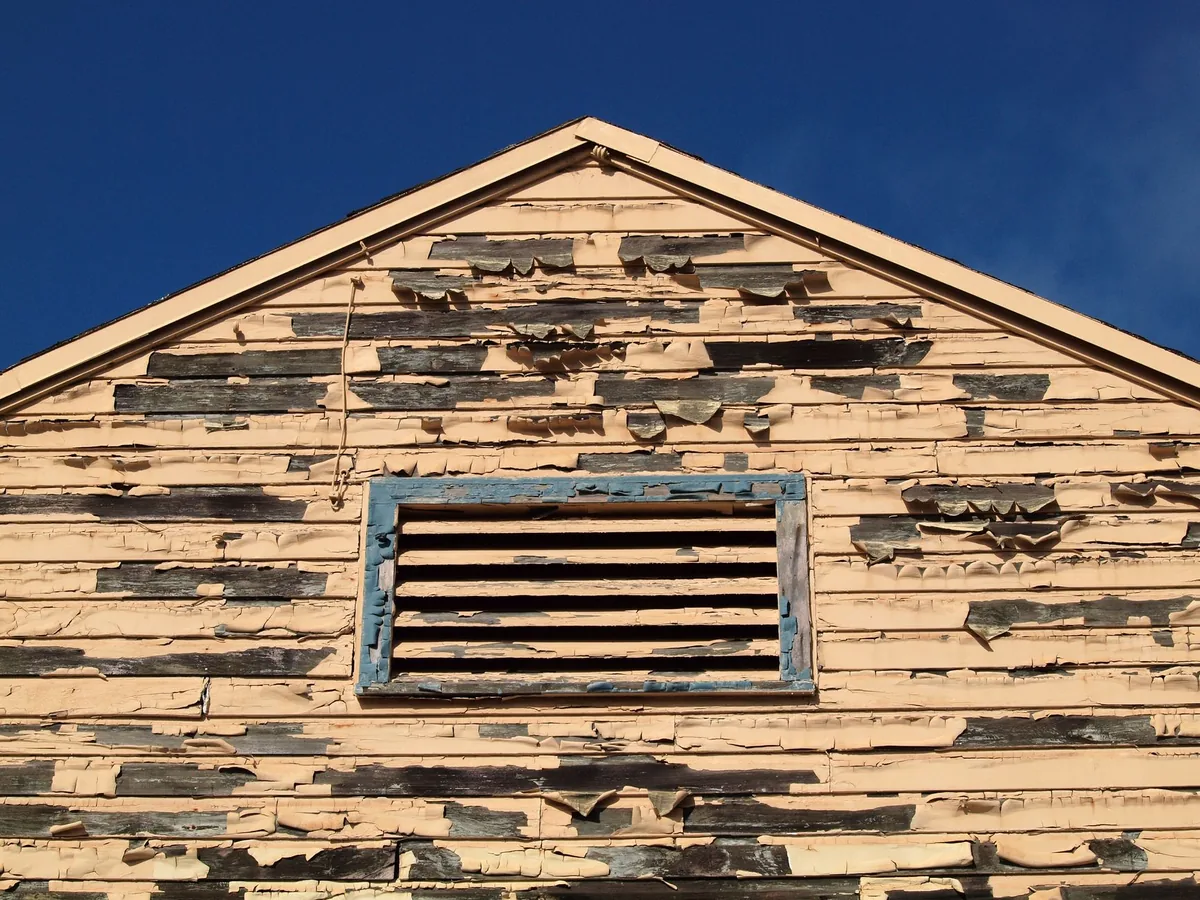
Deteriorating lead paint (peeling, chipping, cracking or worn surfaces) is a different story. The EPA says old or worn lead paint can produce chips and dust that become a hazard when inhaled or swallowed. This is what can trigger appraisal problems on FHA loans and create post-sale liability, and it is what can drive remediation costs up.
Your first step as a seller is figuring out which category your home falls into. That assessment shapes every decision that follows.
| Condition | Description | Health Risk | FHA Impact | Selling Impact |
|---|---|---|---|---|
| Intact, good condition | No peeling, chipping or flaking; surface smooth | Lower, unless disturbed by renovation | Less likely to be flagged | Disclose and sell normally; minor buyer concern |
| Minor deterioration | Small areas of peeling on non-friction surfaces | Moderate (localized dust) | May be flagged; repair may be required | Targeted repair or a credit |
| Significant deterioration | Widespread peeling or chipping, including friction surfaces like windows and doors | High (active dust generation) | Likely flagged; repair is typically required | Encapsulate, remove or sell as-is |
| Severe or widespread hazard | Crumbling paint, visible dust, large areas compromised | Very high | Likely flagged; repair is typically required | Full abatement or sell as-is to a cash buyer |
Federal Lead Paint Disclosure: What Sellers Must Do (and What They Don't)
Federal law (Section 1018 of Title X, and the EPA and HUD rules that implement it) requires sellers of pre-1978 homes to disclose known lead paint information, provide an EPA pamphlet, and give buyers a 10-day inspection window. The rule says it does not put a positive obligation on the seller to conduct any evaluation or reduction activities. In plain terms, you do not have to test for lead paint, and you do not have to remove it. But you must tell buyers what you know.
The federal rule applies to all transactions to sell target housing, so it covers listings with an agent, sales by owner and as-is sales to a cash buyer. The exceptions are narrow and specific, listed below.
The Five Federal Disclosure Requirements
These come from the EPA's lead-based paint disclosure rule and apply to sales of pre-1978 homes unless an exemption applies.
- Disclose known lead paint information. Share any knowledge you have about the presence of lead-based paint and lead-based paint hazards in the property, including the location and condition of painted surfaces.
- Provide available records and reports. Hand over any existing inspection reports, risk assessments, or previous abatement records related to lead paint in the property.
- Give the buyer the EPA pamphlet. Every buyer must receive a copy of "Protect Your Family From Lead In Your Home," the EPA's official consumer guide.
- Include a Lead Warning Statement with the contract. The federal rule requires a specific Lead Warning Statement, included in or attached to the contract, along with signatures and dates from the sellers, agents and purchasers.
- Offer a 10-day testing window. Give the buyer a period (10 days is the default, though it can be extended, shortened, or waived by mutual written agreement) to conduct a lead paint inspection or risk assessment.
After closing, keep signed copies of all disclosure documents for at least three years.
What You Don't Have to Do
You don't have to test for lead paint. The disclosure form lets a seller state that they have no knowledge of lead-based paint or hazards, and that statement has to be true to the best of your knowledge.
You don't have to remove lead paint. Disclosure is not the same as remediation. The law requires transparency, not action.
The 10-day window is the buyer's chance to inspect. The rule does not ask you to do the testing yourself.
And "as-is" sales still require lead paint disclosure. This is federal law. It applies regardless of the sale terms, the condition of the property, or whether the buyer is an individual, an investor, or a cash home buying company. Sellers who skip disclosure on cash sales face the same potential penalties as anyone else.
When Disclosure Doesn't Apply
A small number of situations are exempt from federal lead paint disclosure requirements:
- Homes built after 1977 (no pre-1978 paint present)
- Foreclosure sales
- Zero-bedroom units (studio-type housing where the living and sleeping areas are not separated) unless a child under 6 resides or is expected to reside there
- Leases of 100 days or less
- Housing for the elderly or persons with disabilities (unless a child under 6 resides or is expected to reside there)
- Housing certified as lead-free
If none of these applies to your sale, you're required to disclose.
Penalties for Non-Compliance
The EPA says a seller, landlord, real estate agent or property manager who does not give the proper information to homebuyers and renters may be subject to penalties. The federal rule says violators may face civil and criminal sanctions, and the statute makes a person who knowingly violates it liable to the buyer for three times the damages the buyer incurs. Penalty amounts are adjusted over time, so check the EPA's page or ask an attorney for current figures. Disclosure itself is straightforward, and skipping it carries real risk.
Lead Paint Remediation Options: Costs, Timelines, and What Each Method Involves
If your home has deteriorating lead paint and you're considering remediation before selling, you generally have a few options: encapsulation (sealing the paint in place), enclosure, chemical removal and full abatement, plus component replacement, which makes sense when a window or door needs replacing anyway. Costs vary widely with the size of the area, the method and your region, so get written quotes from certified contractors. The EPA says lead abatement must be done by trained and certified abatement contractors. Whether you need full abatement depends on the condition of the paint and on what a buyer's lender requires.
Remediation Methods Compared
| Method | What It Is |
|---|---|
| Encapsulation | Apply a special coating over lead paint to seal it in place |
| Enclosure | Cover lead-painted surfaces with new drywall, paneling or cladding |
| Chemical removal | Apply a chemical stripper to soften and scrape paint |
| Full removal | Strip the lead paint from the surface using approved methods |
| Component replacement | Remove and replace whole components such as windows, doors or trim |
The EPA RRP Rule: Why Your Contractor Matters
This is the part most selling guides skip, and it can catch sellers off guard.
The EPA's Renovation, Repair, and Painting (RRP) Rule says that firms performing renovation, repair and painting projects that disturb lead-based paint in homes built before 1978 must be EPA- or state-certified and must use certified renovators. This isn't limited to lead abatement specialists. If you hire a contractor to sand, scrape or cut into painted surfaces in a pre-1978 home for any reason, including pre-sale repairs unrelated to lead, that firm generally needs to be certified. The rule has exceptions, so check the EPA's page or ask the contractor.
The practical impact for sellers: fewer contractors may be able to do the work, which can affect both cost and wait times. Covered work done by an uncertified firm can put the project out of compliance with the rule.
Before hiring anyone for pre-sale work on a pre-1978 home, ask to see the firm's EPA or state lead-safe certification.
Hidden Costs and the "Clustered Hazard" Problem
Lead paint is sometimes not the only issue in an older home. Homes from the same era can also have aging systems and materials that are expensive to address one by one and overwhelming all together.
Other issues that can show up in older homes include:
- Asbestos: testing and abatement can be significant, depending on scope
- Knob-and-tube or outdated wiring: replacement is often a major expense
- Outdated plumbing: replacement can be a major expense
- Old windows: replacement adds up quickly across a whole house
- Thin or missing insulation
When you add lead paint remediation on top of electrical, plumbing, asbestos and window issues, the total bill can climb quickly. At that point, the remediate-then-list math can break down. The cost of fixing everything may exceed the additional sale price those fixes generate, especially in markets where older homes already trade at a discount.
Cash buyers and investors often buy properties with several issues at once. They price the full scope into their offer rather than requiring you to resolve each problem individually. If your home is dealing with more than just lead paint, that's worth factoring into your decision. For a look at how selling an outdated house works with cash buyers, we covered that in a separate guide.
How Lead Paint Affects Your Buyer Pool: FHA, VA, and Conventional Loans
If your pre-1978 home has peeling, chipping or flaking paint, a buyer using an FHA loan may not be able to close until the affected surfaces are repaired. FHA's standards are in HUD Handbook 4000.1, which directs the appraiser to note the condition and location of defective paint on homes built before 1979 and to require repair in line with HUD's lead-based paint rule and any applicable EPA requirements. Depending on your market, that can shrink your potential buyer pool.
| Loan Type | What the Appraiser Checks | What Can Trigger a Problem | What May Need to Happen Before Closing |
|---|---|---|---|
| FHA | Interior and exterior painted surfaces of homes built before 1979 | Cracking, scaling, chipping, peeling or loose paint | Repair of the defective paint, following HUD's lead-based paint rule and any applicable EPA requirements |
| VA and USDA | Each program has its own property standards | Ask the buyer's lender | Ask the buyer's lender |
| Conventional | The appraiser notes condition and the lender decides | Condition or safety concerns the lender cares about | Varies by lender. Ask the buyer's lender |
The nuance that trips up many sellers: for FHA loans, the appraiser's job is a visual observation of the surfaces, and defective paint on a pre-1979 home gets noted and repaired under the rules above. Ask the buyer's lender how it handles paint that has not been tested.
Stabilization means repairing the defective paint with lead-safe work practices, and it can delay closing. The EPA's RRP rule may require a certified firm for the work. Ask the buyer's lender what it requires.
One thing a price reduction does not do: make the paint repair go away. When a lender requires the repair, offering a lower price doesn't fix the appraisal flag. Ask the buyer's lender whether a credit is ever an option.
Cash buyers skip the lender's rules. There's no lender appraisal, no lender-required paint repair, and no financing contingency. For sellers whose pre-1978 homes have deteriorating paint and a tight timeline, this is often where the cash offer vs. listing comparison gets interesting.
What Cash Buyers Actually Expect When You Have Lead Paint
Cash buyers expect you to follow the same federal disclosure requirements as any other sale: the EPA pamphlet, the Lead Warning Statement and the 10-day testing window. They do not expect you to test for lead paint, remove it, encapsulate it or remediate it. They price the lead paint, and whatever it will cost to address after purchase, into the offer. The trade-off is a lower sale price in exchange for no remediation cost, no repair delays and more certainty of closing. Whether Eagle can make an offer depends on the property, the title and our buying criteria.
Disclosure is still required. This bears repeating because it's the most common misconception about cash and as-is sales. Federal lead paint disclosure applies to sales of pre-1978 homes, including cash sales and investor sales, unless one of the narrow exemptions listed above applies. Sellers who skip disclosure on a cash sale face the same potential penalties and buyer lawsuits.
The 10-day testing window still applies unless the buyer waives it. Some cash buyers and investors choose to waive it because they already plan to address the paint after purchase, but the waiver should be in writing.
How cash buyers factor lead paint into their offer. They estimate what it will cost to address the paint after purchase, subtract that from their offer along with other repair costs, holding costs and their margin, and make an offer based on the property's current condition. A cash offer is below what a fully remediated house might fetch on the open market. For a detailed breakdown of the calculation, see our guide on how cash buyers calculate offers.
What cash buyers typically don't need: to meet an FHA or other lender's appraisal standards, or a buyer financing contingency. They evaluate the property as-is.
What cash buyers do care about: Honest disclosure, a clean title, and a property they can evaluate accurately. Surprises after the contract is signed, like significant undisclosed hazards behind peeling paint, erode trust and can derail deals even with experienced cash buyers. The title insurance process still applies, and transparency makes everything move faster.
If you're unsure whether a cash buyer is operating legitimately, we wrote a guide on evaluating cash home buyers that covers what to look for and what to watch out for.
The Math: Remediate-Then-List vs. Sell As-Is
Whether remediating before listing makes financial sense depends on three things: the scope of the lead paint issue, the total cost of remediation plus any other needed repairs, and how long you can afford to wait. For minor surface stabilization, the math can favor fixing and listing. For full abatement, especially when other systems also need work, selling as-is can net a comparable amount once all costs are counted. A listing can net more when you have both the time and the money to put the house right.
Fill in the same lines for each path using your own quotes and estimates.
Net-Proceeds Worksheet for a Pre-1978 Home With Lead Paint
| Line Item | Stabilize or Encapsulate, Then List | Full Abatement, Then List | Sell As-Is to a Cash Buyer |
|---|---|---|---|
| Sale price | Close to market value for a sound house | Close to market value, possibly a small premium | Below market, because the buyer takes on the remediation and the risk |
| Remediation cost | Your contractor's written quote | Your contractor's written quote | None on your side |
| Agent commission | Usually applies | Usually applies | None on a direct sale |
| Closing costs | Usually paid by the seller | Usually paid by the seller | Eagle pays them, except your mortgage payoff, back taxes or liens and your share of transfer tax |
| Carrying costs | Mortgage, taxes, insurance and utilities during the work and the listing | The same, over a longer period | Limited to the days until closing |
| Time to close | Work, listing and the buyer's loan process | Longest of the three | As little as 21 to 42 days, or longer if you need it |
The numbers are yours to fill in. The point is that full abatement before listing can cost more than the value it adds, while minor stabilization may pay for itself.
The key insight from this comparison: minor stabilization may be worth it if you can afford it and you have the time. It can keep FHA buyers eligible. Full abatement, on the other hand, may not pay back dollar for dollar on your house.
Factor in the time value, too. Every month the house sits during remediation and the traditional selling process, you're paying the mortgage, property taxes, insurance and utilities. Those carrying costs add up.
A Decision Framework: Should You Remediate, Encapsulate, or Sell As-Is?
The right path depends on four variables: the condition of the paint, your budget for remediation, your timeline, and whether the home has other issues beyond lead paint. Here's a step-by-step framework for working through the decision.
Step 1: Assess the paint condition. Is the paint intact with no peeling, chipping, or flaking? If so, you can likely sell traditionally with standard disclosure alone. No remediation required. If the paint is deteriorating, continue to Step 2.
Step 2: Determine the scope. Consider a professional lead inspection or a risk assessment, which the EPA says only certified inspectors and risk assessors can legally perform. An inspection determines whether there is lead-based paint and where it is located. A risk assessment looks for lead hazards, including hazards in paint, dust and soil. Small areas of deterioration (a few windows, one room) suggest targeted stabilization. Widespread deterioration points toward encapsulation or removal. Get written quotes for each.
Step 3: Check your budget. Can you afford the remediation out of pocket? If so, remediation and a traditional listing may be the right path. If you can't cover the upfront cost, selling as-is or negotiating a buyer credit at closing may make more sense. The catch with buyer credits: they may not satisfy a lender's repair requirement, so ask the buyer's lender before you count on one.
Step 4: Check your timeline. Can you wait for remediation plus a traditional sale? If so, the remediate path is viable. Need to close quickly? An as-is sale to a cash buyer may be the faster route, with closing in as little as 21 to 42 days, or longer if you need it.
Step 5: Check for compounding issues. Is lead paint the only problem? If so, remediation is probably worth it if you can afford it and the timeline works. Does the home also need electrical rewiring, plumbing updates, asbestos removal or structural work? If the total bill across all systems is large, the math may favor selling as-is. Run the net-proceeds comparison using your actual numbers.
Step 6: Compare net proceeds. Use the worksheet from the previous section. Plug in your home's estimated sale price, your actual remediation quotes, your carrying costs per month and your expected timeline. The highest net to you wins. If the numbers are close between paths, factor in your timeline, stress tolerance and how much closing certainty matters to you.
Liability After the Sale: Can You Be Sued for Lead Paint?
Following the federal disclosure requirements is the baseline. If you don't, or if you actively conceal known lead paint hazards, you can face penalties and be sued after closing. An attorney can tell you how your state treats claims after a sale.
Honest disclosure is your best legal protection. If you disclose what you know (or honestly state that you don't know), you have done what the federal rule asks.
"I didn't know" is a valid position, but only if it's true. Sellers aren't required to test for lead paint, and "unknown" is an acceptable disclosure answer. But if you had a lead inspection done and didn't share the results, or if you painted over deteriorating lead paint specifically to hide it before listing, that can be treated as concealment and lead to legal claims.
State laws may add requirements beyond federal law. Some states and cities have their own lead rules that go beyond the federal baseline. Consult a real estate attorney in your state for specific obligations, especially if you know the property has lead paint.
Don't assume your insurance covers lead paint claims. If you're selling a property you know has lead paint, ask your insurance agent whether your policy covers lead-related claims before closing.
The practical takeaway: Complete the federal disclosure honestly, keep a signed copy for three years after the sale, and consult a real estate attorney if you know lead paint is present and you're unsure about your state's requirements. Disclosure is straightforward. The cost of skipping it can be significant.
Frequently Asked Questions
Can you sell a house with lead paint?
Yes. Federal rules require sellers of pre-1978 homes to disclose known lead paint information, provide an EPA pamphlet and offer a 10-day buyer inspection period. They do not require you to test for lead paint or remove it before selling. Homes with lead paint can be sold through traditional listings, by owner and in cash sales.
Do I have to disclose lead paint when selling my house?
Yes, if your home was built before 1978. Federal law (Section 1018 of Title X) requires sellers to disclose any known information about lead-based paint and lead-based paint hazards. This applies to as-is and cash sales as well. The exemptions are narrow: housing built after 1977, foreclosure sales, certified lead-free housing, zero-bedroom units, short-term leases, and certain elderly or disabled housing, as described in the EPA's disclosure rule.
How much does lead paint reduce home value?
It depends largely on the condition of the paint. Intact lead paint with proper disclosure may have little effect on your sale price. Deteriorating lead paint that requires remediation can lower what buyers will pay, since they weigh the cost of the work and the uncertainty. The impact on your buyer pool can matter too: deteriorating paint on a pre-1978 home can hold up FHA buyers, narrowing demand and potentially lowering offers.
Do cash buyers care about lead paint?
Cash buyers expect full federal disclosure, but they generally do not require remediation before closing. They factor estimated lead paint remediation costs into their offer and plan to handle it after purchase. There's no lender appraisal to fail and no financing contingency. The trade-off is typically a lower sale price in exchange for speed, certainty, and zero out-of-pocket remediation cost for the seller.
What happens if an FHA appraisal finds peeling paint on a pre-1978 home?
HUD's handbook directs the appraiser to note defective paint on a home built before 1979 and to require repair in line with HUD's lead-based paint rule and any applicable EPA requirements. In practice, that means the paint repair generally has to be dealt with before the loan can close, and a price reduction alone does not make it go away. If the work falls under the RRP rule, a certified firm may be needed, which can affect cost and timing. Ask the buyer's lender what it requires.
Is encapsulation or removal better for selling a house with lead paint?
Encapsulation seals the paint in place rather than eliminating it, and removal takes the paint away. Which one fits depends on the condition of the paint, the cost and what a buyer's lender requires. Get written quotes from certified contractors before you decide.
Do I have to test for lead paint before selling?
No. Federal law does not require sellers to test for lead paint. You're only required to disclose what you already know. If you have no knowledge of lead paint, the disclosure form lets you say so, as long as it is true. However, if you have had a lead inspection or other testing done, you must provide the records and reports you have, even if the results are unfavorable.
What are the penalties for not disclosing lead paint?
The EPA says sellers who do not give the proper information to homebuyers may be subject to penalties. The federal rule says civil and criminal sanctions are possible, and the statute makes a person who knowingly violates it liable to the buyer for three times the damages. The disclosure itself is straightforward.