Homeowners who fall behind on the mortgage eventually face a hard question: pursue a short sale, or let foreclosure happen? Short sale vs foreclosure is not a small choice. It can affect your credit, your ability to buy again, your taxes and how much control you keep over the next few months, and a wrong move is hard to undo.
This guide compares the two side by side. It also covers the deficiency and tax questions people overlook, and why timing matters more than most owners realize. Short version: act early. It is general information, not legal advice. Foreclosure and deficiency rules vary by state, so confirm your situation with your servicer and a local attorney.
What Is a Short Sale?
A short sale is a sale for less than the remaining mortgage balance, with the lender's approval. The lender agrees to take less than it is owed. Unlike foreclosure, you stay involved in the sale process. You usually:
- List the property or find a buyer
- Work with the buyer
- Negotiate with the lender
- Coordinate the closing
The lender must approve the deal before it closes. No approval, no sale. That usually takes paperwork, such as financial documents and a hardship explanation, and the review can drag on while payments, late fees and the foreclosure clock keep running in the background. Patience matters.
Short sales happen when the home is worth less than the loan. Here is a hypothetical example with round numbers. You owe $340,000 and the home sells for $300,000. The $40,000 gap is the shortfall. The lender may accept the sale. Whether it forgives the rest or still pursues it depends on the agreement and your state's law.
How Does Foreclosure Work?
Foreclosure is the lender's legal process for recovering the loan from the property after payments stop. According to the CFPB, it is done in one of two ways, through a court case (judicial) or without one (non-judicial), and the process differs by state.
Under federal servicing rules, a servicer generally cannot make the first foreclosure notice or filing until the loan is more than 120 days delinquent (12 CFR 1024.41(f)). After that, the timing depends on state law. Nothing here is a promise of how long yours will take.
The length of the process varies a lot. Our guide on how long the foreclosure process takes explains the stages, and how foreclosure auctions work explains the sale itself.
The Biggest Differences Between Short Sales and Foreclosures
Both involve financial hardship. The long-term outcomes can be very different, and the differences show up in your credit file, your tax return and the date you can qualify for a new mortgage.
Control Over the Process
A short sale gives you some control. Not total control. You can usually choose when to sell, talk with buyers and plan your move, although the lender still has to approve the price and may counter, delay or say no at any point along the way. In a foreclosure, the lender and the court calendar drive the timeline. You have far less say.
Credit Impact
Both hurt your credit. The size of the drop depends on your starting score and history, and no one can promise you a number in advance. Credit reporting companies can generally report negative payment history for up to seven years. Fannie Mae treats a foreclosure as the more serious event, and that shows up in the waiting periods below.
Future Mortgage Eligibility
| Event | Standard Fannie Mae waiting period | With documented extenuating circumstances |
|---|---|---|
| Short (preforeclosure) sale | 4 years | 2 years |
| Foreclosure | 7 years | 3 years |
These are Fannie Mae's published waiting periods for conventional loans, counted from the completion date (Selling Guide B3-5.3-07). FHA, VA and USDA loans, and individual lenders, may use different rules, so ask a loan officer about your own situation. Do it early.
Why Many Homeowners Choose a Short Sale
Nobody wants a short sale. Still, it often leaves less long-term damage than a foreclosure. It avoids a foreclosure on your record, can shorten the wait for a new mortgage, and lets you manage the timing instead of waiting for a court date that someone else sets. It only works if the lender agrees. That takes patience.
Deficiency Balances and Taxes
A deficiency is the gap between what you owe and what the property brings in. In some states the lender can pursue that gap after a short sale, and state rules differ. The CFPB advises that if the lender waives the deficiency, you get the waiver in writing. An attorney can tell you what your state allows.
Forgiven debt can also count as income. Plan for that. The IRS generally treats canceled debt as taxable unless an exclusion applies. One exclusion covers forgiven debt on a primary residence, but it applies only to debt discharged before January 1, 2026, or under a written arrangement made before then. See the IRS page on canceled debt, and ask a tax professional about your situation.
Can a Short Sale Prevent Foreclosure?
It can, but only if the lender approves the sale and it closes in time. A short sale does not automatically stop a foreclosure that has already started, so ask the servicer whether it will postpone the sale date while the offer is reviewed. Timing is critical. The most common mistake is waiting too long to contact the mortgage lender, sometimes because the whole situation feels too overwhelming to face. Once the foreclosure process is well underway, options shrink fast.
Where a Cash Sale Fits In
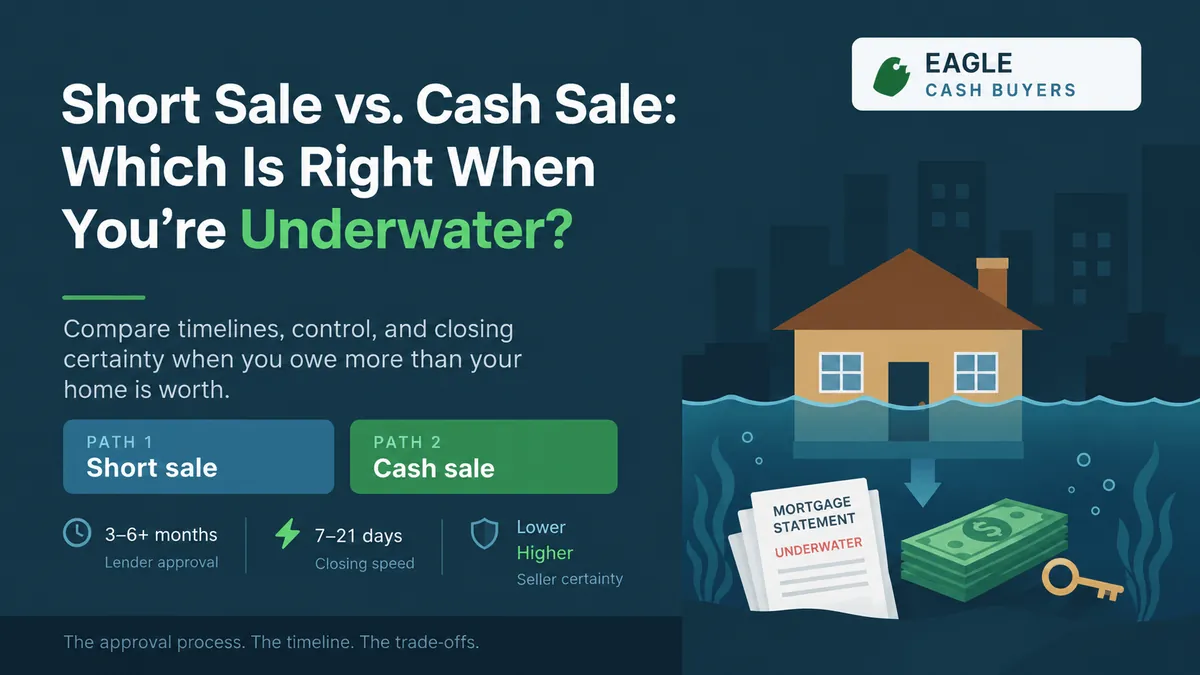
If you have equity, the choice may not be short sale vs foreclosure at all. A regular sale that pays off the loan avoids both. Run the numbers first. If you owe more than the house is worth, the lender still has to approve any sale for less than the payoff. A cash buyer cannot promise that approval. Be wary of anyone who says otherwise. Our guide on short sale vs cash sale explains the difference.
Some homeowners need speed more than the highest price. A listing can net more when you have both the time and the money to get the house ready, while a cash sale can be faster, though the cash price is generally below market value and every buyer sets its own terms. With Eagle Cash Buyers, closings can happen in as little as 21 to 42 days, or later if you need more time, but whether we can make an offer depends on the property, the title and our buying criteria.
Final Words
Short sales and foreclosures both signal financial distress, but they are not equal outcomes. A short sale often gives more control and shorter waiting periods, if the lender agrees. A foreclosure usually carries deeper long-term consequences. The earlier you act, the more options you keep. Waiting closes doors. See mortgage default consequences for the full picture, and how to delay foreclosure if time is short.