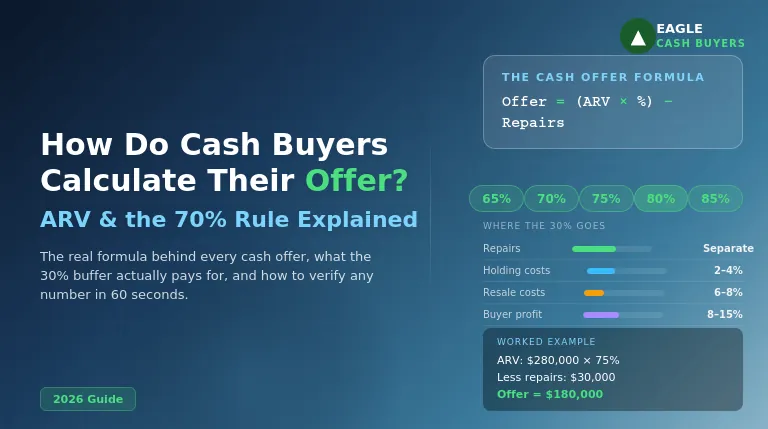
How do cash home buyers calculate their offer? Many work backward. They estimate what your house would sell for after it's fixed up, called the after-repair value or ARV, and then subtract what it takes to get there: repairs, the costs of buying and reselling, and a margin for their risk and work. What's left is the offer.
That number isn't random. You don't have to take it on faith, either. Once you know the pieces, you can ask any buyer to show theirs, and this guide explains the formula, the "70% rule" investors quote, what the discount actually pays for, and how to check an offer for yourself. We buy houses ourselves, so weigh our view accordingly.
One caution first. Every figure in the examples below is illustrative, because no formula applies to every buyer and every house.
The Formula Behind Every Cash Offer
Cash buyers use two versions of the same idea. The shortcut applies a percentage to the ARV and then subtracts repairs. The itemized version subtracts each cost one by one, which takes longer but shows you exactly where the money goes. Both start in the same place.
ARV (after-repair value): what the house would sell for on the open market if it were fully updated and move-in ready. It isn't your online estimate, and it isn't what you paid. It's based on what comparable, renovated homes near you actually sold for in recent months, adjusted for the differences between those homes and yours.
Repair costs: what it would take to bring the house up to that condition. Roof, systems, kitchen, bathrooms, flooring, paint. Anything structural.
Everything else the buyer pays or risks: closing costs on the purchase and on the resale, holding costs while the work is done, a cushion for surprises, and a profit. Without profit, there is no buyer.
From Our Transactions: Showing the Math on a Live Call
In one Eagle seller file, a woman called on behalf of her husband, with power of attorney, about a house he had inherited. It was a small home of roughly 894 square feet. She wasn't browsing. She was shopping around: "I'm just calling around to all the different places that can give me fast cash offers and see who's the highest bidder at this point." She already had a $50,000 offer from another company.
The Eagle acquisition manager didn't just name a number. He showed his work on the phone. He started from market value, around $114,000 on the comparable data, though she had the house at $120,000 on Zillow, and he explained each step as he went. He subtracted renovation, estimated at about $35,000 to $40,000 from roughly $30 to $35 per square foot. He subtracted roughly 15% for closing costs and commissions when the company would eventually resell. Then he subtracted a margin. The offer was $55,000, which was above the $50,000 she already held, and he said why it landed where it did instead of asking her to trust him.
She pushed back. She was entitled to: "Oh, no, sir. If you're going to come at me like that, then I may as well just hang up the phone." She had followed her local market for six years. She believed the lot alone was worth far more, and she had a friend who's a local real estate agent lined up to check the math before she said yes to anyone.
That is exactly what a seller should do. Nobody has to accept a first number. The point is that the steps were laid out in the open, so she could test each one. These figures belong to one property in one market. Don't treat them as a formula for yours.
What Is the 70% Rule, and When Does It Apply?
The "70% rule" is a rule of thumb many house flippers quote. It says not to pay more than 70% of the ARV, minus repair costs. It's a quick screen. It isn't a law, and plenty of buyers use a different percentage or skip it entirely in favor of an itemized estimate.
MAO = (ARV x 0.70) − Repair Costs
MAO stands for maximum allowable offer. Here is a hypothetical example. Say the ARV is $300,000 and repairs are $45,000. Then MAO = ($300,000 x 0.70) − $45,000 = $165,000.
Where the 70% Rule Helps
It's useful for a house that needs heavy work in an ordinary market. A buyer can run it in seconds. It builds in room for cost overruns, holding costs and a slow resale, which makes it a handy first filter on a deal that might deserve a closer look.
Where It Breaks Down
It is sometimes presented as universal. It isn't. A fixed percentage treats a $120,000 house and a $600,000 house as if their costs scaled the same way. They don't. Some fixed costs, like closing costs and a minimum profit, matter more on a low-priced house. A move-in-ready house carries less renovation risk than a gutted one, so buyers may adjust the percentage for those reasons. Some skip it for the itemized method.
So treat the 70% rule as a benchmark, nothing more. The better question for a seller is whether the buyer can explain how they reached their number, line by line, in plain language.
What the Discount Actually Pays For
Sellers sometimes hear "30% below market" and assume it's all profit. Not so. The gap between ARV and the offer has to cover several costs, and the buyer's margin is only one of them. Here is the same hypothetical $300,000 ARV, itemized with round numbers that are only meant to illustrate.
| Illustrative line item | Hypothetical amount |
|---|---|
| After-repair value (ARV) | $300,000 |
| Repairs | -$45,000 |
| Resale costs (agent commission and closing costs when the buyer sells) | -$24,000 |
| Buyer's closing costs and holding costs (taxes, insurance, utilities) | -$9,000 |
| Cushion for surprises | -$10,000 |
| Buyer's margin for the work and the risk | -$47,000 |
| Offer | $165,000 |
These amounts were chosen so the total matches the 70% rule example above. Real deals differ. Some buyers need a larger cushion, some resell faster, and some renovate more cheaply. What matters is that most of the gap is real cost the buyer takes on, so an offer can look low without being unfair. It's still below what a fully repaired, listed house might bring. You aren't paying for the repairs or the wait.
Not Every Cash Buyer Uses the Same Math
Different cash buyers run different businesses, so the same house can produce very different offers. Knowing the buyer type explains much of the price.
Fix-and-Flip Investors
They lean hardest on the ARV approach. They need room for renovation, a resale and a profit, and they work to a timeline, so every month of delay costs them money.
Buy-and-Hold Investors
Landlords care less about resale. They look at the rent a house could earn compared with the price they pay, and at what it costs to keep it occupied. A house that makes a poor flip can make a good rental, so a landlord may value the same property differently than a flipper does.
iBuyers
iBuyers are companies that price offers with software. Economists who studied them found that their business works best on homes that are easy to value (see this National Bureau of Economic Research working paper), so a house with major problems may not fit an iBuyer's model. Our guide on cash buyers vs iBuyers compares the two.
Companies That Buy at Scale
Some companies, including Eagle Cash Buyers, may buy directly or assign the contract to another buyer, and the agreement discloses which before you sign. Either way, ask how the number was built.
This is why two or three offers help. The seller above had the right idea. Our guide on where to get a cash offer and how to compare shows what to line up side by side.
How Cash Buyers Figure Out Your ARV (and How You Can Check It)
Buyers estimate ARV from comparable sales, or "comps". These are recently sold homes near yours with a similar size, age and layout, in updated condition, and buyers then adjust for differences such as lot size, an extra bathroom, a garage or a pool. You can run a rough version yourself.
- Find sold homes, not listings. Look at recent sales near your address, using your county's sales records or the "sold" filter on a home-search site.
- Pick three to five close matches. Look for similar size and layout, in updated condition, in the same neighborhood. Note what each one sold for.
- Compare with the buyer's ARV. If their figure is far from what the comps suggest, ask which comps they used.
Common ARV Mistakes Sellers Make
- Using asking prices. What sellers hope to get and what buyers paid are often different numbers, and only the second one counts.
- Comparing with homes in different condition. A renovated house across the street shows your ARV, not your house's value today. That gap is the repair estimate.
- Ignoring location. A house on a busy road or beside a commercial lot may sell for less than an otherwise identical one on a quiet street two blocks away.
How Cash Buyers Estimate Repair Costs
The repair estimate is one of the biggest drivers of the offer. It's also a common place for buyers and sellers to disagree. During a walkthrough or a review of photos, a buyer looks at the roof, heating and cooling, foundation, electrical, plumbing, kitchen, bathrooms, flooring, paint and the exterior. If you're selling an outdated house, it helps to know what a buyer is pricing in.
Why the Buyer's Number Is Often Higher Than Yours
Buyers price repairs at contractor rates, not do-it-yourself costs. Many add a cushion for surprises, which can turn up in older houses, and they may include permits and inspections for structural or system work that a seller doing a quick cosmetic refresh would never think to budget for. A seller who thinks the kitchen just needs paint may not realize the buyer plans a fuller update to reach the ARV. In the story above, the buyer used roughly $30 to $35 per square foot. The right rate varies widely by market and scope.
How to Sanity-Check the Estimate
Ask for a line-item breakdown. A buyer should be able to say what they plan to spend on the roof, the kitchen, the flooring and the systems, and why. Vague answers deserve follow-up questions. A local general contractor can give you a rough quote to compare. The numbers won't match exactly. Scopes and contractors differ. They should still be in the same neighborhood.
What You Actually Net: Cash Offer vs. Traditional Sale
The gap between a cash offer and a listing price looks bigger than it is. What matters is what you keep. A listing can net more when you have both the time and the money to put the house right and wait for a buyer. Even then, you would subtract the agent's commission, your closing costs, repairs, staging and the monthly cost of carrying the house until it sells, and you would carry the risk that a buyer's loan or an inspection undoes the deal weeks after you thought it was done.
A cash offer trades a lower price for speed and certainty. That's the deal. With Eagle, there's no agent commission on a direct sale, and we pay closing costs except your mortgage payoff, back taxes and liens, and your share of transfer tax. Closings can happen in as little as 21 to 42 days, or longer if you need more time. Ask every buyer for a written net sheet, whoever they are. Our comparison of a cash offer vs listing with an agent runs the numbers side by side, and our guide to negotiating with a cash buyer covers what to say once you have an offer.
How to Spot a Lowball vs. a Fair Cash Offer
A fair offer has math behind it. A lowball has pressure. A few questions separate them fast.
- What ARV did you use, and which comps? A serious buyer names them. If not, take note.
- What is the repair breakdown? You want line items, not one lump sum.
- What costs did you build in? Ask about resale costs, holding costs and the margin. Compare them with the table above.
- Can you show proof of funds? Ask for a recent bank statement or a letter from a financial institution, and don't sign until you've seen it.
- Who holds the earnest money? Ask where the deposit will be held, and get the answer in writing in the contract.
- What do other buyers say? Get two or three offers. Different business models give different numbers.
If you're weighing a company's reputation, Eagle is rated A+ by the BBB and has completed more than 1,000 transactions since 2019. You can read reviews from real sellers. Before you commit to anyone, read our guide on how to spot a scam. For the basics of the process, see what a cash offer on a house is.
Frequently Asked Questions
How much do cash home buyers typically offer?
It depends on the house, the housing market and the buyer. Many cash buyers start from the after-repair value and subtract repairs, closing costs, resale and holding costs, and a margin, so the offer lands below market value, but rather than relying on a typical percentage, ask the buyer to show how the number was built.
What is the 70% rule in real estate?
The 70 percent rule is an investor rule of thumb. Pay no more than 70% of the ARV, minus repairs. It's a quick screen used mainly when flipping houses, not an absolute rule, and many buyers adjust the percentage or use an itemized method instead.
What is after-repair value (ARV)?
ARV is what your house would likely sell for after a full renovation, estimated from recent sales of comparable homes nearby. It's the starting point for most cash offers.
Why is a cash offer lower than market value?
The buyer takes on repairs, closing and holding costs, resale costs, the risk of surprises and a profit margin. You skip the repairs, the showings and the wait. Compare what you would net.
How can I check if a cash offer is fair?
Pull your own sold comps. Ask for the buyer's ARV, comps and repair breakdown, then test the result against the 70% rule as a benchmark. Getting two or three offers is the most reliable check.
Does Eagle Cash Buyers pay closing costs?
Eagle pays closing costs except your mortgage payoff, back taxes and liens, and your share of transfer tax. There's no agent commission on a direct sale.
How fast can I close with a cash buyer?
With Eagle, a cash sale can close in as little as 21 to 42 days, or longer if you need more time, and you pick the date. Other buyers differ. Title issues such as liens, probate or deed problems can add time with any buyer.