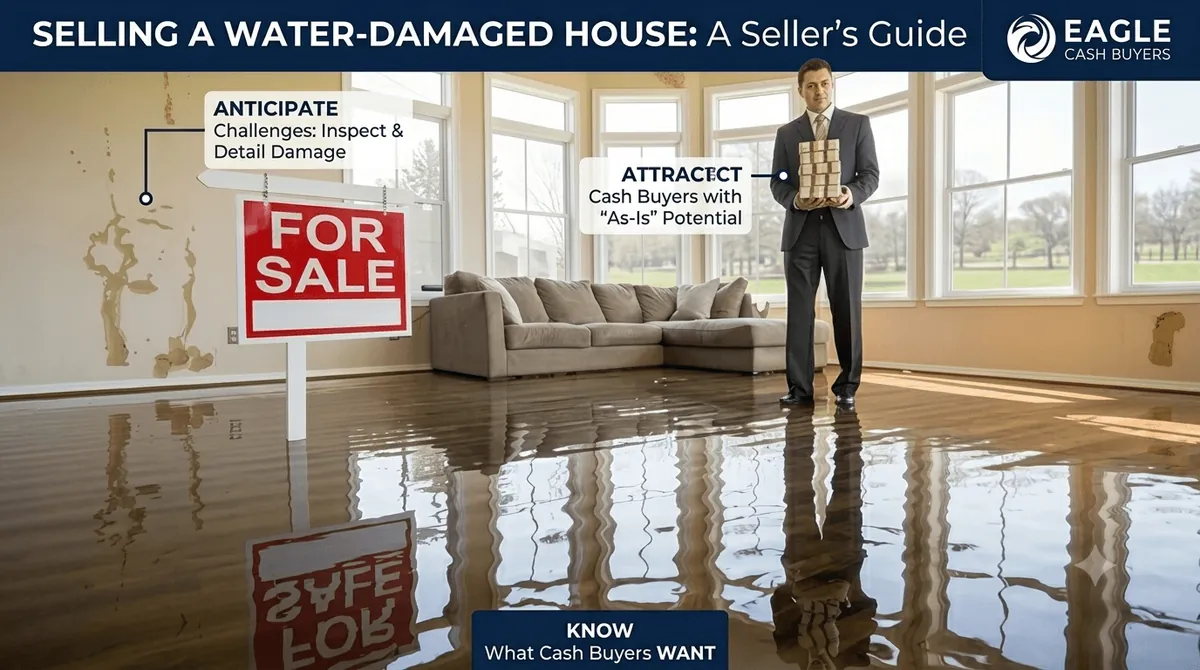
Selling a water-damaged house is possible, and you don't have to repair it first. Cash buyers and investors often buy houses with water damage as they are, and the price reflects the damage. What decides that price is how bad the damage is, whether the water source has been stopped and whether mold or structural problems are involved.
Water damage is one of the scariest problems a seller can face, whether it came from a burst pipe, a flooded basement or a roof that let storm water in, and the first reaction is usually panic. It's understandable. There's a clear way forward. This guide explains how water damage is categorized, how a cash buyer evaluates it, what a traditional buyer's lender will do, and what you have to disclose. We're a cash buyer ourselves. Weigh our view with that in mind.
Do You Have to Repair Water Damage to Sell a House?
No. You can sell as is, with no major repairs first. What changes is the buyer pool and the price, because a buyer who needs a mortgage may not be able to close on a house with active damage, and a buyer with cash will subtract the cost of the work from the offer.
Two things decide whether repairing first makes sense. You need the money to pay for remediation and repairs, and you need the time to wait through the work, a listing and a financed buyer's closing. If you have both, repairing and listing can net more. If either one is missing, selling as is to a cash buyer is often the better outcome, and sometimes the only one that closes. Our guide on selling a house as is explains how that route works.
We evaluate houses in many conditions, including water damage, mold and structural problems, but whether we can make an offer depends on the property, the title and our buying criteria.
How Water Damage Is Categorized
Restoration professionals commonly sort water damage into three categories based on the source, a system built on the IICRC's S500 standard and described in this Connecticut state guidance. Buyers use the same idea to judge risk.
- Category 1, clean water. It comes from a source unlikely to harm people, such as a potable supply line or a sink overflow. It's the least hazardous.
- Category 2, gray water. It carries some contamination that could make people sick, and it can come from something like a dishwasher or washing machine overflow. Left alone, it can turn into black water.
- Category 3, black water. It's grossly contaminated, as with raw sewage or water from rivers and other flooding, and it's the most serious category.
A Category 1 pipe leak in a laundry room looks very different to a buyer than Category 3 water, such as sewage backup or river flooding, that reached the subfloor of the whole house.
Water Damage and the Value of Your Home
Water damage doesn't make a house impossible to sell, but it does set how much a buyer will pay, and a handful of factors move that number up or down before any offer is made. Here they are.
- Whether the source is fixed. A repaired leak is a smaller problem.
- Structural involvement. Damage to subfloors, joists, load-bearing walls or the foundation can cost far more to fix than stained drywall or warped flooring.
- Mold. Visible mold can end a deal with a financed buyer, and even signs of past mold may lower a cash offer.
- Documentation. Invoices, moisture readings and a written timeline reduce the unknowns a buyer has to price in.
Costs vary widely by region and scope, so get written quotes from licensed restoration and repair contractors before you assume a number. A cash buyer's offer generally works backward from the house's value after repairs, minus the work, the resale costs and a margin, which our guide on how cash buyers calculate their offer explains.
On mold, the EPA advises fixing leaks and water problems as soon as possible and drying everything completely. Its guidance says that in most cases you can handle a moldy area smaller than about 10 square feet yourself, while for larger areas it points to its remediation guidance, as described on the EPA's mold cleanup page. Not sure how far it has spread? Get a professional assessment before you sell.
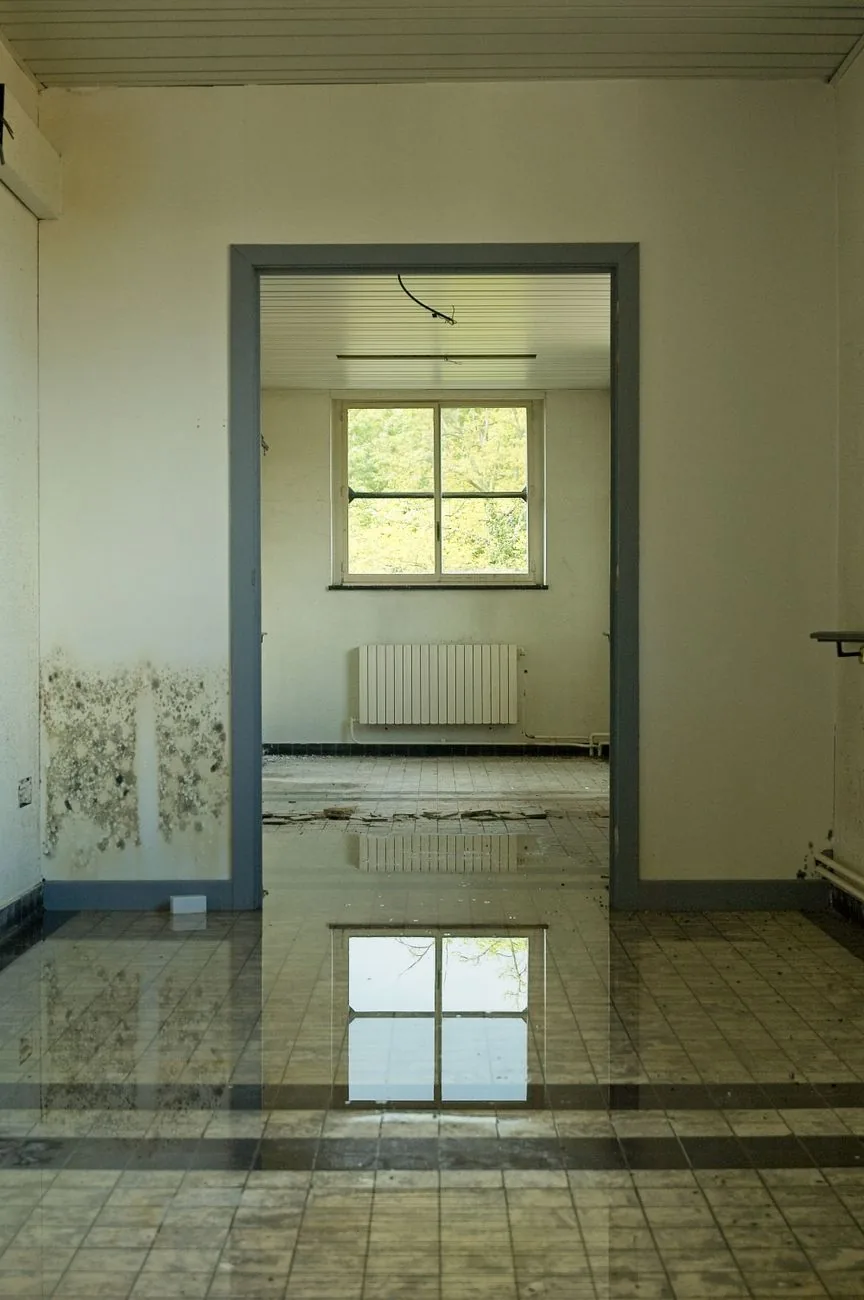
How a Cash Buyer Assesses a Water-Damaged Home
Cash buyers and investors look at houses that traditional buyers pass on, but they evaluate them carefully. Here is what a buyer typically checks.
Whether the Water Source Has Been Stopped
First question: is water still getting in? An active leak is a far bigger concern than past damage, even when the past damage looks serious. A buyer will look at the roof, plumbing, foundation and crawlspace. If you've fixed the source with a pipe repair, a roof patch or drainage work, contractor receipts help, and so does a written note of the date the repair was done and who did it.
The Extent of Structural Damage
Stained drywall and warped laminate are cosmetic, and they're inexpensive to fix compared with compromised framing or a damaged foundation, which can mean opening walls, bracing or replacing structural members and bringing in an engineer before any repair begins. That takes time. If water damage and foundation trouble show up together, our guide on selling a house with foundation problems explains how the two interact.
The Presence of Mold
Mold can kill a financed deal. A cash buyer prices it in. Buyers still want the full picture, though, because a closet with visible mold is very different from mold behind the walls or across a basement. If you have a professional mold assessment, share it.
What Has Already Been Repaired
Repairs can help or raise questions. Documented professional work, such as invoices, moisture readings and drying logs, makes a buyer more comfortable. Undocumented work raises questions about what was done.
The Overall Condition of the House
It rarely comes alone. A buyer also looks at the roof, the HVAC, the wiring and the plumbing, and weighs the whole house against what it would take to bring it to market condition. When we evaluate a damaged property, we send general contractors to quote the repairs, and the seller doesn't pay for that assessment or manage the work.
Why Many Traditional Buyers Can't Buy a Water-Damaged House
A mortgage buyer needs the lender's approval. FHA-insured loans carry HUD's minimum property requirements, which call for a home that is safe, sound and secure, and other loan programs set their own standards. Active water damage, mold or structural problems may keep a home from meeting those standards, and a lender may then refuse to fund until they're fixed.
That narrows the buyer pool to cash buyers, investors and buyers with renovation financing, which is also why water-damaged houses can sit on the market, and why financed deals sometimes fall apart between contract and closing while you keep paying the carrying costs. Standards differ by lender and loan type, so this is a general pattern and not a rule for every buyer.
Your Two Core Choices
Option 1: Repair and List
You pay for remediation, mold removal, structural repair and cosmetic restoration, then list the house, pay agent commissions and wait for a buyer. It can take months. It makes sense when the repair costs are clearly lower than the extra value a repaired, financeable house would bring, and when you have the money and the time.
Option 2: Sell As Is to a Cash Buyer
You sell the house as it is. There are no repairs to pay for, no agent commission on a direct sale and no wait for a buyer's bank. The offer reflects the damage. It's lower than a repaired house might bring. This route fits best when the damage is substantial, speed matters or you can't tie up cash in repairs. Our comparison of a cash offer and listing with an agent shows the two side by side.
How a Cash Sale Works
- Tell us about the property. Share the basics and describe the water damage. See how it works on our how it works page.
- Schedule a walkthrough. A field agent or mobile notary can photograph the property so we can assess the damage category, the structure and the overall condition.
- Review the offer. The offer is based on the condition of the house, and it comes in writing. We pay closing costs except your mortgage payoff, back taxes and liens, and your share of transfer tax.
- Choose your closing date. Closings can happen in as little as 21 to 42 days, or later if you need more time. You pick the date.
- Close and get paid. You close through a title company or closing attorney, and funds go out by wire or cashier's check.
Documents That Can Speed Up Your Sale
You can ask for an offer without any paperwork, but if you have some of the following it can speed up the review and reduce the unknowns a buyer would otherwise build into the price.
- Water damage assessments or remediation reports from a professional
- Contractor invoices for work already done
- Insurance claim paperwork, even if it was only partly paid or denied, since it shows when and how the damage happened
- Written estimates for repairs you haven't done
- Utility records that help date the damage
- A recent home inspection report, if you have one
A simple timeline helps too. Note when the damage happened, what caused it and what you did about it.
What You Have to Disclose
Disclosure rules vary by state. Texas, for example, requires sellers of previously occupied homes to give buyers a written seller's disclosure notice, and its law reaches known flooding and water penetration. Other states differ, so ask a licensed real estate attorney what applies where you live.
Disclosure doesn't stop a sale. The legal risk usually isn't the damage. It's hiding it. Concealing known water damage can expose you to legal claims after the sale, so tell the buyer what you know.
Frequently Asked Questions
Can I sell a water-damaged house as is?
Yes. Cash buyers and investors often buy water-damaged houses as they are, including houses with mold damage or structural problems, subject to the property and the title. You don't have to repair anything first.
How much value does a water-damaged house lose?
It depends on the severity. Dry, limited damage with a fixed source may lower an offer modestly. Structural damage or widespread mold growth can lower it a lot. A cash offer generally works backward from the repaired value, minus the cost of damage repair, so written repair quotes are the best way to see your number.
Will my homeowners insurance help before I sell?
It depends on your policy and the cause. Policies commonly treat sudden and accidental events differently from long-term leaks or neglected maintenance, so ask your insurance company or adjuster what's covered. Our guide on selling a storm-damaged house covers how an open insurance claim interacts with a sale.
How fast can I sell a water-damaged house to a cash buyer?
With a cash offer from Eagle, closings can happen in as little as 21 to 42 days, or later if you need more time, and you pick the date. Title work and local requirements can affect the timeline.
Should I disclose water damage to a cash buyer?
Yes. Some states, such as Texas, require written disclosure of known conditions by law, and full disclosure protects you. Cash buyers are used to damaged houses and price accordingly.
What if the damage is only in the basement?
Each house is judged on its own facts, whether it is a wet basement or water elsewhere. The source, any mold and the condition of the structure matter most.
Not sure which option fits your situation? See all of our services.