If your sale price covers your mortgage payoff, selling for cash is generally easier on your credit than a deed in lieu of foreclosure. A sale that pays the loan off in full closes the account as paid, with no deed-in-lieu entry and no deficiency to chase. A deed in lieu is a negative event for credit and for future mortgage approvals, and the CFPB says a credit reporting company generally can report most negative information for seven years.
If your lender has started talking about a deed in lieu, or a letter tells you to sell quickly and get the house under contract, you need to know what each path does before you agree to anything. This guide compares the two on credit reporting, waiting periods for a new mortgage, taxes and deficiency risk. It is general information, not legal or tax advice. Foreclosure law varies by state, so confirm your details with your servicer and a local attorney.
One condition runs through all of it: a cash sale only avoids these outcomes if the price covers what you owe. If you are underwater, the picture changes, and this guide covers that too.
What Is a Deed in Lieu of Foreclosure?
A deed in lieu of foreclosure is an agreement to voluntarily turn ownership of your home over to the lender to avoid the foreclosure process, according to the CFPB. You lose the house, but you skip the auction and the court case. The name says it: you give the lender the deed instead of ("in lieu of") a foreclosure.
In practice, you contact your lender, document your hardship and offer to sign the property over. The lender decides whether accepting the deed makes sense compared with foreclosing. Ask the lender how it treats any other liens on the property, such as a second mortgage or a judgment.
Then there is the deficiency, the gap between what you owe and what the home is worth. Suppose you owe $250,000 and the home is worth $200,000 (a hypothetical example). The $50,000 difference is the deficiency. The lender may waive it or pursue it, depending on your state, your agreement and its own policies. The CFPB advises asking the lender to waive the deficiency in writing. Never assume it is forgiven unless the paperwork says so.
A deed in lieu also takes time to negotiate. Meanwhile, your missed payments can keep building up on your credit report. That is the hidden cost of waiting.
How Does Selling for Cash Work When You Are Behind on Payments?
You sell the property to a buyer, not back to the lender. The title company pays off your mortgage from the sale proceeds at closing, and the account closes as paid. When the price covers the payoff, the sale itself does not add a foreclosure or deed-in-lieu entry to your credit report.
That is the main difference. In a deed in lieu, you hand the property back and the lender treats it as a loss mitigation event. In a cash sale, you sell to a third party and repay the debt in full. The payoff includes past-due payments, late fees and accrued interest. A servicer generally must provide a payoff statement within seven business days of a written request, though loans already in foreclosure may get a "reasonable time" instead (12 CFR 1026.36).
When the sale pays the loan in full, you are not asking the lender to accept less, so it is a different process from a short sale. Still, tell your servicer you are selling. Then the two processes will not conflict. The late payments that were already reported will stay on your report for their normal period.
A sale does not automatically stop a foreclosure that has already started. Be careful here. If a sale date is set, confirm your status and dates with your servicer. For the mechanics, see what happens to your mortgage when you sell for cash. If you are already in foreclosure, see selling a house during foreclosure.
Credit Score Impact: Deed in Lieu vs. Cash Sale
Fannie Mae treats a deed in lieu as a derogatory credit event, and how much your score moves depends on where it started and what else is on your report. A sale that pays off the mortgage does not add a negative entry of its own.
| Factor | Deed in lieu | Cash sale (mortgage paid in full) |
|---|---|---|
| How it is reported | Generally treated as a negative event | Mortgage closed as paid |
| Score impact | Varies by starting score and history; can be significant | No new negative entry from the sale. Earlier late payments still show |
| How long it can stay | Negative information can generally stay up to 7 years | Late payments before the sale stay for their normal period |
| Deficiency risk | Depends on your state and agreement. Get any waiver in writing | None, because the loan is paid in full at closing |
A cash sale is not a better version of a deed in lieu. When the price covers the payoff, it avoids being one.
Why Speed Matters More Than the Label
By the time a deed in lieu is on the table, you have usually been behind for several months. Late payments keep adding up while you wait, and the deed in lieu would come on top of them. Late payments hurt whether you end up in a deed in lieu or not.
That is the argument for acting early. Move fast, and fewer late payments pile up. The ones already reported stay.
How Long Before You Can Buy Again? Mortgage Waiting Periods
After a deed in lieu, a new mortgage usually means a waiting period. For conventional loans backed by Fannie Mae, the published waiting periods are:
| Event | Standard waiting period | With documented extenuating circumstances |
|---|---|---|
| Foreclosure | 7 years | 3 years |
| Deed in lieu | 4 years | 2 years |
| Preforeclosure (short) sale | 4 years | 2 years |
Those figures come from Fannie Mae's Selling Guide, measured from the completion date. FHA, VA and USDA loans and individual lenders use their own rules and may add requirements, so talk to a mortgage professional about your situation. Lenders will also look at any late payments on your report.
The Equity Question: When a Cash Sale Works and When It Does Not
A cash sale protects your credit only if the sale price covers your payoff, including past-due amounts, fees and accrued interest. If you owe more than the home is worth, a standard sale cannot pay off the loan unless you bring cash to closing.
- You have equity. A sale that pays off the loan is usually the cleaner exit. Get a payoff figure and a cash offer, then compare them.
- You are close to even. It may still work, but margins are thin once costs are counted. Do not assume you are underwater without checking.
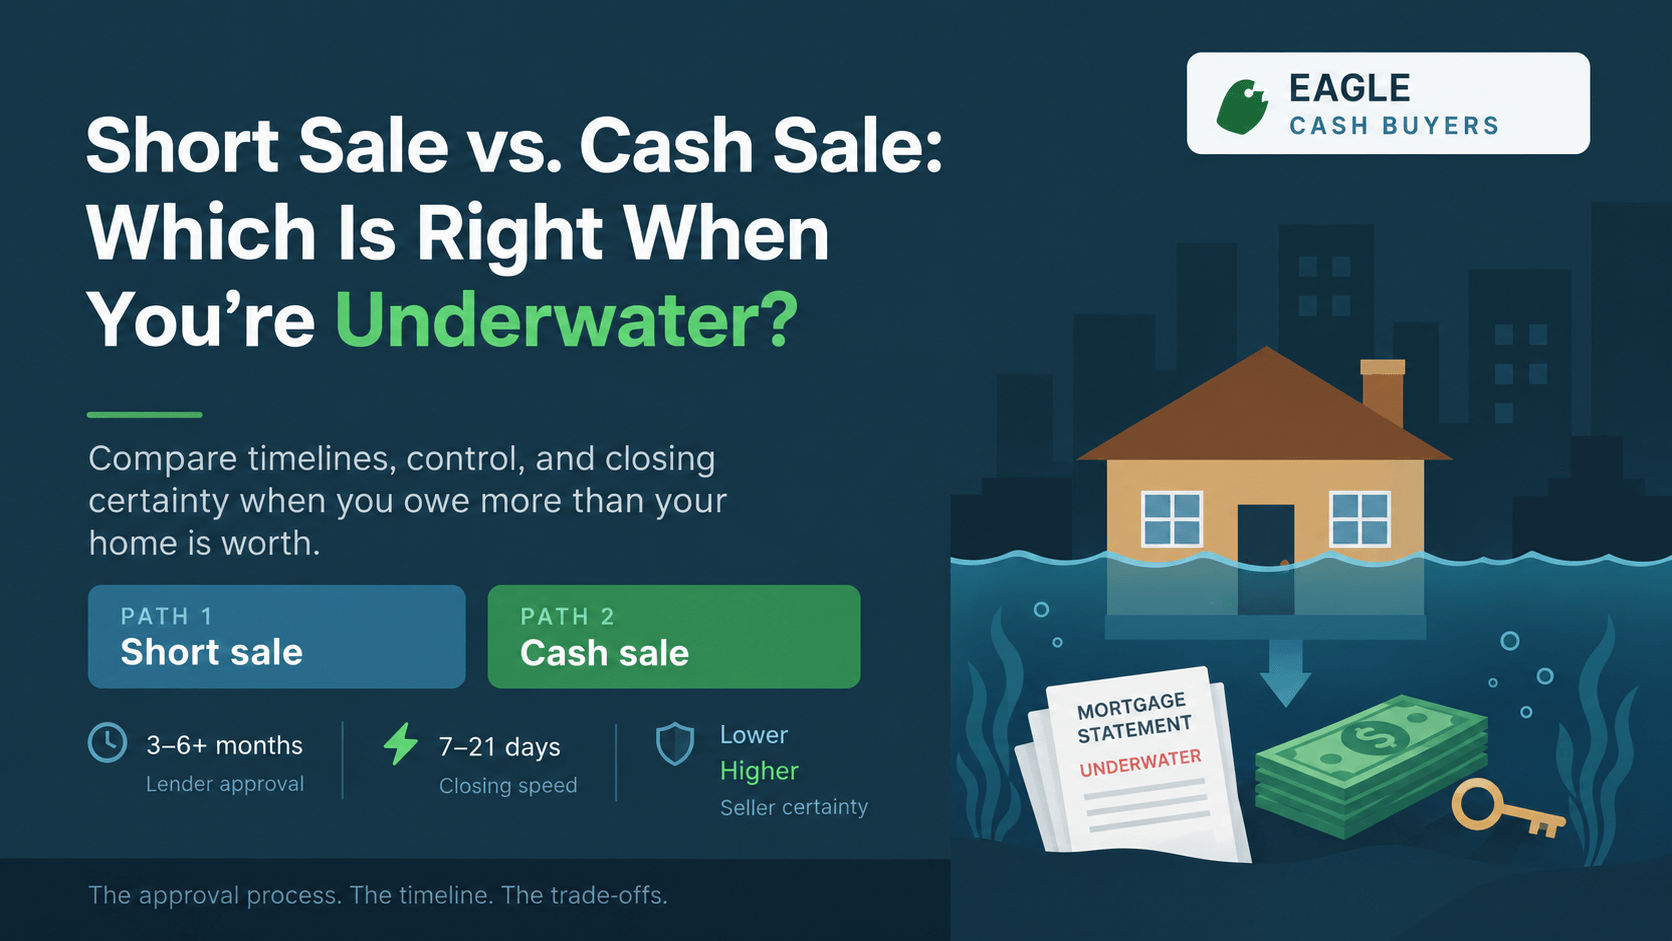
- You are underwater. Your options narrow to a short sale, a deed in lieu or foreclosure, and each one affects credit. The lender has to agree to a short sale or deed in lieu, and a cash buyer cannot promise that approval.
Not sure where you stand? Get your payoff in writing. Get a cash offer. Then compare the two numbers. Our guide on short sale vs cash sale covers the underwater case in detail.
The Tax Trap: Canceled Debt Income (Form 1099-C)
When a lender forgives part of your mortgage debt, the IRS can treat the forgiven amount as income, and you may receive a Form 1099-C. A sale that pays the mortgage in full creates no forgiven debt. Here is a hypothetical illustration with round numbers:
| Line | Amount (hypothetical) |
|---|---|
| Mortgage balance owed | $230,000 |
| Home value at the time of the deed in lieu | $185,000 |
| Forgiven amount (deficiency waived) | $45,000 |
| Example federal bracket | 22% |
| Potential federal tax on the canceled debt | $9,900 |
This is a simplified illustration, not tax advice. Exclusions may apply. The insolvency exclusion can help if your debts exceeded your assets when the debt was forgiven (Form 982). A separate exclusion for forgiven primary-residence debt applies only to debt discharged before January 1, 2026, or under a written arrangement made before then. See the IRS page on canceled debt and ask a tax professional before you decide.
Deficiency Judgments: The Risk People Miss
If a lender accepts a deed in lieu but does not waive the deficiency in writing, it may still be able to pursue the balance. Some states limit deficiency claims and others allow them unless the lender agrees not to pursue one. The rules vary, so ask an attorney what your state allows.
If you consider a deed in lieu, the most important thing to negotiate is a written deficiency waiver. Do not sign until you have it in hand. A sale that pays the loan in full leaves no balance for anyone to pursue. For related issues, see our guide on judgment liens.
When a Deed in Lieu Is Still the Right Choice
A deed in lieu can be the better option when you are significantly underwater and cannot sell for enough to cover the loan. It can make sense when:
- You have negative equity and no cash to bring to closing, and the lender will waive the deficiency in writing.
- The lender offers relocation help. The CFPB advises asking your lender or servicer about relocation help through private programs sometimes called "cash-for-keys."
- Your credit has already taken the hit from months of late payments.
- You tried to sell, the market could not support the price you needed, and the foreclosure clock is running.
In those cases a deed in lieu can be a better outcome than a completed foreclosure, because it may come with a written waiver of the deficiency. Before you agree to one, talk to a HUD-approved housing counselor. The CFPB's page on your options explains how to reach one for free or low-cost guidance.
How a Cash Sale Works When Foreclosure Is on the Table
You sell to a cash buyer, the title company pays off the mortgage from the proceeds, and the loan is closed. Eagle Cash Buyers evaluates homes in many conditions, and whether we can make an offer depends on the property, the title and our buying criteria. Closings can happen in as little as 21 to 42 days, or later if you need more time, and you pick the date. Eagle pays closing costs except your mortgage payoff, back taxes and liens, and your share of transfer tax. There is no agent commission on a direct sale.
The cash price is generally below what a fully prepared listing could bring. Compare it with your payoff and your other options. A listing can net more when you have both the time and the money to get the house ready. If a foreclosure sale date is already set, a sale may not close in time, so confirm your dates first. Our guide on selling your house fast before foreclosure covers timing, and our stop foreclosure page has more on these situations.
Real Seller Story: "That's Their Kind Way of Telling You Foreclosure Started"
A husband and wife in a small town in the Southwest had owned their house since 2014. Their mortgage rate was never locked. Around the COVID period their payment moved from about $1,500 a month to about $2,500.
"We don't have a locked-in rate, so they can do whatever they want," the husband said. "I don't make that kind of money and we can't afford it."
They fell about two months behind, roughly $5,000 in arrears on a balance of about $125,000. Then their mortgage company gave them advice that sounded helpful: sell fast, and get it under contract.
Eagle's acquisition manager recognized that advice for what it can mean. "That's their kind way of telling you that foreclosure started," he said. The husband did not argue. "Yeah, no, I 100% agree with that."
His goal was not to squeeze out the last dollar. "I'd rather not lose the home if we could," he said. "We can sell it and get out from under it, it'd be better."
One moment taught something useful. He had been quoting his price as a net figure, what he wanted in hand after the mortgage was paid. The acquisition manager first heard it as a gross sale price, so the ask sounded far higher than it was. They sorted it out and reframed the conversation around the only number that matters to a seller: "We're just discussing what you guys are walking away with in your pocket, correct?" He answered, "Yes... Makes sense."
He also asked a sharp question: would his payoff be cheaper if he paid the lender directly instead of through a sale? The honest answer was that it could go slightly either way, and that late fees from the delinquency add to the payoff.
After twelve years in the house, he asked for 30 days to move. The manager offered 45. "If you guys need it, you have it. If you don't need it, well, happy days." The couple also planned to hand the house over clean. His wife had already vacuumed, and he said leaving a mess would make them look bad.
This comes from an Eagle seller file. The record ends with the couple asking for time to talk the offer over privately, so the outcome is not confirmed. Names, the town and the mortgage servicer are withheld.
What to take from it: a servicer telling you to sell fast can be a sign that foreclosure is coming or has started, so ask for your status and dates in writing. And whatever route you choose, work out your net number first. It is the figure that decides which path is open to you. Please confirm your own foreclosure status and timeline with your servicer before you decide.
Frequently Asked Questions
How does a deed in lieu of foreclosure affect your credit?
Fannie Mae treats it as a derogatory credit event. The size of the drop depends on your starting credit score and history, and negative information can generally stay on your report for up to seven years.
Does selling your house for cash affect your credit?
The sale itself does not add a negative entry when the sale proceeds pay off the mortgage in full at closing. Late payments reported before the sale stay for their normal period.
How long do you have to wait for a mortgage after a deed in lieu?
For conventional loans backed by Fannie Mae, the standard wait is four years, or two with documented extenuating circumstances. Other loan programs and lenders use different rules.
Is a deed in lieu better than a foreclosure for your credit?
Both are serious negative events for your credit score. A deed in lieu may come with a written deficiency waiver if you negotiate one, and Fannie Mae's waiting period after it is shorter than after a foreclosure (four years versus seven for standard cases).
Can I sell my house to avoid a deed in lieu?
If the price covers your payoff and you have time, yes. If you are underwater, a standard sale cannot cover the debt and your options narrow to a short sale, a deed in lieu or foreclosure.
Can I still sell my house if I am behind on payments?
Generally yes. The payoff, including missed payments, fees and interest, is paid from the proceeds at closing. If a foreclosure has already started, confirm your dates with your servicer.
What is canceled debt income?
If a lender forgives part of what you owe, the IRS can treat it as taxable income and you may get a Form 1099-C. Exclusions exist, such as the insolvency exclusion (Form 982), so ask a tax professional.
The Bottom Line
If you have equity and enough time, selling can protect your credit more than a deed in lieu, because the mortgage closes as paid and no deficiency or mortgage waiting period comes from the sale itself. If you are underwater, a deed in lieu may be the right path, but negotiate a written deficiency waiver before you sign.
Either way, speed matters. Each missed month does its own damage, and the earlier you act, the more options you keep. See mortgage default consequences for the full picture.