Your mortgage servicer keeps calling. You have a cash offer on the table. And you're wondering: what actually happens to my mortgage when I sell? Does the buyer take it over? Do I have to pay it off first? Who handles all of this?
When you sell your house for cash, your mortgage is paid off at closing from the sale proceeds. The title company or closing attorney coordinates the payoff with your lender, deducts the balance from the buyer's funds, and sends you the difference. You don't need to pay off the mortgage before selling. In most cases you don't need to chase your lender yourself, because the closing agent handles that. Simple.
This guide walks through how that process works in a cash sale, what comes out of your proceeds, and what to know about payoff statements, escrow refunds and second liens.
Can You Sell a House for Cash if You Still Have a Mortgage?
Yes. You can sell your house for cash even if you still owe on your mortgage.
Many homeowners still owe on their mortgage when they sell. Having a balance doesn't stop you. It just means the mortgage gets paid off from the sale proceeds at closing, and you receive whatever is left.
In a cash sale, there's no buyer's lender involved. That usually means no lender appraisal, no wait for a bank to approve the buyer's loan, and no risk of financing falling through at the last minute. You still have a contract, a title search and a closing.
One clarification for the reader: this article is about selling to a cash buyer (an investor or cash home buying company) while you still have a mortgage. Not about buying a house with cash.
How the Mortgage Payoff Works Step by Step in a Cash Sale
The mortgage payoff in a cash sale follows the same general process as any home sale, with one big difference: there's no buyer's lender in the picture, so one party that could slow things down is gone. Here's the sequence.
Step 1: Accept the Cash Offer
You review and accept a written offer from the cash buyer. The buyer provides proof of funds showing they have the money to close. Read it closely, and ask any buyer, including Eagle Cash Buyers, to put every cost in writing.
Step 2: The Title Company Requests Your Payoff Statement
After you accept, the title company (or closing attorney, depending on your state) contacts your mortgage lender to request an official payoff statement. This document shows the exact amount needed to clear your loan as of a specific date.
You don't usually need to do this yourself, but you can request one independently to verify the number. More on what's actually on that statement, and why it's different from your monthly balance, in the next section.
Step 3: The Title Search Reveals All Liens
The title company searches county records for every lien on the property: first mortgage, second mortgage, HELOC, property tax liens, HOA liens, IRS liens, judgment liens. Every lien must be cleared before the buyer can receive clear title.
Eagle pays closing costs except the seller's mortgage payoff, back taxes and liens, and the seller's share of transfer tax. In some states a closing attorney, not a title company, handles the closing.
Title searches sometimes turn up surprises: liens nobody knew about, deeds that were never transferred after a death, or county records that haven't caught up. The title search catches them, and the title company works through each one before closing.
Step 4: Closing Day, Funds Are Distributed
The buyer's cash funds go into escrow. The title company distributes the money in order of lien priority (see the full breakdown below). Your mortgage lender receives the payoff amount directly from the title company. You receive your net proceeds by wire transfer or cashier's check, your choice.
Step 5: Lien Release and Loan Closure
Once the lender receives and confirms the payoff, they release their lien on the property. The "satisfaction of mortgage" (or "deed of reconveyance" in some states) is recorded with the county. The timing varies by state. You can check with your county recorder's office to confirm it was recorded.
Your loan is closed. Done.
For more on how the title process works in a cash sale, this guide to title insurance covers what to expect from the seller's side.
Where Does the Money Go? The Proceeds Waterfall
When you sell for cash, the proceeds are paid out at closing in the order set by lien priority, and the title company works that order out from the recorded documents. The order can vary by state and by lien type, especially for tax liens, so treat the table as a typical pattern, not a rule for every state.
Here's a typical pattern:
| What gets paid | Notes | Who handles it |
| Property tax and special assessment liens | Priority depends on state and local law | Paid from proceeds at closing |
| First mortgage payoff (principal, accrued interest and fees) | Per your payoff statement | Title company pays the lender directly |
| Second mortgage or HELOC, if any | Per that lender's payoff statement | Title company pays the second lender |
| HOA, IRS, judgment and other recorded liens, if any | Priority varies by state and lien type | Paid from proceeds at closing |
| Seller-side closing costs | Eagle pays closing costs except your payoff, back taxes and liens, and your share of transfer tax | Title company or closing attorney |
| Your net proceeds | Everything remaining | Wire transfer or cashier's check to you |
With Eagle, there's no agent commission on a direct sale, and we pay closing costs except your mortgage payoff, back taxes and liens, and your share of transfer tax. So the main deductions are your own payoff, any liens and your transfer tax share.
That's a meaningful difference when you run the actual numbers.
What Your Payoff Statement Actually Means (And Why It's Not Your Balance)
Your mortgage payoff amount is not the same number you see on your monthly statement. Your payoff includes interest due through the day you pay off the loan, and it may include other fees you haven't yet paid. Your current balance may not show all of that.
The gap changes every day because interest keeps accruing until the payoff date.
What's on a payoff statement:
- Remaining principal balance
- Interest through the anticipated payoff date
- Any unpaid fees, such as late fees
- Any prepayment penalty, if your loan has one
A payoff statement is calculated as of a specific date. If closing moves, a new statement may be needed. The title company typically requests it for you after you accept an offer.
Example with hypothetical numbers: monthly balance vs. payoff amount
Your October mortgage statement shows: $164,200 remaining balance.
Your payoff statement (good through October 30) shows: $164,847.
The difference is $647. Here is how it breaks down:
$580 in accrued interest (21 days at $27.62 per day on a 6.14% rate)
$35 in a hypothetical unpaid fee
$32 in another hypothetical unpaid fee
If closing moves to November 5, the payoff rises by about $138 (5 more days of interest). Small numbers. Real ones depend on your loan.
Practical tip: You can request a payoff statement independently before accepting any offer, so you know your approximate net proceeds up front. Federal rules generally require a servicer to send a payoff statement within seven business days of a written request (see 12 CFR 1026.36).
From Our Transactions: When Your Servicer Starts Calling
One seller working with Eagle, a widow in the Pacific Northwest, had a servicer to deal with in the middle of a sale. After her husband passed away, she'd taken out a HELOC to cover repairs on the house. She'd also fallen behind on property taxes, though not critically.
Then her mortgage servicer started calling, and she froze. That moment is more common than most people realize: the phone rings, it's your lender, and you don't know what to say because you're in the middle of trying to sell.
The guidance she received was simple and specific:
- Answer the call. Don't dodge it.
- Tell them you're selling.
- Ask for a payoff letter, the document stating exactly what's owed to clear the loan.
- Forward it to the title company.
- Don't send the lender a payoff yourself. The balance gets settled at the closing table out of the proceeds.
Five steps that turn a frightening phone call into a piece of paperwork. Keep making your regular payments until closing, as covered below. The point is that the payoff itself is not something you send. The mortgage balance was to be settled at the closing table out of the proceeds. Her plan was to buy her next home outright, near her daughters. "I don't want another mortgage," she said.
(This account is from an Eagle seller file. The record does not confirm whether the sale ultimately closed.)
Cash Sale vs. Traditional Sale: How the Mortgage Payoff Differs
The mortgage gets paid off the same way in both a cash sale and a traditional sale. The difference is everything around it: the timeline, the costs deducted from your proceeds, and the risk of the deal falling through.
| Factor | Cash sale (as-is) | Traditional sale (agent and financed buyer) |
|---|---|---|
| Sale price | Usually lower, because the buyer takes on repairs and resale costs | Usually higher, often after prep and repairs |
| Mortgage payoff | Paid from proceeds at closing | Paid from proceeds at closing |
| Agent commissions | None on a direct sale with Eagle | Negotiated |
| Seller closing costs | Eagle pays closing costs except your payoff, back taxes and liens, and your share of transfer tax | Varies by state and contract |
| Repairs and prep | None on your side | Often needed to win a financed buyer |
| Carrying costs while you wait | Fewer months, since Eagle closings can happen in as little as 21 to 42 days | Usually more months of mortgage, taxes and insurance |
| Risk the deal falls through | Fewer contingencies | Financing, appraisal and inspection contingencies |
A traditional sale can net more when you have both the time to wait out a listing and the money to put the house right first. If either is missing, the comparison changes, because months of mortgage payments and repair bills count against the higher price. The right answer comes from comparing real net figures for your own house.
We break down this math in more detail in our cash offer vs. agent comparison. And if you want to understand how a cash buyer arrives at the offer number, this explanation of the ARV formula walks through the calculation.
When Do You Stop Paying Your Mortgage When Selling for Cash?
You keep paying your mortgage until the sale closes. Don't skip one. A missed payment can trigger late fees that raise your payoff amount, can affect your credit, and in some cases can complicate the closing.
The good news with a cash sale: the time between accepting the offer and closing can be as little as 21 to 42 days, or longer if you need more time. That means you may only need to make one additional mortgage payment, sometimes none, depending on where your closing date falls relative to your payment schedule.
In a traditional sale, you may make several more mortgage payments while waiting to close, and those carrying costs, along with taxes and insurance during the wait, come straight off what you keep.
What happens if your closing date falls near your payment due date? The title company and your lender coordinate. The payoff statement shows interest through a stated date. Ask the title company how your last payment will be handled, so you don't pay twice.
What Happens to Your Escrow Account After You Sell?
If your mortgage includes an escrow account for property taxes and homeowners insurance, you'll receive a refund of the remaining balance after your loan is paid off. This refund is separate from your closing proceeds.
Federal rules (12 CFR 1024.34) require your mortgage servicer to return any remaining escrow balance within 20 business days (not counting weekends and legal public holidays) after you pay off the loan. The check comes separately from the closing proceeds.
A few things to know:
- This escrow account is not the same as closing escrow. It's the account your lender used to hold your monthly tax and insurance deposits.
- The refund amount depends on when taxes and insurance were last paid.
- The check comes from your mortgage servicer, not the title company.
- If it hasn't arrived after 20 business days, contact your servicer with your payoff confirmation.
Practical tip: Update your mailing address with your servicer before closing so the check doesn't go to the house you just sold.
What If You Owe More Than the House Is Worth?
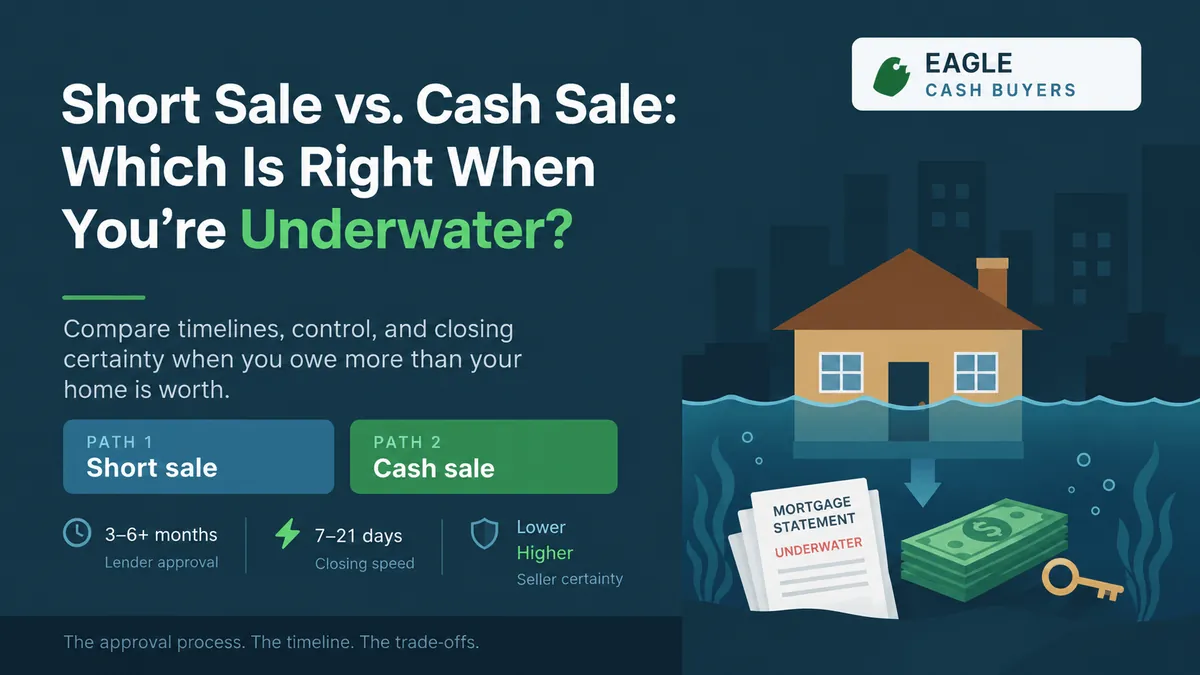
If you owe more on your mortgage than the home is worth (an underwater mortgage, or having "negative equity"), you can still sell. But the sale proceeds won't fully cover your mortgage payoff, so you'll need to address the shortfall.
Your options:
- Bring cash to closing. If the gap is small, some sellers pay the difference from savings.
- Negotiate a short sale. Your lender agrees to accept less than what's owed. This requires lender approval and can be slow. In some states, as the CFPB notes, the lender can still sue for the shortfall, so ask for a written waiver. It may also affect your credit.
- Ask a buyer what it can do. Whether a lender will accept less than the full payoff is the lender's decision. Ask any buyer, in writing, how it would handle a shortfall.
- Delay selling. If the market may improve and you can afford to wait, building more equity may be the better move.
Talk to your lender, a HUD-approved housing counselor or an attorney before assuming you're stuck. You may have more choices than it feels like. For a deeper comparison of these paths, our short sale vs. cash sale guide covers the full picture.
What About a Second Mortgage, HELOC, or Other Liens?
If you have a second mortgage, HELOC, or other liens on your property, they all get paid off at closing from the sale proceeds, in order of lien priority. The order depends on state law and recording dates, and the title company works it out from the recorded documents. You receive whatever is left after all secured debts are cleared.
Every secured lien must be satisfied before the title can transfer to the buyer. The title company identifies all liens during the title search and coordinates payoffs with each lender.
HELOC early-termination fees: Some HELOCs charge a cancellation fee for closing early, usually within the first two or three years. Check your loan agreement or call your HELOC lender before closing.
Property tax liens and HOA liens are typically paid at closing from the seller's proceeds. With Eagle, back taxes and liens are not part of the closing costs we pay, so they come out of your proceeds.
IRS or judgment liens generally have to be resolved before the buyer can receive clear title. The title company will flag them.
If your proceeds don't cover all the liens, you may need to bring cash to close or ask the lien holders about reduced payoffs.
Do You Face a Prepayment Penalty for Paying Off Your Mortgage Early?
Not all mortgages have a prepayment penalty. Under federal rules (12 CFR 1026.43(g)), a covered home loan can carry one only if it is a fixed-rate qualified mortgage that is not higher-priced. The penalty can't exceed 2 percent of the amount prepaid in the first two years or 1 percent in the third year, and none can apply after three years.
Older loans and loans outside those rules may follow different terms. A penalty typically applies when you pay off the whole balance within a set period, usually three or five years.
How to check:
- Read the "Prepayment" section of your original mortgage note or promissory note.
- Call your loan servicer and ask directly.
- Request your payoff statement. Any prepayment penalty will be included in the total.
If a penalty exists, it's deducted from your proceeds at closing just like any other cost. Even a small percentage of a large balance is worth knowing about in advance. It shouldn't stop you from selling, but it changes your net proceeds.
Frequently Asked Questions
Can you sell a house for cash if you still have a mortgage?
Yes. Many home sellers still have a mortgage balance when they sell. At closing, the cash buyer's funds are used to pay off your remaining mortgage, and you receive whatever is left after the payoff and any other deductions. You don't need to pay off the mortgage first.
Who pays off the mortgage when you sell your house?
The title company or closing attorney handles the mortgage payoff. They request a payoff statement from your lender, collect the buyer's funds, and pay your lender directly at closing. You don't write a separate check or make a phone call. The payoff happens automatically as part of the closing process.
Do I have to pay off my mortgage before selling to a cash buyer?
No. Your mortgage is paid off at closing using the sale proceeds. The title company coordinates the payoff with your lender. You just need the sale price to cover your remaining balance, plus any other liens on the property.
How long does it take to pay off a mortgage after a cash sale?
The title company sends the payoff to your lender at or right after closing. Your lender then processes it and closes your loan. The lien release is recorded with the county, and timing for that varies by state. Ask the title company for payoff confirmation.
What happens to the escrow account after I sell my house?
Your mortgage servicer refunds the remaining escrow balance after the loan is paid off. This is the money collected monthly for property taxes and insurance. Federal rules require the servicer to send this refund within 20 business days after payoff. The check comes separately from your closing proceeds.
Do you keep paying your mortgage while selling?
Yes. Continue making your regular monthly mortgage payments until closing day. Missing a payment can trigger late fees, increase your mortgage payoff amount, and affect your credit. With Eagle, closings can happen in as little as 21 to 42 days, so you may only make one additional payment after accepting the offer.
Is there a penalty for paying off your mortgage early when selling?
Not always. Federal rules limit when a home loan can carry a prepayment penalty, but some loans have one, so check. Check your loan documents or call your servicer to confirm before closing.