A cash offer on a house is an offer from a buyer who pays the full price from their own funds. No mortgage. No lender to approve the loan, order an appraisal or change its mind three weeks in. The buyer proves they have the money, you agree on a price, and the sale moves toward closing on a schedule that doesn't depend on an underwriter you will never meet.
That simplicity is the whole appeal. It has a price. This guide explains what a cash offer is, how it differs from a financed offer, how a cash sale works from the first offer to the money in your account, what you gain and what you give up, and how to check a buyer before you sign anything, so you can decide with the full picture in front of you.
What Is a Cash Offer on a House?
Think of selling a used car. One buyer loves it but has to ask a bank for a loan first, and the bank, which has never seen the car and has its own rules, can say no. Another buyer arrives with the money ready. Same car. Very different certainty.
Houses work the same way, more or less. "Cash" doesn't mean a suitcase of bills. Not literally. It means the purchase isn't financed by a mortgage, and the buyer pays at closing, usually by wire transfer or cashier's check handled by a title company or attorney. Before you accept, the buyer should show proof of funds. That can be a recent bank statement or a letter from a financial institution, and you are entitled to ask for it.
Cash buyers come in several kinds. Some are individuals buying to live there. Others are investors and investment companies that buy houses to repair, rent or resell, and everything below applies mainly to those investor-style offers, because that's what most sellers who search for a "cash offer" end up receiving.
Cash Offer vs. Financed Offer: The Real Differences
Two things separate these offers. One is where the money comes from. The other is which conditions come with it, and those conditions shape how likely the deal is to close. Here is a general comparison, and individual deals vary.
| Feature | Cash offer | Financed offer |
|---|---|---|
| Funding source | The buyer's own funds | A bank or mortgage lender |
| Lender approval | Not needed | Required, and it can fall through |
| Appraisal | No lender appraisal. The buyer decides how to value the house | Usually required by the lender |
| Contingencies | Often fewer, but the contract still sets terms | Financing and appraisal contingencies are common |
| Closing date | Often flexible and can be faster | Tied to the lender's timeline |
| Price | Often below what the open market might pay | Can be higher, if the sale goes through |
The main risk in a financed sale is the loan. Underwriting takes time. An appraisal that comes in below the price can force a renegotiation, or end the deal outright after you have already started packing. A cash offer removes that step. You still have a contract, a title search and a closing, so nothing is certain until the money arrives. But one way a sale can fall apart is gone.
How a Cash Sale Works, Step by Step
If you've only sold through an agent, a cash sale can feel mysterious. It isn't. It follows the same legal steps as any other sale, minus the lender, and the usual order is below, though every company and every state adds its own details that you should confirm in your agreement.
- You share details about the house. Address, condition, whether you owe a mortgage, and your timeline, along with photos if you have them, since they let a buyer give you a realistic number sooner.
- The buyer reviews the property. Often that means photos, public records and a conversation. Some buyers also visit in person.
- You get an offer. A good buyer explains how the number was built. If not, ask.
- Proof of funds. The buyer should be able to show they have the money, for example through a bank statement or a letter from a financial institution.
- You sign a purchase agreement. It sets the price, the closing date, who pays which costs, and what happens if something changes.
- A title company or attorney opens the file. Which one depends on your state. It searches the title, resolves what it finds with you and the buyer, and prepares the closing documents.
- You close and get paid. You sign, the buyer's funds are delivered, any mortgage is paid off out of the proceeds, and you receive the remainder.
No lender means no mortgage underwriting and no lender appraisal. It does not mean no contract, no title work and no closing.
The Cash Sale Timeline
Without a lender, you and the buyer can set a closing date that suits you both. With Eagle Cash Buyers, closings can happen in as little as 21 to 42 days, or longer if you need more time, and you pick the date. Other buyers advertise different speeds. Ask for the date in writing.
The title work is usually what sets the pace. The title company searches public records for liens, unpaid taxes, judgments and ownership problems, and anything it finds has to be cleared before closing can happen. A house with a clean title can move quickly. One with an unpaid lien, a missing heir or an unrecorded deed takes longer, sometimes much longer. Our guide to selling a home with liens or back taxes explains how those are handled.
If you have a mortgage, you will need a payoff figure from your servicer. Under federal rules (12 CFR 1026.36(c)(3)), a servicer must send a payoff statement within a reasonable time, and no more than seven business days after a written request, so ask early. Our guide on what happens to your mortgage when you sell for cash covers the payoff in more detail.
Closing Day
Closing day is short. You sign the final documents at a title company or attorney's office, or sometimes with a mobile notary or by mail, and then the funds are released to you by wire or check. Details differ by state.
A few practical points help. None are hard.
- Have a government ID, the property's details and your mortgage account information ready.
- Gather the keys, the garage openers, and any warranties or paperwork the buyer asked for, so nothing delays the handover.
- Confirm wiring instructions by phone, using a number you already trust, with the title company before you send or accept any money, because scammers send fake wiring instructions that look like they come from a closing agent (CFPB).
- Keep copies of all of it.
What Still Comes Out of Your Proceeds
"Cash sale" can sound like "no deductions." Not quite. Some things come out of the price whoever the buyer is:
- Your mortgage payoff. It's paid from the sale proceeds at closing.
- Back taxes and liens. They have to be cleared for the title to pass.
- Your share of transfer tax. Rules and rates vary by state, county and city.
- Prorations. Property taxes and some utilities are usually split between you and the buyer by closing date.
Our guide on closing costs in a cash sale goes through them line by line.
The Real Benefits of Accepting a Cash Offer
Sellers often pick a cash offer for speed, certainty and simplicity, not for the highest price. Those matter most when life has a deadline, such as a job that starts in three weeks, an inherited house you can't afford to carry, or a mortgage that's falling behind and putting your credit at risk.
Certainty and Speed
A financed buyer brings many "what ifs." Will the loan clear? Will the appraisal hold? A cash sale removes the lender from that list. It also lets you and the buyer pick a closing date that fits. With Eagle Cash Buyers, closings can happen in as little as 21 to 42 days, or longer if you need more time, and you choose the date.
The Simplicity of an As-Is Sale
Many cash buyers purchase houses as they are. That can let you skip a lot:
- Repairs: you don't have to replace a worn roof or an old HVAC system to pass a buyer's inspection.
- Staging and showings: no open houses, and no keeping the place spotless for last-minute tours.
- Agent commissions: there's no agent commission on a direct sale with Eagle.
"As-is" doesn't mean nothing can change. A serious buyer still confirms the condition, usually through photos or a walkthrough, and the contract spells out what happens if something new turns up. Ask up front whether the offer can change after that visit.
Looking at Both Sides of a Cash Offer
Here is the honest part. A cash offer from an investor or home buying company is often below what the open market might pay. The buyer isn't being arbitrary, because the number reflects work and risk the buyer takes on, and a house in good condition that you have time to list may well bring more on the open market.
Why Is the Price Different?
An investor starts from what the house should be worth after repairs, then subtracts the costs and risks of getting there and of reselling it, which usually include the following.
- Repair costs: small fixes and big ones alike, so you don't have to pay for them.
- Holding costs: property taxes, insurance and utilities from the day they buy until the day they resell or rent.
- Resale costs: the closing costs and commissions the buyer will pay when they sell.
- Margin and risk: a profit for the work, and a cushion in case the market shifts or repairs run over.
Our guide on how cash home buyers calculate their offer walks through that math in detail.
So the real trade is simple. You accept a lower price in exchange for speed, certainty and convenience. A listing can net you more when you have both the time and the money to put the house right and wait for the right buyer. A cash sale can make more sense when repairs are large, the clock is tight, or you can't carry the costs of waiting. Neither is always better. Our comparison of a cash offer vs listing with an agent shows how to weigh them with your own numbers.
Costs matter too. At Eagle, we pay closing costs except your mortgage payoff, back taxes and liens, and your share of transfer tax. Ask any buyer, including us, for a written net figure that shows every item, line by line, before you sign.
Exploring Your Options for Finding Cash Buyers
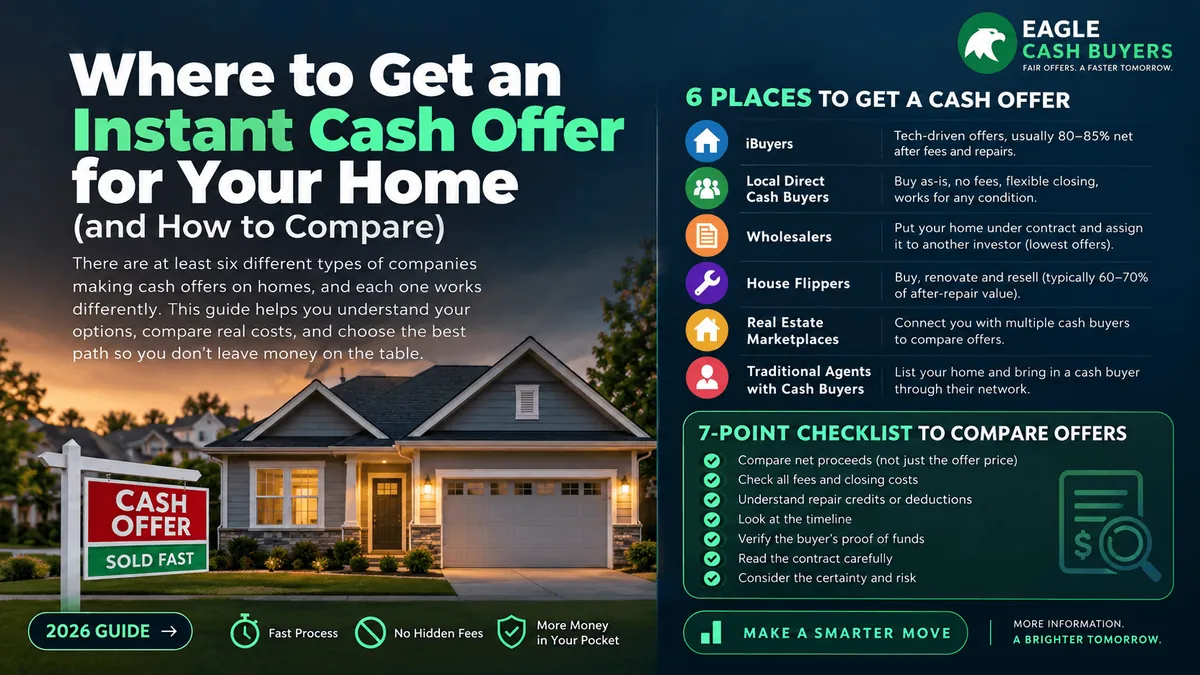
The market for cash buyers is bigger than most people think. You'll usually meet three groups.
- Individual investors: local flippers and landlords. They can be flexible, but their funding, experience and reliability vary.
- iBuyers: technology companies that use algorithmic pricing, which researchers found works best on homes that are liquid and easy to value. Our guide on cash buyers vs iBuyers compares the two.
- Home buying companies: investment companies that buy at scale. Some buy directly and some sign a contract and assign it to another buyer. Eagle may do either, and the agreement discloses it before you sign.
Each mixes speed, convenience and price differently, so the best fit depends on you. Decide what matters most first. Our guide to getting a cash offer and comparing several walks through where to look.
How to Vet a Potential Cash Buyer
Cash buying draws serious professionals. It also draws people with no money and no intention of closing, so a little research goes a long way toward protecting you from wasted weeks and worse.
- Ask for proof of funds: a bank statement or a letter from a financial institution.
- Check track record and reviews: how long the company has operated, whether past sellers describe real experiences, and what its Better Business Bureau profile shows. Eagle is rated A+ by the BBB.
- Read the contract: look for who pays which costs, whether the buyer can assign the contract, what the closing date is, and what could change the price.
- Never pay upfront: a buyer shouldn't ask you for money to receive an offer.
- Let a professional review it: an attorney or an agent you trust can read the agreement before you sign. A good buyer welcomes it.
Our post on how to tell if a cash company is legit lists the red flags. Read it first.
Taxes on a Cash Sale
Selling for cash doesn't change how the sale is taxed. The same rules apply. According to the IRS, many homeowners can exclude up to $250,000 of gain from income, or up to $500,000 for joint filers, if they owned and lived in the home for at least two of the five years before the sale. Exceptions apply, so read IRS Topic 701 and talk to a tax professional. Our guide on capital gains tax on a cash sale covers more.
Frequently Asked Questions
Is a cash offer always lower than a financed offer?
Offers from investors and home buying companies are often below what the open market might pay, because the buyer prices in repairs, holding costs, resale costs and a margin. A cash buyer who plans to live in the home may pay closer to market. Compare what you would net. Not the headline price.
Do I need an agent to accept a cash offer?
No. You can sell directly, and on a direct sale with Eagle there's no agent commission. You can still have an attorney or an agent you trust review the contract, and we encourage sellers to take their time with it.
Can a cash buyer still back out?
Yes, depending on the contract. A cash offer removes lender risk, but problems with title, with the condition of the house or with the buyer's own plans can still end a deal. That's why the contract terms and the buyer's track record matter so much.
How long does a cash sale take?
It varies. The cash buyer, title work and paperwork speed all matter. With Eagle, closings can happen in as little as 21 to 42 days, or longer if you need more time. Get the date in writing.
Can I sell for cash if I still have a mortgage?
Yes, if the sale price covers what you owe. The mortgage payoff is made from the proceeds at closing. If you owe more than the house is worth, the options are different, so speak to your servicer and a local attorney.
Who handles the closing?
A title company or a real estate attorney, depending on the state. They search the title, prepare the closing documents and handle the funds.
Not sure which option fits your situation? See all of our services.