You searched for an instant cash offer for your home. That means you want two answers: who will give you one, and how to tell a good offer from a bad one. Both are more complicated than most articles admit.
Several kinds of companies make cash offers on homes. Their business models differ. An iBuyer, a direct buyer and a wholesaler might all call themselves "cash home buyers," yet the offer you get, the deductions you see at closing and the amount you actually keep can differ a great deal on the very same house, which is why the price alone never tells you which deal is better.
This guide covers who makes an instant cash offer for your home, what "instant" really means, and a seven-point checklist for comparing offers side by side. It also shows the method with clearly hypothetical numbers. If you want the deeper math on listing instead, our guide to cash offer vs. listing with an agent covers it line by line.
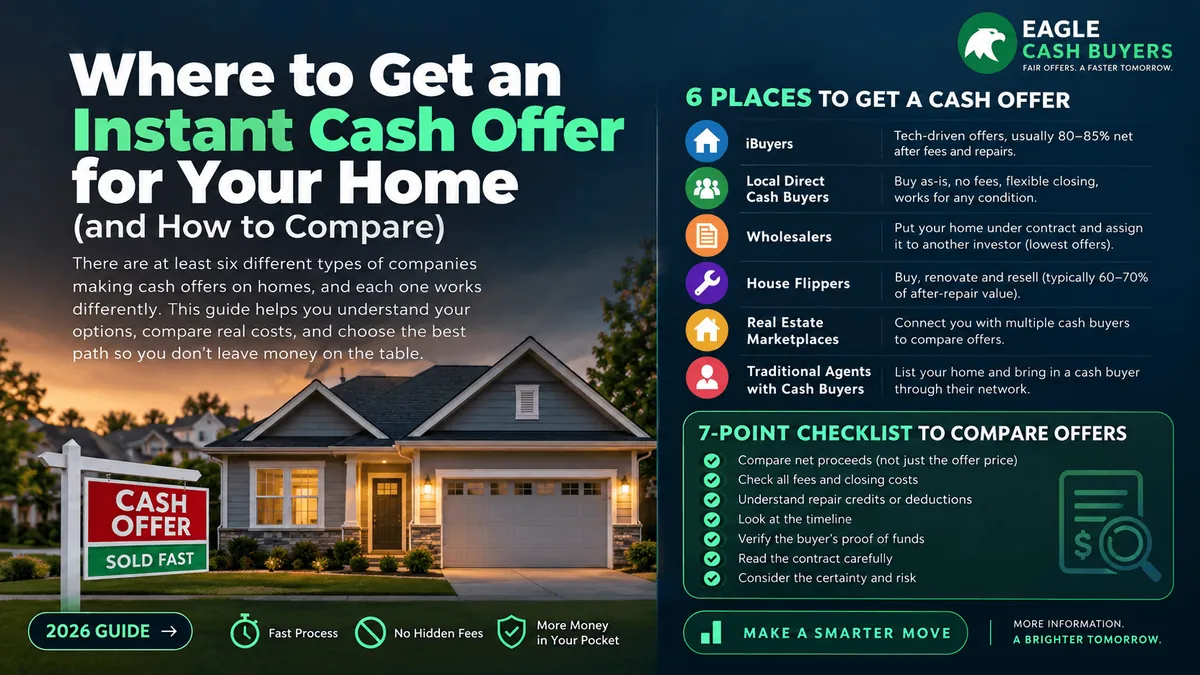
Where to Get an Instant Cash Offer: Six Types of Buyers
Not every cash offer comes from the same kind of buyer. Each type has its own pricing model, its own fee structure and its own level of certainty, and knowing which one you are talking to is the first step toward comparing offers fairly. Start there.
1. iBuyers
iBuyers are technology-driven companies that use automated valuation models to produce a quick offer from your address and public data. Some charge a service fee, and some adjust the offer after an in-person inspection, so read the terms before you assume the first number is the last.
iBuyers generally buy homes that fit their criteria, in the markets where they operate. A home with major repairs, a rural location or a complicated title may fall outside them. Check first.
2. Direct cash buyers
Direct buyers are real estate investment companies that buy homes with their own capital or private funding, and Eagle Cash Buyers works this way. We buy many properties as they are, including homes that need work. Whether we can make an offer at all depends on the property, the title and our buying criteria.
On a direct sale with Eagle there is no agent commission, and we pay the closing costs except for your mortgage payoff, any back taxes or liens, and your share of transfer tax. The offer is below market value, because we take on the repairs, the holding costs, the risk and the resale, and the price reflects all of that. Our guide to how cash home buyers calculate their offer shows where that gap comes from.
3. Wholesalers
A wholesaler puts your home under contract and then assigns or sells that contract to another investor for a fee, which means the person who made you the offer may not be the person who actually closes on your house. That is a recognized way of doing business. It is not automatically a problem. The risk lies in a lack of transparency, so ask early who the end buyer will be.
A wholesaler needs room for its own fee on top of the final buyer's margin, so offers can come in lower. Not always. Compare in writing.
4. House flippers and fix-and-flip investors
These buyers purchase homes to renovate and resell. They work from the same basic formula as other investors: after-repair value, minus repairs, minus costs, minus profit. Some are formal companies and some are individuals. A few know one neighborhood better than anyone. Ask for proof of funds and a closing date, since a small operation may depend on financing of its own and a delay on their side becomes a delay on yours.
5. Franchise and network buyers
Some "we buy houses" brands operate as a network of independently owned local franchises. The offer you receive comes from the local owner, so judge that operator on the things you can check yourself, such as reviews, references, proof of funds and how clearly they explain their numbers, not just on the name over the door.
6. Offer marketplaces
A marketplace collects your property details once and passes them to its network of buyers, who send offers. The convenience is real, and it saves time. The limit is that a marketplace is only as good as the buyers in your area. Some earn their fees from the buyer side while others may charge the seller, so ask how the platform is paid before you hand over your details.
Our guide on cash home buyers vs. iBuyers vs. traditional agents compares the main routes in more detail.
What "Instant" Actually Means
When a company advertises an instant cash offer, it almost always means a preliminary estimate built from limited information. It is not a firm, binding offer you can accept today. The distinction matters. A preliminary number can change after the company sees the property or finishes its due diligence, sometimes by a lot.
- Preliminary offer: built from your address, public data and whatever you tell them over the phone or online. An estimate. Not a contract.
- Firm written offer: issued after the buyer evaluates the property, through a walkthrough, a contractor assessment, a title check or all three. It is the number on the purchase agreement.
Ask three questions before you rely on any instant number. Is this offer subject to change after inspection? If so, what is the most it could drop? Will you put that limit in writing?
At Eagle, we talk through your situation and the condition of the home, and then put an offer in writing. If the walkthrough or the contractor assessment shows something different from what we were told, we explain the change. You see how the number was built.
The honest framing: an instant offer is where a conversation starts, not where it ends. The firm offer comes after due diligence. That holds for every type of buyer, so treat any figure given before someone has seen the property as a direction, not a decision, and plan around the written number only.
How to Compare Cash Offers: The 7-Point Checklist
Two offers with the same price can leave very different amounts in your pocket, depending on fees, closing costs and whether the offer is firm. Use these seven points on every offer you get. Our guide to negotiating with a cash home buyer explains what to do once you have the answers.
- Offer price. The number they quote. It matters, but it is only the starting point, and on its own it tells you very little about what will reach your bank account.
- Fees and service charges. Ask: "Are there any fees or service charges deducted from my proceeds at closing?" Listen for "admin fee" and "processing fee."
- Who pays closing costs. Some buyers pay them, some pay only part, and some leave them to you. Ask for a net sheet that shows every cost taken out of your proceeds. The CFPB notes that who pays which closing costs depends on the contract and state law, and our guide on what sellers pay in a cash sale goes deeper.
- Net proceeds. Offer price, minus fees, minus closing costs, minus repair credits, minus your own payoff, and then compare the result to the same figure from the other offers. Net to net. Never price to price.
- Firm or preliminary. Can the offer drop after inspection? By how much? Can you walk away without penalty if it does, and is that stated in the contract rather than promised over the phone?
- Who the actual buyer is. Will the company buy with its own funds, or assign the contract? Either can be legitimate, but it should be disclosed before you sign. Ask for proof of funds.
- Timeline and flexibility. When can they close? Can you pick the date? What if you need extra time after closing? We let you pick the closing date and can offer post-occupancy options when you need them.
A blank comparison worksheet
Copy this framework when you have real offers in hand.
| Comparison point | Offer A | Offer B | Offer C |
| Offer price | |||
| Fees and service charges | |||
| Closing costs (who pays) | |||
| Net proceeds | |||
| Firm or preliminary? | |||
| Who is the actual buyer? | |||
| Closing timeline |
A Hypothetical Example: Price Is Not Proceeds
These numbers are hypothetical. We picked round figures to show the method. They are not what any specific buyer type pays, and they are not a quote for your home. The idea is simple: the offer with the highest price is not always the offer with the highest check.
| Line item (hypothetical) | Offer A | Offer B | Offer C |
| Headline offer | $270,000 | $250,000 | $258,000 |
| Service fee (assumed 5%) | ($13,500) | $0 | $0 |
| Repair credits after inspection | ($8,000) | $0 | $0 |
| Seller closing costs | ($3,000) | $0 | ($2,000) |
| Price revised after due diligence | $0 | $0 | ($15,000) |
| Net before payoff | $245,500 | $250,000 | $241,000 |
Offer A looked best on day one and finished second, after the fee and the credits came out. Offer C looked second best and finished last, because its number was preliminary and was revised after due diligence. Offer B was the lowest on paper. It was the highest in the end. Your mortgage payoff comes out of all three equally, so it is left out.
Change the assumptions and the order changes. That is the point. Run the math with the real terms in each written offer, line by line, before you sign anything.
Red Flags: How to Spot a Bad Cash Offer
Many cash buyers run legitimate businesses. The industry also has bad actors. These signs call for a pause. Our guide on whether "we buy houses" companies are legit goes through more of them.
- Pressure to sign immediately. A legitimate buyer lets you compare offers and have an attorney review the contract, and a buyer who says the offer expires in an hour is working on your nerves, not your numbers. We encourage both.
- No proof of funds. A cash buyer should be able to show a bank statement, a line of credit or a letter from a lender that proves it can close. Ask early.
- Unexplained assignment language. Ask whether the buyer will close on the house itself or pass the contract to someone else. A straight answer matters more than the wording.
- Very little earnest money, or a very long inspection period. Both can leave you tied up while the buyer shops your contract. Ask what is at risk on the buyer's side if the deal fails.
- A sudden drop after the walkthrough. Some adjustment can be fair when the buyer finds something real. A large drop with no explanation is a reason to ask for the math or walk away.
- No verifiable business. No website. No reviews. No title company. Eagle Cash Buyers, LLC is registered in Ohio and rated A+ by the BBB.
- No explanation of the math. If a buyer cannot or will not walk you through how the number was built, the offer is not transparent. Walk away.
How Eagle Cash Buyers Makes and Evaluates Offers
Here is how it works with us, step by step. We would rather you know before you call than find out on the phone.
- Acquisition call. A team member learns your situation, goes through the property's condition and history, and discusses your goals and timeline.
- Field visit. A field agent or mobile notary photographs the property and notarizes documents, and for sellers who cannot travel or who do not use e-signature, the notary comes to you instead of asking you to come to an office.
- Contractor assessment. We send contractors to quote repairs. You never pay for or manage repairs.
- Written offer. Based on comparable sales, repair estimates and our costs. We show you how it was built.
- Title work and closing. Closing runs through a title company or closing attorney. Funds go by wire transfer or cashier's check.
Closing costs are covered by us, except your mortgage payoff, any back taxes or liens, and your share of transfer tax. Those come out of your proceeds. We evaluate properties in 43 states, and we may buy directly or assign the contract. That is disclosed in the agreement before you sign.
We can close in as little as 21 to 42 days, or longer if you need more time. You choose the date. We also encourage you to compare offers, to have your own attorney review the contract before you sign, and to take all the time you need, because a good offer will still be a good offer after a few days of checking it.
When a Cash Offer Makes Sense, and When It Does Not
A cash offer fits when time, condition or circumstances make a traditional listing impractical or expensive. It fits poorly when the home is in great condition, you have the time and the money to put it right, and top price is your priority. Then listing can net more. Our guide on which saves you more money, a cash sale or a traditional sale helps you decide.
- A cash offer tends to fit when: the home needs significant work, you are on a deadline, the property is vacant, or a title problem would complicate a financed sale.
- Listing tends to fit when: the home is move-in ready, you have months to spare, your market favors sellers and you can carry the costs comfortably.
A cash offer is below market value. That is the trade-off for speed and certainty, and it deserves a hard look with real numbers from both paths, not a feeling about what the house is worth.
Frequently Asked Questions
Where can I get an instant cash offer on my house?
You can request offers from iBuyers, direct cash buyers like Eagle Cash Buyers, "we buy houses" companies, franchise brands, offer marketplaces and individual investors. The quickest way to start is to submit your address on a buyer's website or call them. Expect any quick number to be preliminary until the buyer has evaluated the property in person or through a full set of photos and records.
How much do cash offer companies pay for homes?
It varies. Buyer type, condition and market all matter. A cash offer is below what the house might bring on the open market, because the buyer takes on repairs, holding costs and resale, so the useful question is not the price but what you keep. Compare net proceeds.
Are instant cash offers legitimate?
Many are. Some are not. Look for a verifiable business presence, proof of funds, a closing through a title company or attorney, and a willingness to let you compare offers, take your time and consult an attorney of your own before you commit to anything. Eagle Cash Buyers, LLC is registered in Ohio, rated A+ by the BBB and has completed more than 1,000 transactions since 2019.
What is the difference between an iBuyer and a "we buy houses" company?
An iBuyer uses automated valuation, may charge a service fee and buys homes that meet its criteria. A direct "we buy houses" company is usually an investor who buys many properties as they are and prices in the repairs. Details differ. Ask each company to show you its fees and its math in writing.
Do I have to pay fees when I sell to a cash buyer?
It depends on the buyer, so ask for a net sheet that lists every deduction before you agree to a cash sale. With Eagle, there is no agent commission on a direct sale, and we pay closing costs except your mortgage payoff, back taxes or liens, and your share of transfer tax.
Can the offer change after the first quote?
Yes, with most buyers. A preliminary offer rests on limited information, and a buyer may adjust it after the walkthrough, the contractor assessment or the title search turns up something nobody knew about. Ask any buyer what could change the number and whether the limit will be put in writing.
Should I get more than one offer?
Yes. Two or three offers from different types of buyers give you comparison points and a stronger position when you talk numbers. We encourage it.
How fast can I close on a cash offer?
We can close in as little as 21 to 42 days, or longer if you need more time, and you choose the date. Timing depends on title readiness, liens, mortgage payoffs and the closing provider, any one of which can add days. Our look at how fast a cash sale can realistically close explains what affects it.
This article is for general information and is not legal or financial advice. The figures in the example are hypothetical. Terms and closing procedures vary by buyer, by state and by property, so have your own attorney review any contract before you sign.