Yes. You can usually sell your house fast before foreclosure, as long as the closing happens before the foreclosure sale, and a sale that covers the full payoff generally ends the foreclosure. Timing is the risk. Fees and interest keep growing, and a listing or a signed contract doesn't stop the clock by itself, so get a written payoff statement, talk to your servicer and pick the fastest option that covers the payoff.
Rules vary by state and by loan, so confirm your own dates. The CFPB lists HUD-approved housing counselors who offer independent advice, often at little or no cost, and the HOPE Hotline at (888) 995-4673 answers 24 hours a day. We're a cash home buyer, so weigh our view accordingly.
Can You Sell a House in Foreclosure?
Generally, yes. Until the property is sold at the foreclosure sale, you usually still own it and can sell it, even with a notice of default or a lawsuit already filed. If the price covers it, the closing agent pays the lender from the proceeds, so your missed payments, late fees and interest are settled inside the payoff rather than out of your pocket first. If you're a few payments behind and no notice has arrived, you have more room, and our guide to selling when you're behind on mortgage payments covers that stage.
How Much Time Do You Have Before the Foreclosure Sale?
It depends on your state, your loan and your servicer. Under federal rules, a servicer generally can't make the first foreclosure notice or filing until the loan is more than 120 days delinquent, with limited exceptions (12 CFR 1024.41(f), checked October 2026). After that, the process sets the pace. In a judicial foreclosure the lender files a lawsuit and a court oversees the case, which tends to take longer. In a non-judicial foreclosure a trustee sends the notices required by state law and the loan documents, then can move to a sale without a judge.
Time Left by Stage
| Stage | Time left | What is still realistic |
|---|---|---|
| Behind, no notice yet | No first notice or filing until the loan is more than 120 days delinquent, generally (federal rule, checked October 2026) | A listing, a cash sale or a workout |
| Notice of default or lawsuit | Varies widely by state and court | A listing if time allows, a cash sale, a short sale or a workout |
| Sale date scheduled | Whatever remains before the date in your notice | Mostly a cash sale that covers the payoff, or a written postponement or workout |
| After the foreclosure sale | Usually too late for a normal sale | Some states allow a limited redemption period. Ask a local attorney. |
Our guide on how long the foreclosure process takes goes deeper on court and non-court states, and how foreclosure auctions work covers the sale itself.
Will Selling Stop the Foreclosure?
A completed sale generally ends it, if the proceeds cover the full required payoff and reach the lender before the sale date. A listing or a signed contract does not.
A sale may help avoid a foreclosure sale if it closes in time and the proceeds are enough to satisfy the required payoff, or if the lender gives written approval to accept less. We cannot promise to stop or postpone a foreclosure; that depends on the lender or servicer, the foreclosure process in your state, the timing and whether the transaction closes. Contact us as early as possible and bring every notice you have so we can usually tell you whether our expected timeline appears workable. A HUD-approved housing counselor or an attorney licensed in your state can explain your legal options and deadlines. At Eagle, we can help only if there are at least 3 weeks before the auction date and you can send paperwork quickly and help the title company close fast.
Once you sign a contract, ask your servicer in writing whether it would postpone the sale date, and plan as though the date could stand.
Your Four Options for Selling Before Foreclosure
A traditional listing and a cash sale are normal sales, and both need a price that covers the payoff, while a short sale and a deed in lieu of foreclosure need the lender's agreement.
| Listing | Cash sale | Short sale | Deed in lieu | |
|---|---|---|---|---|
| Speed | Usually the slowest | Can be fast. With Eagle, most sales close in 21 to 42 days, or later if you need more time | Slow, since the lender reviews it | Depends on the lender |
| Lender approval needed? | No | No | Yes | Yes |
| Fits when | You have equity and months of time | You have equity and little time | You owe more than the home is worth | You owe more and can't sell |
| Main risk | The buyer's loan falls through | A lower price than an open-market sale | The lender rejects or delays it | The lender declines |
Option 1: Selling on the MLS (Traditional Listing)
A listing puts your house in front of the widest pool of buyers, and it often brings a better price than a cash sale. The catch is time. A financed buyer needs an appraisal and loan approval, and if that financing fails near the end there may be no time left to relist before the sale date. Then there's the agent commission. It's usually between 5% and 6% of the sale price, and it's negotiable and depends on the agent. A listing fits best when the sale date is months away and you can keep paying the mortgage, taxes and insurance while the house is on the market.
Option 2: Selling to a Cash Home Buyer
A cash buyer doesn't need a mortgage. The sale doesn't wait on a lender's approval or an appraisal, and you usually don't fix anything first. Once a sale date is set, that is often the route that still fits the calendar, provided you have equity and the title can be cleared in time.
At Eagle Cash Buyers, the steps are a call about your situation, a property review, title work and a closing with a licensed title or escrow company, or a closing attorney, depending on the state. Most sales close in 21 to 42 days, or later if you need more time. You pick the date. Eagle charges no fees, and you pay no repair costs and no closing costs. Your mortgage payoff, any liens and prorated property taxes are paid from the sale proceeds. On a standard cash offer you also pay the transfer tax, and the purchase agreement states who pays.
The trade is price. A cash offer is usually below what a well-prepared listing might bring, and the offer isn't what you take home: whatever remains after the mortgage, any other liens and your share of the sale costs goes to you. What narrows the gap is what you skip, from the commission to months of carrying costs.
Why Acting Fast Matters: Your Payoff Can Grow
An old statement balance goes stale. Once a lender moves to foreclose, fees and interest keep stacking up, so the number you were quoted weeks ago may not be the number the title company needs.
Real seller story. A homeowner in Indiana who contacted us learned her auction date from a sheriff's sale notice delivered to the house, where her mother was living. The deal had been built around a mortgage payoff of roughly $182,000. The notice put the full payoff demand at about $212,000, roughly $30,000 more, and climbing. She hadn't yet spoken to the mortgage company. When she did, there was no repayment plan on offer, just "Pay in full." Our coordinator didn't improvise on the phone. He told her, "Let me bring this information to my manager to see how we want to play it out, see what can we do in order to help you." Our record doesn't show how her sale ended, so we won't claim it beat the auction.
Ask your servicer in writing for a payoff statement now. Ask again as closing nears. A servicer generally has to send it within seven business days of a written request, but when a loan is in foreclosure it may take a reasonable time instead (12 CFR 1026.36(c)(3), checked October 2026), which is one more reason to ask early.
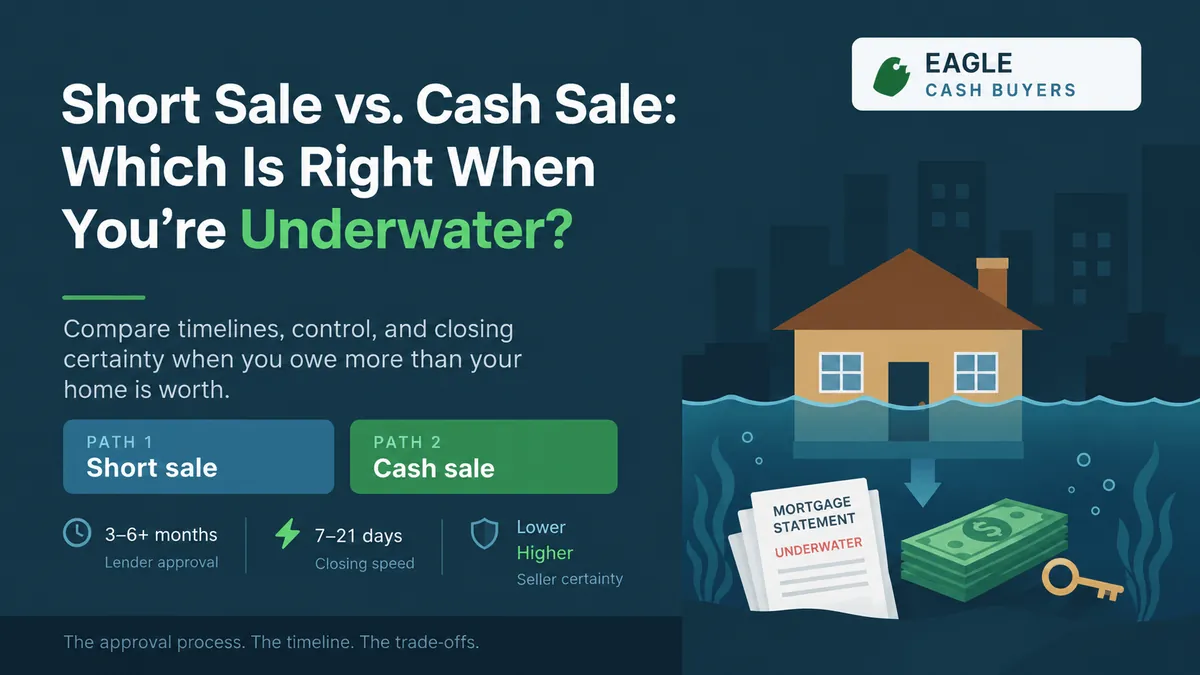
Option 3: Short Sale (When You Owe More Than the Home Is Worth)
In a short sale you sell for less than the loan balance and the lender agrees to accept less. The lender's review is the bottleneck. That makes a short sale a poor fit for a tight calendar, although for some underwater owners it is the route that works, and with a second mortgage, each lienholder usually has to agree too.
Two cautions. In some states a lender may be able to pursue you for the shortfall unless the agreement waives it in writing, so have an attorney check the waiver. Forgiven debt can also be taxable: the exclusion for forgiven debt on a main home covered debt discharged before January 1, 2026, or under a written arrangement entered into before then (IRS Topic 431, checked October 2026). Ask a tax professional. Our guide on short sale versus cash sale covers underwater sellers.
Option 4: Deed in Lieu of Foreclosure
You hand the title to the lender, and the lender agrees to cancel some or all of the debt. It avoids the auction. But it needs the lender's agreement, it doesn't automatically clear second mortgages or other liens, and whether you could still owe a shortfall afterward depends on your state and on the wording of the agreement. Our comparison of a deed in lieu and selling for cash covers the credit side.
The Real Numbers: What You Walk Away With
Here is an illustrative example with round numbers, not what any buyer typically pays.
Illustrative Example: $250,000 Home, $190,000 Payoff
| Line item (illustrative) | Listing | Cash sale |
|---|---|---|
| Sale price or offer | $250,000 | $210,000 |
| Agent commission (assumed 5.5%) | -$13,750 | $0 |
| Seller closing costs (assumed 2%) | -$5,000 | $0 with Eagle |
| Repairs (assumed) | -$8,000 | $0 |
| Carrying costs (assumed) | -$7,500 (3 months) | -$1,500 (3 weeks) |
| Payoff with arrears and fees | -$190,000 | -$190,000 |
| Net to seller | $25,750 | $18,500 |
Here the listing nets about $7,250 more. It also takes longer and is more likely to miss the sale date, and with only weeks left, a closed sale that leaves $18,500 can beat a listing that doesn't close. The example holds the payoff level, though three more months would add interest and fees, and leaves out back taxes, other liens and transfer tax, which reduce what you receive in either column.
The Credit Impact: Foreclosure vs. Selling Before
The CFPB says a credit reporting company can generally report most negative information for seven years. A sale that pays the loan in full means no completed foreclosure goes on your report, though late payments already reported can stay. A short sale or a deed in lieu can also hurt your credit, so ask the lender how it would report the account. See short sale vs. foreclosure for the comparison.
How to Sell Your House Fast Before Foreclosure: A Step-by-Step Plan
- Get your payoff and your dates. Ask your servicer in writing for a payoff statement and whether a notice, lawsuit or sale date exists.
- Find out what the house is worth. Get an agent's market analysis and a cash offer.
- Work out your equity. Value minus the payoff and sale costs. If you owe more than the value, look at a short sale or a deed in lieu.
- Match the method to the calendar. Months of runway may favor a listing, while a short window usually points to a cash sale.
- Tell your servicer you plan to sell. Get any postponement or approval in writing. Have an attorney review the contract.
- Close and confirm. Then get written confirmation that the loan is satisfied.
Other Ways to Avoid Foreclosure If You Want to Keep the House
Selling isn't the only way out. The CFPB lists options a servicer might offer, among them refinancing, a loan modification, a repayment plan and forbearance. Some notices also give a deadline to reinstate by paying the past-due amount, and our guide on how to delay foreclosure covers these routes.
Frequently Asked Questions
Can I sell my house in pre-foreclosure to a cash buyer?
Often, yes. It works if the price covers the payoff and any other liens and there's enough time before the sale date. At Eagle, we can help only if there are at least 3 weeks before the auction date and you can send paperwork quickly and help the title company close fast. Whether we can make an offer depends on the area, the value and whether the numbers work.
What should you not do before selling a house in foreclosure?
Don't sign over your deed, or control of your home, to a company that only promises to sell it later. The North Carolina Department of Justice warns that some "we buy homes" companies convince owners to sign over control, then lease the property to a new tenant while the owner is still responsible for the mortgage. Don't pay upfront for help either. The CFPB says you don't have to pay anyone to help you avoid foreclosure.
What happens to my equity if my house is foreclosed on?
It depends on the auction. If the price is higher than what you owe plus costs, state law decides whether any surplus goes to you. Auction prices are often lower than a normal sale, so selling first gives you more control over the price and what remains for you.
Where a Cash Sale With Eagle Fits
Eagle Cash Buyers, LLC is registered in Ohio and rated A+ by the BBB, with 1,000+ transactions since 2019. We evaluate properties in 43 states. Foreclosure pressure came up in about one in ten of the seller files Eagle documented in 2026, and these are sellers who contacted a cash buyer, not a representative sample of home sellers. Eagle is not a lender. Our sell before foreclosure page explains how we work with tight dates. A sale may help you avoid a foreclosure sale if it closes in time. If there is enough time, we work to close before the sale date or explain your options. We can't promise to stop or postpone a foreclosure.
Eagle Cash Buyers is not a law firm, title company or tax advisor. This information is general and is not legal, title or tax advice. Laws, procedures and transaction costs vary by state and locality, and the purchase agreement and closing documents control each transaction.