Most sellers weighing a cash offer vs listing with an agent start in the same place. They get a cash offer, hold it up next to the price a neighbor's house listed for, and the cash number looks low. So they assume listing is the obvious winner and move on.
That comparison is the wrong one. When you weigh the two, the number that matters is what you keep after every cost is paid on each path. A listing price is a projection. A written cash offer is a figure you can plan around. Different things.
We buy houses for cash, and we have completed more than 1,000 transactions since 2019. We could tell you cash is always better. It is not, and saying so would cost us your trust. This guide walks through the costs on both paths, shows the method with clearly hypothetical numbers, and says plainly when listing is the smarter financial move, which it often is for a home in good shape owned by someone with both time and money to spare.
The Comparison Most Sellers Get Wrong
The most common mistake is setting a cash offer next to a listing price. Those two numbers describe different things.
- Listing price is what you and an agent decide to ask. It is a marketing number. Buyers often negotiate it down.
- Sale price is what a buyer finally agrees to pay, after negotiation, inspection and appraisal.
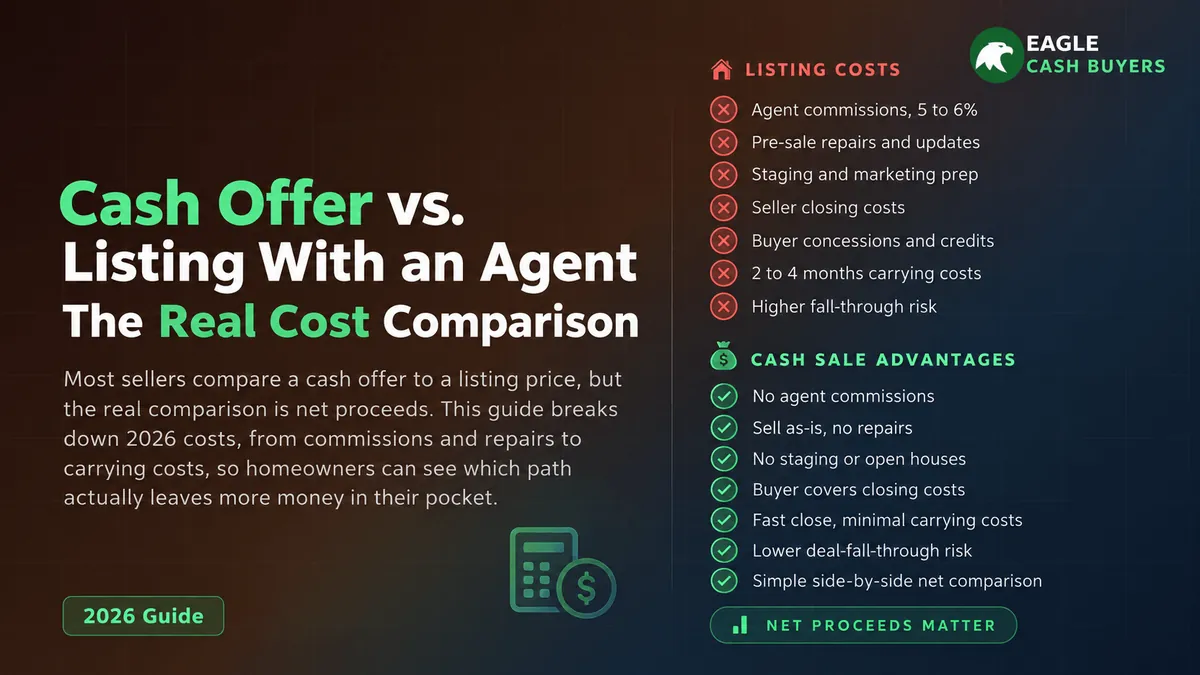
- Net proceeds is what reaches your account after commissions, closing costs, repairs, concessions and the months of carrying costs are subtracted.
A cash offer skips most of that middle stretch. It is closer to a net number on the day you receive it. When you compare it with a listing price, you are comparing a near-final figure with a best-case starting figure. The gap often narrows once the listing path's costs come out. Sometimes it closes. Sometimes listing still wins.
One sentence to keep in mind: the comparison is net proceeds against net proceeds, not sale price against cash offer.
Cash Sale vs. Traditional Sale at a Glance
Here is the short version of a cash sale vs traditional sale. The sections below fill in each row.
| Factor | Cash sale | Traditional sale |
| Price | Below market value | At, near or above market value, depending on condition and demand |
| Time to close | With Eagle, as little as 21 to 42 days, or longer if you need it | Finding a buyer comes first, then their financing, appraisal and inspection |
| Agent commission | None on a direct sale | Negotiated, paid from the sale price |
| Repairs and prep | None from you | Often expected up front, plus credits after inspection |
| Risk of falling through | No lender to wait on | Depends on the buyer's financing and appraisal |
Every Cost of Listing With a Real Estate Agent
A traditional sale usually carries several categories of cost between the sale price and your check. None of them are hidden fees or bad faith. They are the normal economics of a listing, just rarely added up in one place. The size of each one depends on your home, your market and the agent you hire, so get real quotes before you rely on any figure.
Agent commissions
This is usually the largest single cost. It is a percentage of the sale price, and it is negotiable. After the 2024 National Association of Realtors settlement, offers of buyer-agent compensation can no longer be published on the MLS, and buyers work under written agreements with their own agents. Commission is still fully negotiable, as the association's own summary of what the settlement changed explains. Ask every agent you interview exactly what you would owe and to whom.
Pre-sale repairs and updates
Buyers who use a mortgage tend to expect something close to move-in ready. The lender's appraiser can weigh in too. Getting a home list-ready can cost anywhere from a modest amount to a very large one, depending on condition, and then the inspection often opens a second round of negotiation over whatever the first round missed.
Financing adds another gate. FHA-insured loans, for example, come with minimum property requirements, which HUD describes in the glossary to its Handbook 4000.1 as general requirements that an insured home be safe, sound and secure. A home that misses them can lose a buyer who would otherwise have bought. Get contractor quotes before you decide how much to fix.
Staging, photography and prep
Some agents include parts of this in their service and some charge for it. Ask. Then add the decluttering, the deep cleaning and the curb-appeal work you will do yourself, whether in time or in money, before the first showing ever happens.
Seller-side closing costs
Separate from commission, sellers typically pay some title, settlement, recording and transfer charges. Who pays what depends on the state and on the contract. The CFPB explains this in its guide to who pays which closing fees. Your closing or title company can give you an estimate for your property.
Buyer concessions and inspection credits
Sellers forget this one. It lands after they think the price is set, when a buyer may ask you to cover part of their closing costs or when inspection findings turn into repair credits that nobody mentioned during the first showing. The CFPB notes that buyers can negotiate a credit from the seller, and that the seller will usually ask for a higher price in return to cover that credit. Either way, the number you agreed to can move.
Carrying costs while you wait
Every month the home is listed and moving toward closing, you usually keep paying the mortgage, property taxes, insurance, utilities and upkeep. If the home is paid off, the mortgage line disappears and the rest remain. Add your own monthly total. Then multiply by the number of months your agent expects, and ask the agent how long comparable homes in your neighborhood have actually taken to sell, since a pricing guess made at the kitchen table is rarely as reliable as recent local results.
Price reductions and days on market
A home that draws no offers often needs a price cut. Sometimes it needs a second one. Buyers can read a cut as a sign that something is wrong, which may invite lower offers, and a house that finally sells after two reductions can net less than an early cash offer would have, so ask your agent how many comparable homes nearby needed a reduction before they sold.
The risk that a financed deal falls apart
A sale that depends on a buyer's mortgage can stall or collapse at the appraisal, the inspection or the lender's final approval. When that happens, you restart the clock, keep paying carrying costs and sometimes lower the price. A cash sale has no lender in the middle. That removes one risk. Other things can still slow a closing, such as a title problem nobody spotted until the title company ran its search, so no buyer should promise you a perfect result.
Every Cost of Accepting a Cash Offer
The cost structure on a cash sale is simpler, and the trade-off is a lower price. A cash buyer takes on the repairs, the risk and the holding costs you would otherwise carry. Not every cash buyer works the same way. This is how a direct sale with Eagle Cash Buyers works.
- Agent commissions: none on a direct sale. There is no listing agent and no buyer's agent paid out of your side.
- Repairs: none from you. We buy many properties as they are, and the offer already reflects the condition we find, including the cost of the work that a contractor tells us the house needs before anyone could buy it with a mortgage.
- Staging and showings: none. No photography. No open houses. No keeping the house spotless for strangers.
- Closing costs: we pay them, with three exceptions. Your mortgage payoff, any back taxes or liens, and your share of transfer tax come out of your proceeds at the table.
- Carrying costs: shorter. We can close in as little as 21 to 42 days. If you need longer, say so, because you pick the date.
- Concessions: the written offer is the number. Any buyer works from the condition they actually find, so the offer can change if the property differs from what was described.
Whether we can make an offer at all depends on the property, the title and our buying criteria. We may buy the house directly or assign the contract to another buyer. That is disclosed in the agreement before you sign.
The trade-off is real. A cash offer comes in below what the house might bring on the open market. How far below depends on the condition of the home and on your local market, and you should expect a meaningful difference rather than a rounding error. You give up price. In return you get speed, certainty, and freedom from fixing, staging or showing the house.
Cash Offer vs. Listing With an Agent: Two Hypothetical Examples
The honest comparison is the check you deposit, not the price on the contract. The two examples below are hypothetical. We chose round numbers to show the method. They are not typical costs, not what any buyer will pay and not a quote for your home.
Both assume a mortgage payoff that comes out of either path equally, so it is left out. They also assume $2,000 a month in carrying costs.
Example A: a move-in-ready home worth about $300,000
| Line item (hypothetical) | Listing with an agent | Cash offer |
| Sale price or offer | $300,000 | $260,000 |
| Agent commissions (assumed 5%) | ($15,000) | $0 |
| Seller closing costs | ($6,000) | $0 |
| Prep and staging | ($3,000) | $0 |
| Buyer credits after inspection | ($3,000) | $0 |
| Carrying costs | ($6,000), 3 months | ($2,000), 1 month |
| Net proceeds | $267,000 | $258,000 |
In this example, listing nets about $9,000 more. A $40,000 gap in headline price shrank to $9,000 in net proceeds. That is still real money. For a seller with a clean house, months to spare and the cash to cover the prep, it favors listing, while a seller on a deadline may decide the smaller gap is worth giving up for a firm closing date.
Example B: a home that needs major work
This is the case most cash-versus-listing articles skip, and it is where the math can flip.
| Line item (hypothetical) | Listing with an agent | Cash offer |
| Sale price or offer | $270,000 | $225,000 |
| Agent commissions (assumed 5%) | ($13,500) | $0 |
| Repairs needed to list | ($15,000) | $0 |
| Seller closing costs | ($5,400) | $0 |
| Buyer credits after inspection | ($8,000) | $0 |
| Carrying costs | ($8,000), 4 months | ($2,000), 1 month |
| Net proceeds | $220,100 | $223,000 |
Here the cash path nets about $2,900 more, and it gets there months sooner. When a home needs work, the repair bill, the longer time on market and the credits can eat the listing advantage. Change any input and the answer moves. Shrink the repair bill and listing pulls ahead again. If your kitchen and baths are dated, read our take on selling an outdated house before you spend money on updates you may never recover.
Treat both tables as a template. Fill in your own numbers from real quotes. Then see who wins.
How a Cash Buyer Calculates the Offer
A fair cash offer is not a guess. Many cash buyers work from a formula like the one below, and knowing it helps you judge whether a specific offer is reasonable.
After-Repair Value - Repairs - Buyer's Costs - Margin = Offer
- After-Repair Value (ARV) is what the home should sell for once fixed up, based on recent comparable sales nearby.
- Repairs are the cost of getting there.
- Buyer's costs cover holding the property, closing and reselling.
- Margin is the buyer's profit. It has to exist, or the buyer cannot stay in business long enough to close your deal and the next seller's deal after it.
If a buyer will not show you how the number was built, treat that as a warning sign. Our guide on how cash home buyers calculate their offer goes through each piece, and our advice on negotiating with a cash home buyer covers what to do with the math once you have it.
When Listing With an Agent Is the Better Move
Listing usually wins when the home is in good shape and you have both the time and the money to see the sale through, including the prep before the first showing, the months of carrying costs while you wait, and the credits a buyer may ask for after the inspection. You need both. Time without cash leaves you stuck. Cash without time leaves you rushing.
- The home is move-in ready or recently updated. Buyers using a mortgage may pay more for a home that needs nothing, and that premium can offset part of the cost of selling.
- You have no hard deadline. Time helps.
- Your market favors sellers. Several offers change the math.
- You can carry the home without strain. If several months of mortgage, taxes and upkeep are not a hardship, the listing path often comes out ahead.
- The home has features that command a premium. Waterfront, historic, custom-built or high-end homes may draw buyers who pay more than an investor would. Their value is already in the house. It does not depend on renovation potential.
We tell sellers to compare offers, take the time they need and have their own realtor or attorney review any contract. If listing nets you meaningfully more and you can wait, listing may be the better choice.
When a Cash Offer Makes More Sense
A cash offer tends to fit when time, condition or circumstances make the traditional route impractical or risky.
- The home needs significant work. Repairs can erase the listing advantage, as Example B showed.
- You are relocating on a deadline. Two housing costs at once add up fast.
- Your listing has gone stale. After a price cut or two, the net from a traditional sale can fall below what a cash offer would have netted earlier. Decide how much further you are willing to cut, and compare again before you do.
- Foreclosure, divorce or probate is setting the clock. Each month of delay can add payments, penalties or stress that a higher price may not cover. Our guide to selling before foreclosure covers the pre-foreclosure side. Deadlines and procedures vary by state, so confirm yours with a local attorney or a HUD-approved housing counselor.
- The property is inherited. Distance, paperwork and upkeep all pile up. Our guide on how to sell an inherited house covers the paperwork side.
- The home is vacant. Taxes and insurance keep coming due, the house keeps aging without anyone in it, and every month of waiting for a financed buyer adds to a bill that you are paying for a property you no longer use.
- There is a title or deed problem. Paperwork issues can complicate a financed sale. Our guide on how cash buyers handle title insurance explains what to expect.
- You owe back taxes or are behind on payments. Selling can be one way to resolve them. See selling your house to pay off debt for when it does and does not make sense.
Price is rarely the whole story. Timing and certainty often decide it. A seller who must be out by a set date, or who cannot afford another month of a second mortgage, is solving a different problem from a seller hunting for the last dollar.
The Cost of Waiting: Carrying Costs
Carrying costs are the most underestimated expense in a traditional sale. You keep paying to own the home until the day it closes. They never appear on the settlement statement, which is exactly why sellers leave them out of their math.
Build your own line. Add your monthly mortgage, property tax, insurance, utilities and upkeep. Multiply by the months you expect between listing and closing. Then add a cushion for a deal that falls through and restarts.
Every month on the market adds to what the sale costs you, even though no line on the settlement statement shows it.
Timing has a second price. If you need the sale money for the down payment on your next home, a delayed closing can mean bridge financing, temporary housing or losing the purchase you wanted, and money in hand within weeks is not worth the same as money in hand after several months when the next purchase has a date on it.
Then there is the cost that has no dollar sign. Keeping a house show-ready for months means disrupted routines, strangers in your living space and the low-grade stress of not knowing when it ends. For some sellers, that is reason enough.
How to Run the Comparison for Your Own Home
Get real numbers for both paths. Put them side by side. The exercise is worth doing even if you end up listing, because it tells you what a listing has to achieve to beat the alternative.
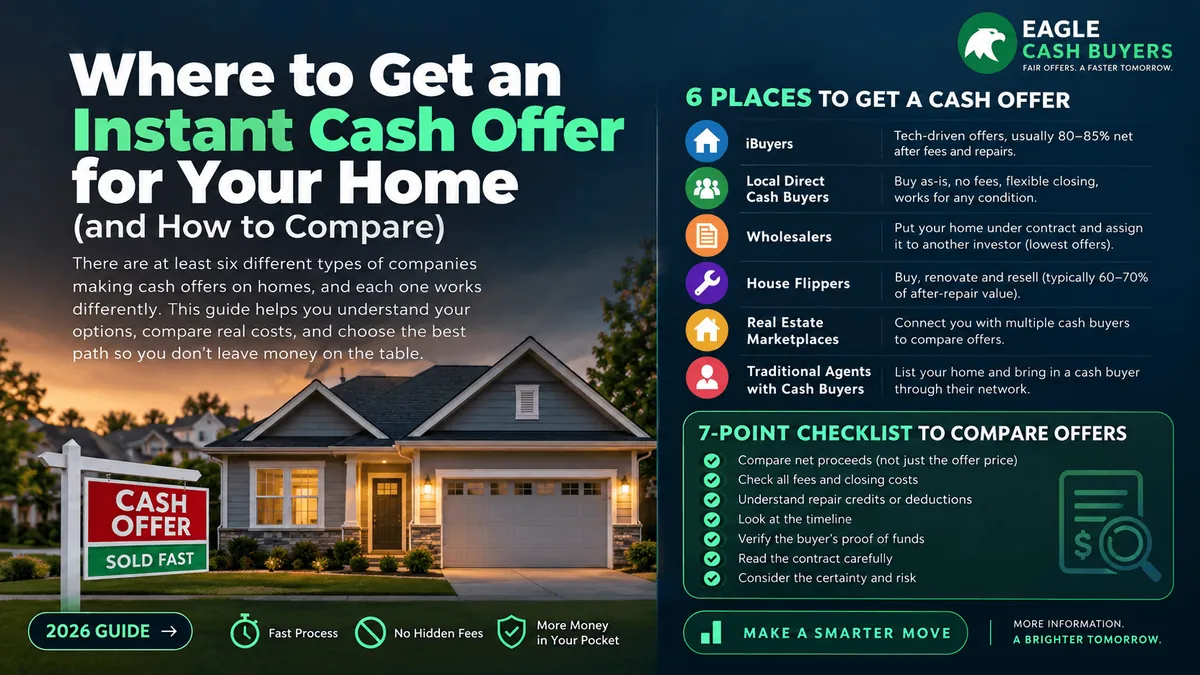
- Get a cash offer in writing. A no-obligation written offer gives you a baseline. Our guide on where to get a cash offer and how to compare them shows how to line up more than one.
- Ask two or three local agents for a net-proceeds estimate. Do not accept a list price alone. A good agent will walk you through each cost line without being asked twice, and one who will not is telling you something.
- Build the side-by-side. For each path, write the price, commissions, repairs, closing costs, carrying costs and likely concessions.
- Compare net to net. Then weigh what money does not capture: time, certainty, hassle and privacy.
- Check the fit. Run your situation through the four questions below.
Liens, unpaid taxes and deed issues can surface on either path. They must be cleared before closing. Raise them early with whoever is handling your closing, because a surprise found late costs time on any sale and money on most.
Four Questions That Point to the Right Path
The numbers give you the net. These questions tell you how much weight to give it, and you can answer all four in an afternoon with a phone and a calculator, once you have a couple of quotes in hand.
- What would it cost to get the home market-ready? Get rough quotes from one or two contractors, because the larger that number comes back, the more a cash offer deserves a serious look next to a listing that would need all of that work done first.
- What is your real timeline? A firm date points toward cash. Months to spare make listing viable.
- What is your local market doing? Ask an agent how quickly comparable homes are selling and whether they draw more than one offer, since a slow market pushes toward cash and a fast one pushes toward listing.
- What does waiting cost you? Multiply your monthly carrying costs by the months a listing would take. The total narrows the gap. Sometimes it closes it.
How to Protect Yourself on Either Path
A few habits keep you from overpaying or accepting less than you should.
If you take a cash offer
- Verify proof of funds. A legitimate cash buyer can show a bank statement, a line of credit or a lender letter proving it can close.
- Get the costs in writing. The purchase agreement should say what the buyer covers. Ask who the buyer will be on the closing documents, since a buyer may purchase directly or assign the contract.
- Close through a title company or closing attorney. Never skip that step.
If you list with an agent
- Negotiate the terms. Commission is not set by law. Everything in the listing agreement is open to discussion, including how long it runs and what happens if you decide to sell another way before it ends.
- Consider a pre-listing inspection. You learn what a buyer's inspector will find, then handle it on your own terms instead of in a rushed negotiation.
- Set a pull-the-plug date. Decide in advance when you will look at a cash offer if the home has not sold. It guards against the sunk-cost trap, where each extra month feels justified by the months already spent.
Frequently Asked Questions
Is it better to sell your house for cash or list with an agent?
It depends. Listing often nets more for a move-in-ready home when you have the time and the money to put the house right and to carry it while a buyer is found. A cash offer can net close to the same, or more, when the home needs work, when you are on a deadline, or when circumstances make a listing impractical. Compare net proceeds from both paths.
How much less do cash buyers pay than a listing would bring?
A cash offer comes in below what the house might bring on the open market. How far below depends mostly on the home's condition and your local market. The gap in what you actually keep is often smaller than the gap in headline price, because a listing has its own costs. Ask for a written offer and run the comparison for your property.
What closing costs do I pay when I sell to a cash buyer?
With Eagle Cash Buyers, we pay the closing costs, except your mortgage payoff, any back taxes or liens, and your share of transfer tax. Those come out of your proceeds at closing. Not every cash buyer works this way, so ask any buyer to put in writing exactly what they cover.
How long does it take to sell for cash compared with listing?
With a cash sale, we can close in as little as 21 to 42 days. You choose the date. A listing has to find a buyer first and then wait through that buyer's financing, inspection and appraisal, so the honest answer for your home comes from a local agent who can tell you how long comparable homes are taking to sell in your area right now.
Can I get a cash offer and list with an agent at the same time?
You can get a cash offer first and use it as a baseline while you interview agents. Read any listing agreement carefully before you sign it, since it may limit what you can do while it runs. Have your own attorney review it.
Can I sell my house for cash if I am behind on mortgage payments?
It can be possible, depending on the payoff, the title and our buying criteria. The mortgage payoff comes out of the sale proceeds, so the price has to cover it. Foreclosure rules differ by state, so talk to a local attorney or a HUD-approved housing counselor early.
What fees should I watch for with cash home buyers?
Ask every buyer for a net sheet that lists each deduction from your proceeds, closing costs included. That is how you catch hidden costs. Be wary of upfront payments, processing charges and verbal-only offers. The written agreement should state what the buyer pays. Close through a licensed title company or closing attorney, and if anything in the contract is unclear, ask your own attorney before you sign.
Are cash home buyers legitimate?
Many are. Not all. Warning signs include pressure to sign right away, refusing to show you the math behind the offer, no verifiable business presence and no title company or closing attorney. Eagle Cash Buyers, LLC is registered in Ohio and rated A+ by the BBB. Rules and closing procedures vary by state, so have your own attorney review the contract before you sign.
A Last Word
The number on a listing is a hope. The number on a written cash offer is a figure you can plan around. Neither is automatically better. It depends on you. The right choice is the one that leaves more money in your pocket once every cost is counted and fits the life you are actually living.
If your home is in good shape and you have time and money, listing may well net you more. If it needs work or you are on a clock, a cash sale is worth putting real numbers to. Get an offer, get a market analysis and compare net to net.
This article is for general information and is not legal or financial advice. The figures in the examples are hypothetical. Costs, timelines and closing procedures vary by state and by property, so confirm the details for your situation with your own attorney or advisor.