A white two-storey house with dormer windows and dark shutters behind a wide mown lawn, with a black mailbox at the curbside and mature evergreens alongside
Questions? Call us: (833) 330-1625

Sell My House Fast in Iowa: We Buy Houses for Cash, As-Is, Any Condition

Any condition, from the Quad Cities to Siouxland. Tell us the address and we will put a real number in writing, free, with nothing to sign.

Sold as-is, no repairs to fund Free, no-obligation offer No agent commission to pay All 99 Iowa counties

Homeowners in 43 states can request a written cash offer from Eagle. In Iowa that includes homeowners from Des Moines and Cedar Rapids out to Davenport, Sioux City, Dubuque, Ottumwa and Spencer. If a foreclosure petition has been filed against you, read its first page before anything else. Iowa makes the lender print your choice there, in capital letters, and it is a choice with a real deadline.

Question 1 of a few

What is the Iowa address?

We price against sales in your own county, and Dallas County prices nothing like Wapello, so this is where we have to start. The next few questions cover condition, ownership and your timing.

Free, and nothing to sign. If a traditional listing would leave you with more, we will tell you.

Next: condition of the house, who is on the title, and the date you would like to close by.
Google Reviews BBB Accredited
  • A+BBB rating
  • 4.5from 40 Google reviews
  • 1,000+transactions completed
  • 43states we buy in

Oren Sofrin, as quoted inMSNYahoo FinanceGOBankingRatesBiggerPockets

Finding your cash offer...

How to Sell Your House Fast in Iowa for Cash

Send us the address and enough detail about the property to work with. During business hours an initial no-obligation offer is often possible within minutes to a few hours, though plenty of houses need research, photographs or a walkthrough first. Most Eagle transactions close in roughly 21 to 42 days, depending on title readiness, liens, payoffs and the property review. If a foreclosure petition has been filed, send it across, because what is printed on its first page changes what your options actually are. See how our sell my house process works, from your first call to closing.

1

Tell us about the house

The address on this page, or a call to (833) 330-1625. We ask about condition, who is on the title, what is owed and when you want to be out. Not your credit.

2

We underwrite, then put it in writing

Comparable sales in your county, what the repairs will cost us, and the resale risk. The written agreement states the price, the closing target and the contingencies.

3

Property review, title, closing

We inspect the house and open title. Payoffs, liens and ownership get verified. The title agency records the deed and disburses your proceeds.

A small older house with painted shingle siding, a corrugated metal roof and porch canopy, a screen door and rose bushes growing up against the front windows
Roof age, storm damage and whether a property can be insured decide most financed Iowa sales, well ahead of the kitchen.

We Buy Houses Across Iowa

Select a city to learn more

Want to see the number before you decide anything?Tell us the address. The offer is free, there is nothing to sign, and if listing would net you more we can usually say so.
Get My Cash Offer or call (833) 330-1625

Cash Home Buyers Across Des Moines, Cedar Rapids, the Quad Cities and Every Iowa Metro

Iowa is one metropolitan market, a handful of mid-sized cities and a great many county seats, and they do not move together. Des Moines runs on insurance and state government, the Corridor on a university and manufacturing, the Quad Cities trade across the river, Council Bluffs is priced against Omaha, and the small towns move on the farm economy. We operate across all of it.

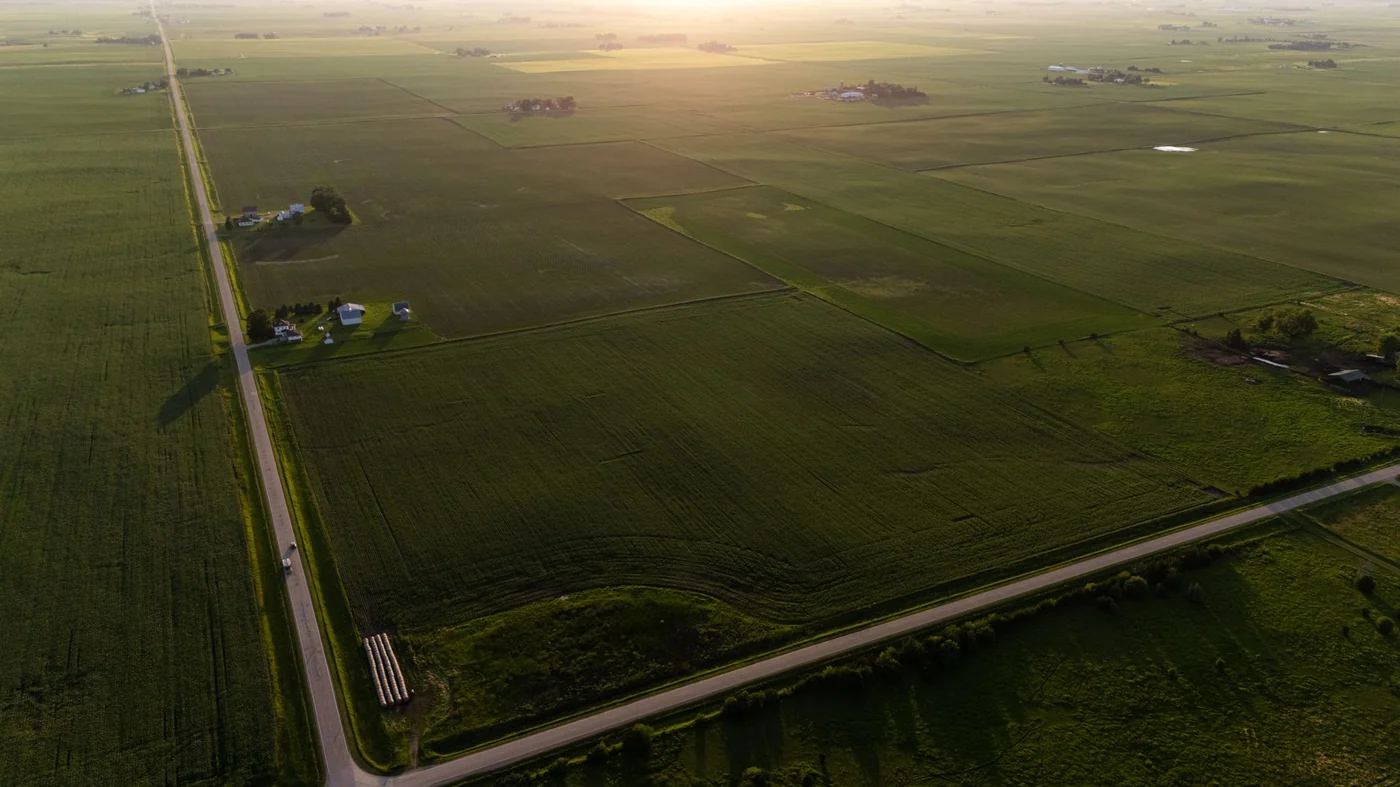
A sunset aerial of flat farmland divided into a grid of square fields by straight gravel roads, with isolated farmsteads and shelter belts scattered across it
Between the metros, most of the state is a section-line grid of farmsteads and county seats, each with its own thin market.

Des Moines

Polk County

The capital and by far the largest market, built on insurance, finance and state government. The most stable employment base in the state and the widest spread of housing ages inside one county.

Sell Your House in Des Moines →

The Des Moines Suburbs

Polk, Dallas and Warren Counties

West Des Moines, Ankeny, Urbandale, Waukee, Johnston, Clive, Altoona, Grimes, Norwalk and Indianola. Where almost all of the recent building has gone, on a buyer pool that works in the city.

Sell Your House in The Des Moines Suburbs →

Cedar Rapids and the Corridor

Linn and Johnson Counties

Cedar Rapids, Marion, Iowa City, Coralville and North Liberty. Manufacturing at one end, the university and the hospitals at the other, a rental market on the academic calendar, and a lot of stock still carrying storm repairs.

Sell Your House in Cedar Rapids and the Corridor →

The Quad Cities

Scott and Muscatine Counties

Davenport, Bettendorf and Muscatine, on the river and trading across it in both directions. Older river-town stock, where flood zone and whether a property can be insured often decide the sale.

Sell Your House in The Quad Cities →

Waterloo and Cedar Falls

Black Hawk and Bremer Counties

Waterloo, Cedar Falls and Waverly. Manufacturing alongside a university, in two adjoining cities whose markets behave quite differently from each other.

Sell Your House in Waterloo and Cedar Falls →

Sioux City and the West

Woodbury and Plymouth Counties

Sioux City and Le Mars, up in the Loess Hills on the western edge. Agriculture and food processing, at some of the lowest prices in the state.

Sell Your House in Sioux City and the West →

Council Bluffs

Pottawattamie County

Across the river from Omaha, and priced against that market rather than against the rest of the state. Older stock down near the river and newer building out on the bluffs.

Sell Your House in Council Bluffs →

Dubuque and the North-East

Dubuque County

Built into the bluffs above the river, with the oldest housing stock in the state and streets steep enough to matter. Age, foundations and access decide sales here well ahead of the kitchen.

Sell Your House in Dubuque and the North-East →

Ames, Boone and Story County

Story and Boone Counties

The university at Ames and the towns around it. A large student rental market with its own calendar, and a research and agribusiness base that keeps it fairly steady for a college town.

Sell Your House in Ames, Boone and Story County →

The River Towns

Clinton, Des Moines and Lee Counties

Clinton, Burlington and Fort Madison. Nineteenth-century river towns with fine older housing at low prices and thin buyer pools, which is often what makes a cash sale the only realistic one.

Sell Your House in The River Towns →

Mason City, Fort Dodge and the North

Cerro Gordo, Webster and Clay Counties

Mason City, Fort Dodge and Spencer. County-seat markets running on agriculture, manufacturing and healthcare, each moving entirely on its own.

Sell Your House in Mason City, Fort Dodge and the North →

The Small County Seats

Marshall, Jasper, Wapello, Mahaska, Marion, Carroll and Buena Vista Counties

Marshalltown, Newton, Ottumwa, Oskaloosa, Pella, Carroll and Storm Lake. Towns of a few thousand to a few tens of thousands, where a single sale can move the local figures.

Sell Your House in The Small County Seats →

Iowa Counties We Cover

From Woodbury and Plymouth on the western edge across to Scott, Clinton and Dubuque on the river, and from Bremer and Cerro Gordo in the north down to Lee and Wapello in the south, our city pages span the state, and we evaluate property anywhere in Iowa. Being inside the footprint is not the same as an offer. Location, property type, condition, marketability, title and our current buying criteria all decide whether we can make one.

Black Hawk County
Boone County
Bremer County
Buena Vista County
Carroll County
Cerro Gordo County
Clay County
Clinton County
Dallas County
Des Moines County
Dubuque County
Jasper County
Johnson County
Lee County
Linn County
Mahaska County
Marion County
Marshall County
Muscatine County
Plymouth County
Polk County
Pottawattamie County
Scott County
Story County
Wapello County
Warren County
Webster County
Woodbury County
Do not see your town on the list?We evaluate property in all 99 Iowa counties, not only the cities with their own page.
Get My Cash Offer or call (833) 330-1625

What a cash sale in Iowa actually costs you

A cash offer comes in below what a prepared house would fetch on the open market. You are trading price for speed, an as-is sale and a much shorter list of things that can go wrong. Whether that trade makes sense depends on the condition of the house and what waiting is costing you.

Below is the honest comparison. Read the last two rows as carefully as the first ones.

 Listing with an agentEagle Cash OfferEagle Retail Max
Typical timelineAbout 39 days on market, then 30 to 45 days to closeRoughly 21 to 42 daysLonger than a cash offer, and driven by the end buyer
Agent commission 5% to 6% of $255,934About $12,800 to $15,400 from your proceedsNone from youNone from you. Eagle covers applicable commissions
Closing costs other than transfer taxSeller pays a shareEagle pays themEagle pays them
Transfer tax at 0.16% above the first $500, mortgage payoff, prorated property taxes, recording feesYoursYours, except the recording fees, which Eagle paysEagle pays the transfer tax and the recording fees. The rest is yours
Repairs before saleOptional, but selling as-is usually narrows the buyer pool and the priceNone. Sold as-isNone from you. Eagle covers approved repair and concession costs
ShowingsOngoing, on the buyer's scheduleProperty review and inspection onlyRequired. Normally scheduled 24 hours ahead when occupied
Financing riskA buyer’s loan can fail on underwriting, appraisal or property conditionNo lender on our sideDepends on the end buyer
Likely proceedsHighest, if the house is market ready and you can waitLowest of the threeBetween the two

Commission figure uses the Iowa median sale price of $255,934 as of August 2026 and a typical 5% to 6% rate (it varies by market), for illustration only. Your numbers will differ. Iowa's transfer tax is 80 cents per $500, or part of $500, of the amount above the first $500, which is 0.16%, or roughly $409 at that median price, worked out here from the statutory rate. The seller is liable by default, though like any closing item it is negotiable in the purchase contract, and the exemptions include deeds between spouses or between parent and child without actual consideration. We did not establish how a deed in lieu of foreclosure is treated, so ask your closing agent. Which structure fits depends on the property, your equity and your timing, and the written agreement controls in every case.

Two things decide this, and they are worth separating: whether you have the time to wait a sale out, and whether you have the money to put the house right before it goes on. Where you have both, list it with a good local agent. We would rather say that up front than spend three weeks getting to the same answer. Where one of them is missing, a cash sale is not the consolation prize. It is often the better outcome and sometimes the only one that closes: a house that needs work you cannot fund, a tangled title, a real deadline, or a situation that takes the listing route off the table.

Dubuque and Storm Lake are different markets entirely.We price against sales in your own county, because a statewide median tells you almost nothing about your street.
Get My Cash Offer or call (833) 330-1625

Iowa Seller Situations: Foreclosure, Storm Damage, Probate, Rentals and Divorce

These are the situations we run into most often in Iowa, and what we can and cannot do about each one.

⚠ Served With an Iowa Foreclosure PetitionRead the first page before you do anything else

If a petition has been filed against you, the most important thing in it is on page one, and it may be printed in capital letters.

A lender electing foreclosure without redemption has to say so there, and has to tell you that the sale happens promptly after judgment unless you file a written demand to delay the sale. Filing one buys you months in the house. But where the petition does not waive a deficiency and the property is your residence and a one- or two-family dwelling, not filing protects you from a deficiency judgment and filing it does not.

That is a real decision with a real deadline: the demand has to go in before entry of judgment. The laws section on this page sets out the detail. We are not going to tell you which way to go. Take the petition to an Iowa attorney and ask them, because the answer turns on how much is owed against what the house is worth.

Send us the petition and any judgment. We will tell you honestly whether a sale before the auction is realistic. We cannot promise to stop a foreclosure or protect your credit, because that depends on your lender, the timing and whether a closing actually happens.

Related guide: How to Sell Your House Fast Before Foreclosure

🌪 Storm, Flood and Derecho DamageAnd the section that keeps it counting as your home

Iowa property gets hit. Derechos have taken roofs off whole neighborhoods, the rivers flood, and hail and tornadoes do the rest. Two things follow from that, and both matter to a sale.

The first is practical: roof age, hail history and whether a property can be insured at a price a buyer will accept decide more Iowa sales than anything inside the house. We buy properties with storm damage, open claims and roofs at the end of their life regularly, and we would far rather know at the start than find it at inspection. If a claim is in progress, tell us, because sometimes it is worth finishing first.

The second is legal and almost nobody knows it. Nearly every protection in an Iowa foreclosure turns on the house being your residence, and Iowa keeps it counting as your residence where you left because of a natural disaster, injury to the property not willfully caused by you, or national guard or federal active duty. The laws section on this page sets out the detail. If you moved out after a storm or a flood, or because you were deployed, say so early and in writing.

Related guide: How to Sell a House As Is

🏠 Inherited Property and ProbateOld farmhouses, and the family transfer

An estate cannot convey clear title until the personal representative has authority to sell, and Iowa probate runs on its own timetable. We work with executors regularly and the usual constraint is the court rather than the house.

If the plan is to move the property within the family rather than sell it, Iowa exempts deeds between husband and wife, or parent and child, without actual consideration from the transfer tax, and adds that a cancellation of debt secured by the property and no greater than its fair market value is not actual consideration for that purpose. Worth knowing before anyone signs a deed assuming the tax will be charged.

Much of what we see in inherited Iowa property is genuinely old: knob-and-tube wiring, a stone or brick foundation that has moved, a cistern or an old well, buried fuel tanks, and out on the acreages a septic system and a private well rather than a rural water connection. Bring what you know and we will be straight about what it means for the number.

Related guide: How to Sell an Inherited House

🔑 Rentals, Tenants and Small MultifamilyWe buy occupied property

A tenant in place is not an obstacle and you do not need to remove anyone before talking to us. Existing leases generally survive a sale, and we would rather take the property with its tenancies intact than ask you to create a vacancy.

Two Iowa points if a rental of yours is behind. The right to cure applies to a homestead, and not to property other than a one- or two-family dwelling that is your residence. And a property that is not your residence carries a shorter redemption period than one that is. A landlord in Iowa is therefore in a different position from an owner-occupier facing the same lender, and the laws section on this page sets out the detail.

Iowa City, Ames, Cedar Falls and Waterloo all run student tenancies on an academic calendar, and the older stock in Des Moines, Dubuque, Davenport and Sioux City carries a lot of small multifamily. Bring the leases, the rent roll, the deposits and any arrears or disputes. Security deposits are the item most often overlooked and they have to be accounted for at closing.

Related guide: Selling a Rental Property With Tenants

💵 Divorce and Co-Owned PropertyBoth signatures, or we cannot proceed

A house is often the last asset to be settled and the one that keeps two people tied together after everything else is done.

The practical constraint is authority: both owners on title normally have to agree to a sale, and we cannot proceed on one signature where two are required. Where attorneys are involved we are happy to work through them, and where a decree already specifies what happens to the house, send it across and we will work to what it says.

If the property is in foreclosure while the two of you are still working things out, remember that the demand to delay the sale has to be filed before entry of judgment and does not wait for a decree. That is not a decision to leave to whoever opens the post.

We are not a party to the dispute and will not take a side in it. Our job is to give both of you the same number in writing so you can decide what to do with it.

Related guide: Selling a House During Divorce

Asked in Iowa

Is it a good time to sell a house in Iowa?

By the figures, a good one, and we can usually say so even though it argues against us.

In Redfin's August 2026 figures, the Iowa median sale price was $255,934, up 4.5% on the year. The number of homes sold was up 1.4%, and the median time to sell fell by two days to 39. Homes for sale rose 3.3% and newly listed homes rose 3.3%, with months of supply unchanged at three. The share going above list fell 1.5 points to 19.7%, the share taking a price cut was flat at 20.0%, and the sale-to-list ratio was essentially unchanged at 97.6%. Price up, volume up and time on market down together is a healthy market by any reading.

If you have the time to wait and the money to put the house right first, list it. We fit the cases that market does not fix: hail or derecho damage a lender wants dealt with before it will finance, a foreclosure petition already served, or a rental you would rather sell with the tenants in place.

Been served with a foreclosure petition?Read the first page before anything else. If it carries a notice in capital letters, you have a decision to make and a deadline to make it by.
Get My Cash Offer or call (833) 330-1625

What Actually Happens on the First Call

People put off calling a company like ours because they do not know what they are walking into. Here is a real call, with the details that could identify anyone removed. We are not saying it was an Iowa seller, because we do not attach cases to states they did not come from.

From our own call records

A man called about his wife’s house. She had sent the inquiry, he was out running errands, and he thought he would get things started. Our acquisition manager noticed the inquiry was in her name, asked whether she was unable to take part, and when the answer was no, she simply asked me to call, he stopped the conversation there. Not for a signature. We talk to the owner. They booked a three-way call for once he was home, around his drive rather than our calendar.

What that first call is for, in his words: it is pretty basic, really more for us to find out about the property and the condition it is in. No offer on the spot, no paperwork, no pressure.

Anonymised from a recorded call. No names, no location, no property details, because the record holds none and we do not invent them. This account ends where the record ends, with a follow-up scheduled.

Iowa Real Estate Laws Every Seller Should Know

Iowa forecloses through the court, and it makes the lender print your choice on the first page of the petition in capital letters. What that choice costs you runs the opposite way from what most people expect. Here is what generally applies before you sell, in plain language.

Before Any State Clock Starts: the Federal 120-Day Rule

Every state timeline on this page sits behind a federal one, and it is the single most useful thing to know if you have missed payments. Under Regulation X, 12 CFR 1024.41(f)(1), a mortgage servicer generally “shall not make the first notice or filing” required for a judicial or non-judicial foreclosure unless the borrower's mortgage loan obligation is more than 120 days delinquent.

That is roughly four months of missed payments before the state process is even allowed to begin. It is why a state sequence that looks alarmingly short on paper is usually longer in practice than the statute alone suggests.

The exceptions, because they are real. The rule does not apply where the foreclosure is based on a violation of a due-on-sale clause, or where the servicer is joining the action of a superior or subordinate lienholder. Small servicers are not exempt from this particular prohibition. Loan types and servicing arrangements vary, and some loans are outside Regulation X altogether.

So treat 120 days as the general floor rather than a guarantee, and work from the dates on your own paperwork. If a notice has arrived and you do not believe you are past that point, that is a question worth putting to a HUD-approved housing counselor or an attorney before you do anything else.

The Choice Is Printed On The First Page, In Capital Letters

Iowa forecloses through the court. But a lender may elect foreclosure without redemption under Iowa Code 654.20, and when it does the statute forces it to tell you so on the first page of the petition, in capital letters the same size as the rest. Most people put that document in a drawer. It contains a decision.

The required notice says the sale will happen promptly after entry of judgment unless you file with the court a written demand to delay the sale. If you file one, the sale is delayed until six months from entry of judgment, or three months if the petition includes a waiver of deficiency judgment, where the property is your residence and is a one-family or two-family dwelling, and until two months otherwise. It also tells you, in the same capitals, that you will have no right of redemption after the sale and that the purchaser is entitled to immediate possession.

Now the part that makes it a genuine decision. Where the petition does not include a waiver of deficiency, section 654.20(2) requires a second paragraph, and section 654.26 states the same rule operatively. If the property is your residence and is a one-family or two-family dwelling, then:

  • If you do not file the demand, a deficiency judgment shall not be entered against you.
  • If you do file the demand, a deficiency judgment may be entered if the sale proceeds fall short.

So the demand buys you months in the house and can cost you the protection from being chased for the shortfall. We are not going to tell you which way to go, because the answer depends entirely on how much is owed against what the house is worth and on whether you have anywhere else to be. What we will tell you is that this is a real choice with a real deadline, that section 654.21 requires the demand to be filed before entry of judgment, and that it is worth an hour of an Iowa attorney's time before you decide.

Two exits that survive it. Section 654.21 also lets you and the lender file a stipulation afterwards that the sale may go ahead promptly and that the mortgagee waives the deficiency, so the trade can be renegotiated. And at any time before judgment, paying the amount claimed in the petition means the action shall be dismissed; after judgment but before the sale, paying the judgment means it is satisfied of record and the sale shall not be held.

The federal rule above generally sits in front of this whole sequence. Free HUD-approved housing counseling is available before you commit to anything, including to us.

Official sources: Iowa Code ch. 654, sections 654.20, 654.21 and 654.26

If They Did Not Elect It, You May Have A Year, And Possession

Where the lender has not elected foreclosure without redemption, chapter 628 applies, and Iowa's default is a generous one.

Section 628.3: the debtor may redeem “at any time within one year from the day of sale, and will, in the meantime, be entitled to the possession thereof”, with the first six months exclusive to the debtor. And property redeemed by the debtor is then “free and clear from any liability for any unpaid portion of the judgment”.

A full year, living there, is a materially different position from the one described in the card above. It is worth finding out which one you are in, and the answer is on the front page of the petition.

The period can be shorter, and there is a pattern to when. Every rung down the ladder is paid for by the lender giving up the deficiency:

  • Section 628.26: on land under ten acres, the mortgage itself may reduce the period to six months, or to three months where the property is not used for an agricultural purpose as the Code defines it, provided in all cases that the mortgagee waives any right to a deficiency judgment. You keep possession.
  • Section 628.27: again on land under ten acres, where the mortgage so provides and the court finds the tract abandoned, and again only if the mortgagee waives the deficiency, the period drops to sixty days. The same section adds that “entry of appearance by pleading or docket entry by or on behalf of the mortgagor shall be a presumption that the property is not abandoned”. Turning up in your own case matters.
  • Section 628.28: where the property is not agricultural and is not your residence, or is your residence but not a one- or two-family dwelling, the period is 180 days, or 90 days where a deficiency judgment has been waived. And where a one- or two-family dwelling was your residence at foreclosure but the court finds it has ceased to be, the period is cut to thirty days from the court's order, or sixty if there is a junior creditor.

Read those together and the point is hard to miss. In Iowa, moving out is what puts you on the shortest rungs. We are not telling you to stay somewhere you cannot afford to stay, and staying does not stop a foreclosure. We are telling you what the sections key on, so the decision is yours to make knowingly.

Official source: Iowa Code ch. 628, sections 628.3, 628.26, 628.27 and 628.28

Thirty Days To Cure, A Line For Storm Damage, And What A Sale Costs

Before any of that, there is a notice. Under section 654.2D a creditor who believes in good faith that a borrower on a homestead is in default must give a notice of right to cure, and the borrower has thirty days from the date it is given to cure. Until those thirty days are up the creditor may not accelerate the balance, take possession other than by voluntary surrender, or otherwise enforce the obligation. The figure is the arrears, not the payoff: all unpaid installments due at the time of tender, “without acceleration”, or the amount stated in the notice, whichever is less. Curing “restores to the borrower the borrower's rights” under the mortgage.

Three limits, and you should hear all three from us. There is no right to cure where the creditor already gave a proper notice for a prior default within the previous 365 days. The section does not apply at all where the creditor is an individual, or where the property is not a one- or two-family dwelling that is your residence, so a seller-financed or private mortgage sits outside it. And a defective notice is not a defence unless you prove you were substantially prejudiced by the defect.

A short section that matters if your house is empty for a reason. Nearly every protection above turns on the property being your residence. Section 654.1A says that for the purposes of sections 628.28, 654.2D, 654.20, 654.21 and 654.26, property is deemed the residence of and occupied by the mortgagor where occupation has ceased because of the effects of a natural disaster, injury to the property not willfully caused by the mortgagor, or the mortgagor's national guard duty or federal active duty. In a state that gets derechos, river floods and tornadoes, that is not a theoretical protection.

On a shortfall and a surplus. Section 654.6 makes a deficiency the general position, by general execution against the mortgagor “unless the parties have stipulated otherwise”, which is exactly what all those waivers above are. Section 654.7 says that an overplus after satisfying the mortgage and costs goes to the mortgagor, “and if there is no other lien upon the property”, which is the statute's own qualifier and the reason a surplus is rarely as simple as it sounds.

What a sale costs you. Chapter 428A charges a real estate transfer tax of eighty cents for each $500, or fraction of $500, of the amount above the first $500, which works out at 0.16%, so roughly $409 at the August 2026 statewide median and $319 on a $200,000 sale. Section 428A.3 makes the person who grants, assigns, transfers or conveys the property liable, which by default is you, though like any closing item it is negotiable in the purchase contract. Two details worth having: the price is presumed to include any personal property unless its dollar value is stated on the deed, in which case it is deducted; and section 428A.2 exempts, among others, deeds between husband and wife, or parent and child, without actual consideration, deeds correcting an earlier one, and partition deeds where no consideration passes. We did not establish how a deed in lieu of foreclosure is treated, so ask your closing agent rather than assuming.

Official sources: Iowa Code ch. 654 and ch. 428A

General information, not advice. This section describes Iowa practice in general terms and was checked in September 2026 against the Iowa Code 2026 as published by the Iowa Legislature. Laws, timelines and local procedures change, and how any of it applies to your property depends on facts we have not seen. It is not legal, tax or financial advice, and it is no substitute for talking to an Iowa attorney, accountant or HUD-approved housing counselor about your own situation.
House standing empty after a storm or a flood?Iowa has a section that can keep it counting as your residence. Tell us what happened and when you left.
Get My Cash Offer or call (833) 330-1625

Iowa Housing Market Snapshot

Iowa is a strong market for sellers right now, and we can usually say so even though it argues against selling to us. Figures below are Redfin statewide data for August 2026.

Iowa statewide figures, Redfin, August 2026. Recheck before relying on them.
MeasureLatestSource
Median sale price$255,934Redfin, August 2026
Median days on market39 daysRedfin, August 2026
Year-over-year price change+4.5%Redfin, August 2026
Homes for sale, up 3.3%14,031Redfin, August 2026
Homes selling above list price19.7%Redfin, August 2026
Sale-to-list price ratio97.6%Redfin, August 2026
The front of a small cream bungalow with a green-painted porch, white rails, a flag on a pole by the steps, azaleas in the bed and a motorcycle parked on the path
Iowa prices rose 4.5% in the year to August 2026 while the median time to sell fell by two days, which is a combination we have rarely been able to report.

Price, sales and speed all moving the seller's way

The median sale price was $255,934 in August 2026, up 4.5% on the year, with sales up 1.4% and the median time to sell two days shorter at 39. Two things decide whether listing is better for you: the time to wait a sale out, and the money to put the house right first. Where you have both, list it, and in this market we can usually say so plainly, because at 97.6% of list price a good Iowa house is being paid for properly. The exception is a house with a foreclosure petition already filed against it. There, what is printed on the first page matters more than any market figure, and the laws section on this page explains why.

Selling Just Over the Iowa Line?

Plenty of Iowa sellers own a second property, an inherited house or a former rental across a border, and the rules change the moment you cross it. Iowa prints the homeowner's choice on the face of the petition and ties the redemption period to what the lender gave up. Its neighbors do not work that way. We evaluate property in all of these.

Illinois

Across the river from the Quad Cities, and the two banks are one housing market in everything but law. Illinois runs foreclosures through the court as well, but its redemption arrangements are not built on the trade this page describes. Do not carry any of it over the bridge with you. See Rock Island or Moline or Peoria.

Missouri

South, and the nearest large markets to the bottom tier of counties. Missouri uses a trustee rather than a court, which makes the whole sequence faster and puts the deadline that matters before the sale rather than after it. See Kansas City or St. Joseph or Columbia.

Minnesota

North, and a common tie for families in the top tier of counties. A different system again, and none of the timings on this page should be assumed to apply up there. See Rochester or Austin or Minneapolis.

Wisconsin

North-east across from Dubuque. Wisconsin uses the court too, but the deadline that matters there has to be claimed before judgment in a way that works quite differently from the demand described here. See La Crosse or Madison or Milwaukee.

What Sellers Say About Working With Us

Kadeshia WhitleyRated 5 out of 5
Kelly and the remainder of the team worked as swiftly as possible to assist me in my property. Would recommend.
Carmen GoodmanRated 5 out of 5
I received the utmost help from Ms. Kelly with my home. She really went out of her way to help me. I can say she is truly an angel. There are still honest and trustworthy people on this earth.

4.5 from 40 reviews on Google · read them all

2019

Founded, and headquartered in Columbus, Ohio.

1,000+

Transactions since 2019 across a 43-state footprint. Coverage does not mean every property qualifies.

A+

Eagle Cash Buyers, LLC is BBB Accredited with an A+ rating. Accreditation is not an endorsement. See the profile.

Ready to See What an Iowa Cash Sale Looks Like?

Sold as-is. No agent commission. Most transactions close in roughly 21 to 42 days.

Get My Free Cash Offer

Or call us: (833) 330-1625

Iowa Home Selling Questions, Answered Straight

Real answers about Iowa law, timelines and how the process actually works here.

How fast can you close on an Iowa home?

Most Eagle transactions close in roughly 21 to 42 days. The timeline depends on title readiness, liens, payoffs and the property review. If a foreclosure petition has been filed against you, send it to us, because what is printed on its first page changes what your options actually are.

What is the fastest I can realistically sell?

To a buyer who does not need a mortgage, does not need the house repaired first and can work to a title company's timetable, it is usually 21 to 42 days. What it is not is same-day or 24 hours, and we would be wary of anyone promising that. Title work, existing liens, mortgage payoffs and the property review all take real time and none of them can be skipped. With a listed Iowa home taking a median of 39 days just to go under contract, three to six weeks to a completed sale is quick but not miraculous.

There is a notice in capital letters on my foreclosure petition. What do I do?

It means the lender has elected foreclosure without redemption: the sale happens promptly after judgment unless you file a written demand to delay it, and that demand has to go in before entry of judgment. Where the petition does not waive a deficiency and the property is your residence and a one- or two-family dwelling, filing the demand buys you months in the house but can cost you the protection from being chased for the shortfall, while not filing keeps it. We are not going to tell you which way to go, because it depends on how much is owed against what the house is worth. The laws section on this page has the detail, and an Iowa attorney should see the petition.

Do I get a redemption period after an Iowa foreclosure sale?

It depends on what the lender elected. If it elected foreclosure without redemption, you have no right to redeem after the sale and the purchaser is entitled to immediate possession. If it did not, you may generally redeem within one year from the day of sale and stay in possession meanwhile, though the period can be shorter where the lender waived the deficiency or the house has stopped being your residence. The laws section on this page has the detail.

How long do I have to cure an Iowa default?

Thirty days from the date the creditor gives you the notice of right to cure, and the amount is the arrears rather than the payoff. The right applies to a homestead and has limits, which the laws section on this page sets out, so ask an Iowa attorney whether it covers your own loan.

What transfer tax do I pay when I sell in Iowa?

Iowa charges eighty cents for each $500, or fractional part of $500, of the amount above the first $500, with no tax where there is no consideration or where the instrument is recorded as corrective of title and says so. That works out at 0.16%, so about $409 at the August 2026 statewide median of $255,934 and about $319 on a $200,000 sale, both figures worked out here from the statutory rate rather than looked up. The law makes the person who grants, assigns, transfers or conveys the property liable, which by default is you, though like any closing item it is negotiable in the purchase contract. Two details worth having: consideration includes any lien on the property that the buyer assumes, and the price is presumed to include any personal property in the sale unless its dollar value is stated on the deed, in which case it is deducted. The exemptions include a list that includes deeds between husband and wife or parent and child without actual consideration, deeds that correct an earlier one, and partition deeds where nothing is paid. We did not establish how a deed in lieu of foreclosure is treated, so ask your closing agent rather than assuming.

Do you have to pay taxes on the profit when you sell a house in Iowa?

Two different things get mixed up in that question and they are worth separating. The transfer tax above is charged on the price and is not about profit at all. Tax on the gain is a federal question first, and the federal exclusion for a main home is subject to conditions on ownership, on how long it was your principal residence, and on how recently you last used it, so whether it applies to you depends on facts we have not seen. Iowa also has its own income tax treatment which we have not read anything on and are not going to characterise. We are not accountants and we do not compute anybody's tax. Ask a tax professional about your own situation before you assume either that you owe something or that you do not.

Should I just list it instead?

In Iowa right now, often yes. It turns on two things: whether you have the time to wait a sale out, and whether you have the money to put the house right before it goes on. Where both are true, list it, and in a market selling in a median of 39 days at 97.6% of list we can usually tell you so plainly. Where one of those two conditions is missing, a cash sale becomes the better answer and often the only one that closes: a foreclosure petition already filed with a decision to make on its first page, storm damage or a roof no insurer will look at, an inherited house in probate, an acreage with well or septic problems, or a title issue that has to be cleared before anyone can buy at any price.

Oren Sofrin

Reviewed by Oren Sofrin, Founder and CEO of Eagle Cash Buyers

Oren has more than ten years in real estate, and he and the Eagle team have completed over 1,000 transactions. His market commentary has been quoted by MSN, Yahoo Finance, GOBankingRates and BiggerPockets. Last reviewed October 2026.

See How We Calculate Your Iowa Cash Offer

Get My Cash Offer →