
You’ve just been named executor of an estate, and among the bank accounts, paperwork, and family conversations is a house that needs to be sold. Maybe you knew this was coming. Maybe you didn’t. According to a 2024 Trust & Will study, nearly 46% of people named as executors didn’t even know they’d been chosen.
Either way, you’re now responsible for selling someone else’s property through a legal process you may never have dealt with before. And every month that house sits unsold, it’s costing the estate money.
This guide walks through the probate home sale process step by step: what documents you need, how the court is involved, what selling path makes financial sense, and how to protect yourself as executor along the way.
Can You Sell a House During Probate?
Yes. An executor or administrator can sell a house during probate once the court grants legal authority, typically through Letters Testamentary (if there’s a will) or Letters of Administration (if there’s no will). You don’t have to wait for the entire probate process to finish before selling.
Probate takes 9 to 24 months on average nationally, according to National Center for State Courts data. Selling the property during that period is common and often necessary: to pay estate debts, distribute proceeds to heirs, or stop the carrying costs on a property the estate can’t afford to maintain.
The critical starting point: nothing legal happens until the court issues your Letters. You can’t sign a listing agreement, accept an offer, or close a sale without them. That document is the executor’s legal foundation.
If the property was held in a living trust, had a transfer-on-death deed, or was owned as joint tenants with right of survivorship, it may pass outside probate entirely. For that process, our guide to selling an inherited house covers the full picture.
What You Need Before You Can Sell (Executor Checklist)
Before you can legally sell a probate property, you need court appointment, the right documents, and in some states, specific approvals. Here’s what to gather before you contact a buyer or list the property.
- Letters Testamentary or Letters of Administration (from the probate court; your legal authority to act)
- Certified death certificates (2 to 3 copies minimum; title companies and banks will each need one)
- The original will (if one exists)
- An EIN for the estate (Employer Identification Number; required to open an estate bank account and file taxes; apply free at IRS.gov)
- Professional appraisal establishing fair market value as of the date of death
- Property insurance transferred or newly issued in the estate’s name (the homeowner’s policy may lapse after death)
- Will review for sale authority (does the will grant independent administration, or is supervised administration required?)
- Title search to identify liens, unpaid taxes, or encumbrances
- Beneficiary and heir notification per your state’s requirements
- Court approval to sell (if supervised administration applies in your state)
This list isn’t exhaustive for every state, and probate rules vary. A probate attorney in your jurisdiction can confirm what’s needed before you proceed.
The 7 Steps to Selling a House in Probate
The probate home sale follows a predictable sequence. The timeline varies by state and administration type, but the core steps are the same.
Step 1: File the Will and Open Probate
File the will (if one exists) and a petition with the probate court in the county where the deceased lived. Most states require filing within 1 to 4 months of death. The court schedules a hearing, typically 4 to 6 weeks out, to review the petition and appoint the executor or administrator.
If there’s no will, the court appoints an administrator, usually the closest surviving relative who petitions for the role.
Step 2: Get Your Letters Testamentary
The court issues Letters Testamentary (with a will) or Letters of Administration (without one). This document is your legal authority to act on behalf of the estate. Keep several certified copies. Title companies, banks, and buyers will all need one, and some courts limit how long a certified copy stays valid.
Step 3: Secure the Property and Stop the Bleeding
Change the locks. Transfer or obtain property insurance in the estate’s name. Keep utilities on (especially in winter to prevent pipe damage). Start paying property taxes and any mortgage from estate funds.
This is where carrying costs begin. A vacant inherited home can cost $1,500 to $3,000 or more per month in mortgage payments, taxes, insurance, utilities, and basic maintenance. Every month the property sits unsold is money leaving the estate.
Step 4: Get the Property Appraised
Order a professional appraisal to establish the property’s fair market value as of the date of death. This typically costs $300 to $600 for a standard residential property.
The appraisal serves three purposes: it establishes the stepped-up tax basis for the heirs (more on that below), it sets the benchmark for fiduciary pricing, and it gives you a defensible number if anyone later questions the sale price.
Step 5: Decide How to Sell
You generally have three options: list traditionally with an agent, sell to a cash buyer, or auction. The right choice depends on the property’s condition, your timeline, the estate’s carrying costs, and whether the heirs are aligned.
A traditional listing may yield the highest gross price but takes months and accumulates commissions, carrying costs, and repair expenses. A cash sale closes faster and costs less but produces a lower sale price. We compare these paths in detail below.
Step 6: Follow Your State’s Notice and Approval Requirements
Under independent administration (where the will grants full authority or the court approves it), you typically notify beneficiaries of the proposed sale and allow a notice period of 15 to 30 days. If no objections are filed, you can proceed to closing.
Under supervised administration, you must petition the court to approve the sale. The court may require a hearing. This adds 30 to 90 days to the timeline at each approval step.
Some states require court confirmation even under independent administration if the sale price falls significantly below appraised value. Always confirm requirements with your probate attorney.
Step 7: Close the Sale and Distribute Proceeds
The title company handles closing, just like any home sale. The executor signs in their capacity as executor, not as an individual. Proceeds go into the estate bank account. From there, pay estate debts (mortgage, liens, taxes, probate costs) and distribute what remains to beneficiaries per the will or intestacy laws. File final tax returns and close the estate with the court.
For more on how the title process works in a cash sale, that guide covers the seller’s side.
Independent vs. Supervised Administration: Why It Matters for the Sale
The single biggest variable in selling a probate house is whether the estate operates under independent or supervised administration. This one distinction can add months to the timeline or cut them.
| Factor | Independent Administration | Supervised Administration |
|---|---|---|
| Court involvement | Minimal after appointment | Active throughout; court approves major decisions |
| Sale authority | Executor can sell after beneficiary notice period | Executor must petition court for permission to sell |
| Timeline impact | Adds 15 to 30 days (notice period) | Adds 30 to 90+ days per court approval step |
| How you get it | Will grants it, or heirs consent, or court approves petition | Default in some states; required if will is silent or heirs object |
| Best for | Straightforward estates with cooperating heirs | Contested estates, unclear wills, disputes among heirs |
If the will explicitly grants the executor “full power of sale” or “independent administration,” the process is faster. If the will is silent, or there’s no will, many states default to supervised administration, and the executor must get court approval before accepting an offer.
Texas, Arizona, and California (through the Independent Administration of Estates Act) are generally considered among the most executor-friendly states. But even in those states, the specific rules depend on how the estate was opened and what the will says. Consult a probate attorney in your state.
The Carrying Cost Problem Nobody Talks About
A vacant inherited property doesn’t just sit there. It costs the estate money every month it isn’t sold.
Monthly Carrying Costs on a $250,000 Inherited Home
| Monthly Expense | Estimated Amount |
|---|---|
| Mortgage payment (if applicable) | $1,200 |
| Property taxes | $350 |
| Homeowners/vacant property insurance | $150 |
| Utilities | $150 |
| Lawn care and basic maintenance | $100 |
| Total monthly carrying cost | $1,950 |
At $1,950 per month:
- 6 months (fast probate + cash sale): $11,700
- 12 months (typical probate + traditional listing): $23,400
- 18 months (slow probate or contested sale): $35,100
Every dollar in carrying costs comes directly out of what the heirs receive. This is why the selling method matters as much as the sale price. A cash sale that closes 6 months sooner can save the estate $12,000 or more in carrying costs alone.
Across 42 seller transactions Eagle Cash Buyers documented in 2026, roughly one in four properties were vacant at the time of sale, and about one in five were inherited or estate properties. (These are sellers who contacted a cash buyer, not a representative sample of all home sellers.) In most of those cases, the property had been sitting empty and costing money before the seller decided to move forward.
Selling a Probate House for Cash vs. Listing Traditionally
An executor can sell a probate house to a cash buyer or list it traditionally with an agent. Here’s how the math compares on the same property.
Scenario: $250,000 inherited home, no mortgage, needing moderate updates.
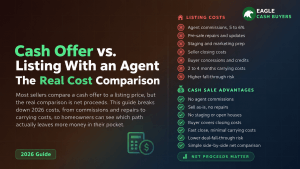
| Factor | Cash Sale | Traditional Listing |
|---|---|---|
| Sale price | $170,000 to $195,000 (as-is) | $230,000 to $260,000 (after prep) |
| Agent commissions | $0 (Eagle covers) | $13,800 to $15,600 (5 to 6%) |
| Closing costs to estate | $0 (Eagle covers) | $5,750 to $7,800 (2.5 to 3%) |
| Repair and prep costs | $0 | $5,000 to $20,000 |
| Carrying costs | $4,000 to $6,000 (2 to 3 months once Letters granted) | $15,000 to $30,000 (8 to 15 months probate + listing) |
| Estimated net to estate | $164,000 to $189,000 | $161,000 to $207,000 |
| Timeline from Letters | 21 to 42 days to close | 3 to 15+ months |
| Heir dispute risk | Lower (speed reduces conflict window) | Higher (longer timeline creates more friction) |
The traditional path can produce higher net proceeds in the best case. But the ranges overlap significantly once you account for carrying costs, commissions, repair expenses, and the risk that a financed deal falls through. For an estate bleeding $2,000 a month in carrying costs, every month saved is money returned to the heirs.
For a deeper dive, our cash offer vs. agent comparison runs the math across more scenarios. And our offer formula breakdown explains how cash buyers arrive at their number.
Your Fiduciary Duty as Executor (And What Can Go Wrong)
As executor, you have a fiduciary duty to act in the best interest of the estate and its beneficiaries. When selling real estate, that means getting fair market value, avoiding self-dealing, and treating all heirs equitably. Breaching that duty can result in personal liability, removal as executor, or surcharge (being forced to repay the estate from your own pocket).
Practical requirements:
- Get a professional appraisal before selling. This establishes fair value and protects you from claims the house sold too cheaply.
- Don’t sell to yourself, a family member, or a business partner at a below-market price without court approval and full transparency to all heirs.
- Document every decision. Why this buyer? Why this price? Why this timeline? A paper trail is your protection.
- Keep estate funds separate. Use a dedicated estate bank account with its own EIN. Never commingle estate money with personal funds.
- Communicate with all beneficiaries throughout the process. Transparency reduces disputes.
A cash sale at a documented fair price, with carrying cost savings, is defensible under fiduciary standards. The key is documentation: the appraisal, the carrying cost math, the rationale for selling quickly. Consult a probate attorney if you have any doubt.
From Our Transactions: Proving Who Has Authority to Sell
Authority questions come up in nearly every estate sale. One transaction Eagle handled involved a father and son in the eastern U.S. who owned a house together. The deed was in the father’s name. The son handled the negotiating.
Eagle’s acquisition manager wouldn’t proceed on the son’s word alone, even though the son was clearly running the conversation. “Legally I still gotta hear your voice,” the manager told the son, asking to speak directly with the father. Both were brought onto the call, and the father gave verbal consent authorizing his son to handle everything on behalf of the property.
Then the contract was walked through line by line with both of them listening: the as-is condition lock, the buyer-pays-closing-costs structure, the property-review rights, and the assignment clause (disclosed up front, not buried in fine print). The son also had a realtor review the contract independently before signing. Eagle encouraged it: “That’s totally fine… any questions, anything, you shoot me a text message.”
It’s a small detail, but it illustrates the authority verification that matters in every estate and probate sale. If the person negotiating isn’t the person on title, a legitimate buyer will stop and verify. If they don’t, that’s a red flag.
(This account is from an Eagle seller file. The record does not confirm whether the sale ultimately closed.)
The Stepped-Up Tax Basis (How It Saves Heirs Money)
When you inherit a property, the IRS “steps up” the tax basis to the property’s fair market value on the date of death. This can eliminate capital gains tax entirely if the property is sold near that value.
Here’s how it works: the original owner bought the house for $80,000 decades ago. If they had sold it for $250,000 while alive, they’d owe capital gains on $170,000 of appreciation. But the heir’s basis is $250,000 (stepped up to the date-of-death value). Sell it at or near $250,000, and the taxable gain is minimal or zero.
This means selling sooner rather than later can be tax-advantageous. The longer you hold the property beyond the date of death, the more it may appreciate above the stepped-up basis, creating a taxable gain that wouldn’t have existed with a quicker sale.
The date-of-death appraisal establishes the stepped-up basis. That’s another reason getting the appraisal early is critical, not just for pricing but for tax protection. For details, see IRS Publication 551 on basis of assets. And consult a tax professional for your specific situation, as state inheritance and estate taxes vary.
What Happens When Heirs Disagree About Selling
Heir disagreements are one of the most common reasons probate sales stall or fail entirely. One heir wants to sell fast. Another wants to keep the house. A third thinks the price should be higher. As executor, your fiduciary duty is to the estate as a whole, not to any individual heir’s preference.
If the will directs the property to be sold, the executor generally has authority to proceed even if not all heirs agree. Heirs can file objections with the court, but they need legal grounds (below-market price, self-dealing, breach of duty), not just personal disagreement.
If there’s no will and heirs disagree, the executor may need to petition the court for authority to sell. The court weighs the estate’s interest: are carrying costs mounting? Are debts going unpaid? Is the property deteriorating?
Practical advice: communicate early and often. Share the appraisal, the carrying cost math, and the rationale for your recommended selling path. Transparency reduces disputes. A partition action (a lawsuit to force the sale of jointly held property) is the nuclear option, and it’s expensive, slow, and destructive to family relationships. Mediation or a frank conversation is almost always better.
A fast cash sale can sometimes be the path of least conflict. It shortens the window for disagreement, eliminates months of decisions about repairs and staging, and puts proceeds in the estate account for distribution.
Frequently Asked Questions
How long does it take to sell a house in probate?
The total timeline depends on your state and how you sell. Getting Letters Testamentary typically takes 4 to 8 weeks. From there, a cash sale can close in 21 to 42 days. A traditional listing adds 3 to 6+ months. In total, most probate home sales take 4 to 18 months from the date of death. Simpler estates close faster; contested ones take longer.
Can an executor sell a house without all beneficiaries approving?
In most cases, yes. If the will grants the executor authority to sell, or if the court orders the sale, the executor can proceed. Heirs can file formal objections with the court, but they need legal grounds. The executor’s fiduciary duty is to the estate as a whole, not to any individual heir’s preference.
Does a house have to go through probate before it can be sold?
Not always. Property held in a living trust, with a transfer-on-death deed, or owned as joint tenants with right of survivorship may pass outside probate. If the property was solely in the deceased person’s name with no such designation, probate is usually required before a legal sale can close.
What is the difference between Letters Testamentary and Letters of Administration?
Letters Testamentary are issued when the deceased left a will naming an executor. Letters of Administration are issued when there’s no will and the court appoints an administrator. Both documents grant legal authority to act on behalf of the estate, including selling real estate.
Do you have to pay capital gains tax when selling an inherited house?
Usually little or none if you sell near the date-of-death value. Inherited property receives a stepped-up tax basis equal to its fair market value on the date of death. Sell at or near that value and the taxable gain is minimal. Hold the property and sell later at a higher price, and you may owe capital gains on the appreciation above the stepped-up basis.
Can you sell a probate house to a cash buyer?
Yes. Executors can sell probate properties to cash buyers as long as they have the legal authority (Letters Testamentary or Administration) and follow their state’s notice and approval requirements. Cash sales can close faster, which reduces carrying costs. The sale must still meet fiduciary standards for fair pricing.
How much does probate cost?
Probate costs typically run 3 to 8% of the gross estate value. Court filing fees range from $50 to $400 by state. Attorney fees vary from flat fees ($1,500 to $5,000 for simple estates) to percentage-based statutory fees. Executor compensation, appraisals, and accounting add more. All costs are paid from the estate.
What happens if the executor doesn’t sell the house?
If the will directs a sale, the executor has a duty to carry it out. If the estate has debts that must be paid from sale proceeds, failing to sell can result in removal as executor. Even without a mandate, an executor who allows a property to deteriorate or accumulate unnecessary carrying costs may face personal liability for the losses.
Your Next Step
If you’re an executor with a probate property to sell, the fastest way to understand your options is to see a real number. Request a no-obligation cash offer from Eagle Cash Buyers to find out what the property is worth as-is. Hold that number next to the appraisal, add the carrying costs for a traditional listing timeline, and compare.
Eagle handles estate properties across 44 states. No repairs, no commissions, no cleaning. The only deductions are the estate’s own mortgage payoff and any liens on the property.
Call (833) 330-1625 anytime, 24/7. Or start online in minutes.