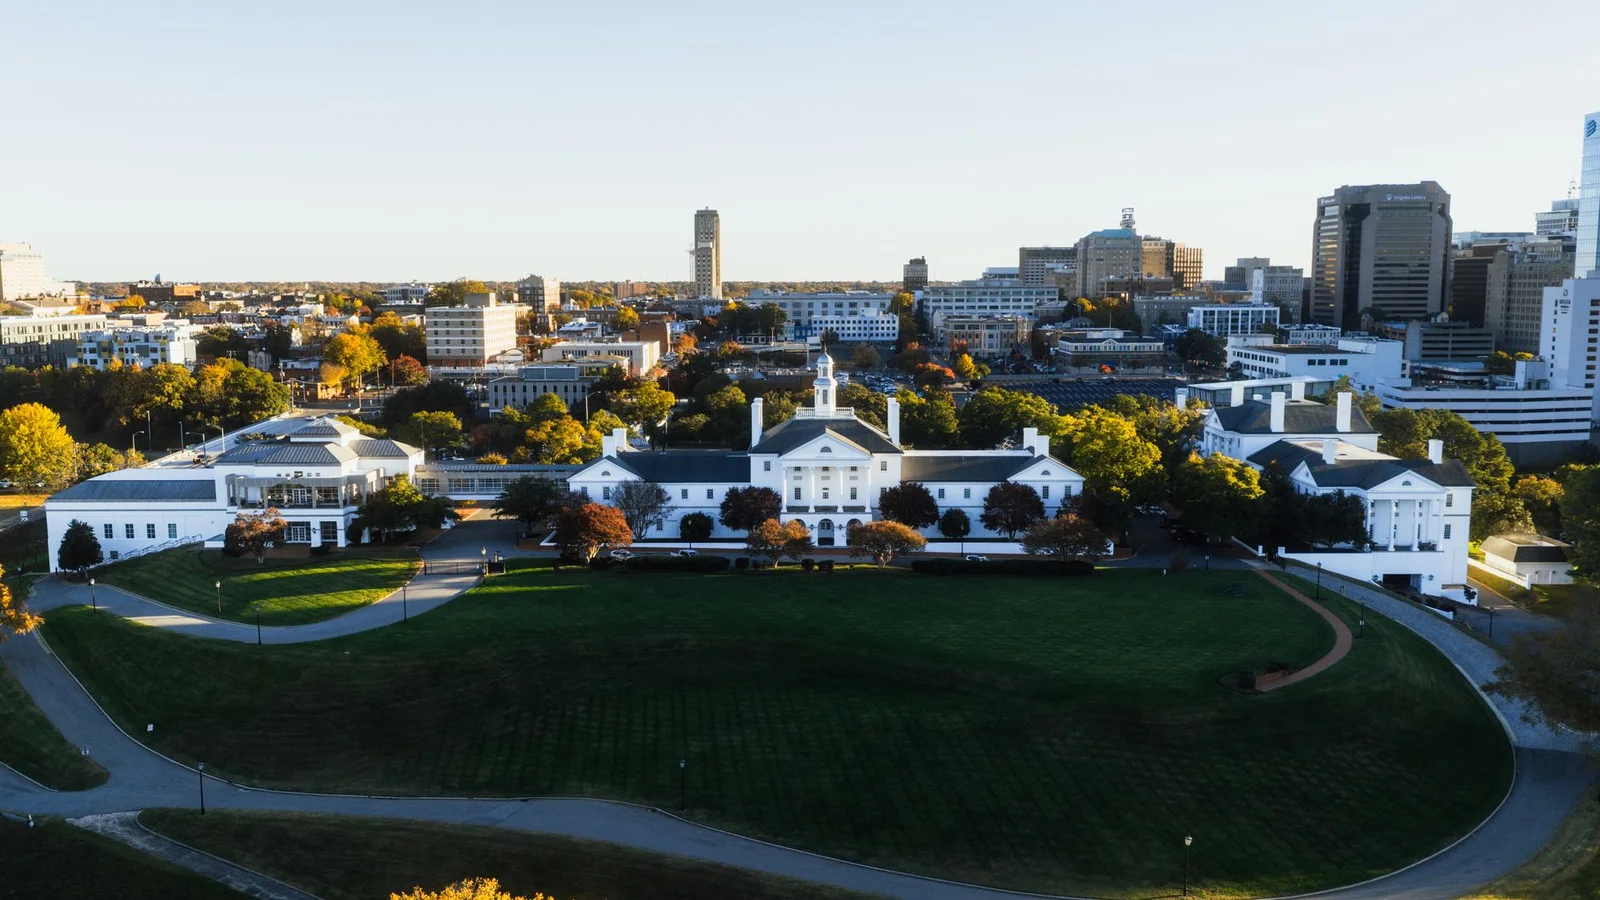
Aerial view of downtown Richmond, Virginia, with autumn foliage and the state capitol
Questions? Call us: (833) 330-1625

Sell My House Fast in Virginia: We Buy Houses for Cash, As-Is, Any Condition

Any condition, from Hampton Roads to the Blue Ridge. Tell us the address and we will put a real number in writing, free, with nothing to sign.

Sold as-is, no repairs to fund Free, no-obligation offer No agent commission to pay Every Virginia county and city

Homeowners in 43 states can request a written cash offer from Eagle. In Virginia that includes homeowners from Virginia Beach, Norfolk and Chesapeake up through Richmond, Fredericksburg and Northern Virginia, and west to Roanoke and the valley. You may have read that Virginia gives a homeowner two weeks' notice before a trustee's sale. For an owner-occupied home that is wrong, and the real figure is far better. We will walk through it with you before anything else.

Question 1 of a few

What is the Virginia address?

We price against sales in your own county or city, and Arlington prices nothing like Danville, so this is where we have to start. The next few questions cover condition, ownership and your timing.

Free, and nothing to sign. If a traditional listing would leave you with more, we will tell you.

Next: condition of the house, who is on the title, and the date you would like to close by.
Google Reviews BBB Accredited
  • A+BBB rating
  • 4.5from 40 Google reviews
  • 1,000+transactions completed
  • 43states we buy in

Oren Sofrin, as quoted inMSNYahoo FinanceGOBankingRatesBiggerPockets

Finding your cash offer...

What a cash sale in Virginia actually costs you

A cash offer comes in below what a prepared house would fetch on the open market. You are trading price for speed, an as-is sale and a much shorter list of things that can go wrong. Whether that trade makes sense depends on the condition of the house and what waiting is costing you.

Below is the honest comparison. Read the last two rows as carefully as the first ones.

 Listing with an agentEagle Cash OfferEagle Retail Max
Typical timelineAbout 38 days on market, then 30 to 45 days to closeRoughly 21 to 42 daysLonger than a cash offer, and driven by the end buyer
Agent commission 5% to 6% of $448,034About $22,400 to $26,900 from your proceedsNone from youNone from you. Eagle covers applicable commissions
Closing costs other than transfer taxSeller pays a shareEagle pays themEagle pays them
Mortgage payoff, prorated property taxes, grantor's taxYoursYoursEagle pays the grantor’s tax. The rest is yours
Repairs before saleOptional, but selling as-is usually narrows the buyer pool and the priceNone. Sold as-isNone from you. Eagle covers approved repair and concession costs
ShowingsOngoing, on the buyer's scheduleProperty review and inspection onlyRequired. Normally scheduled 24 hours ahead when occupied
Financing riskA buyer’s loan can fail on underwriting, appraisal or property conditionNo lender on our sideDepends on the end buyer
Likely proceedsHighest, if the house is market ready and you can waitLowest of the threeBetween the two

Commission figure uses the Virginia median sale price of $448,034 as of August 2026 and a typical 5% to 6% rate (it varies by market), for illustration only. Your numbers will differ. Virginia's state grantor's tax is 50 cents per $500 of consideration, about $1.00 per $1,000 or roughly 0.1%. The statute puts it on the grantor but expressly allows the parties to agree that the grantee pays some or all of it. Some regions add their own grantor's tax on top and we are not quoting those figures here. Which structure fits depends on the property, your equity and your timing, and the written agreement controls in every case.

Two things decide this, and they are worth separating: whether you have the time to wait a sale out, and whether you have the money to put the house right before it goes on. Where you have both, list it with a good local agent. We would rather say that up front than spend three weeks getting to the same answer. Where one of them is missing, a cash sale is not the consolation prize. It is often the better outcome and sometimes the only one that closes: a house that needs work you cannot fund, a tangled title, a real deadline, or a situation that takes the listing route off the table.

How to Sell Your House Fast in Virginia for Cash

Send us the address and enough detail about the property to work with. During business hours an initial no-obligation offer is often possible within minutes to a few hours, though plenty of houses need research, photographs or a walkthrough first. If you accept, the transaction closes through a settlement agent, which is ordinary Virginia practice and does not require an attorney. Most Eagle transactions close in roughly 21 to 42 days, depending on title readiness, liens, payoffs, the grantor's tax and the property review. See how our sell my house process works, from your first call to closing.

1

Tell us about the house

The address on this page, or a call to (833) 330-1625. We ask about condition, who is on the title, what is owed and when you want to be out. Not your credit.

2

We underwrite, then put it in writing

Comparable sales in your county, what the repairs will cost us, and the resale risk. The written agreement states the price, the closing target and the contingencies.

3

Property review, title, closing

We inspect the house and open title. Payoffs, liens and ownership get verified. The title agency records the deed and disburses your proceeds.

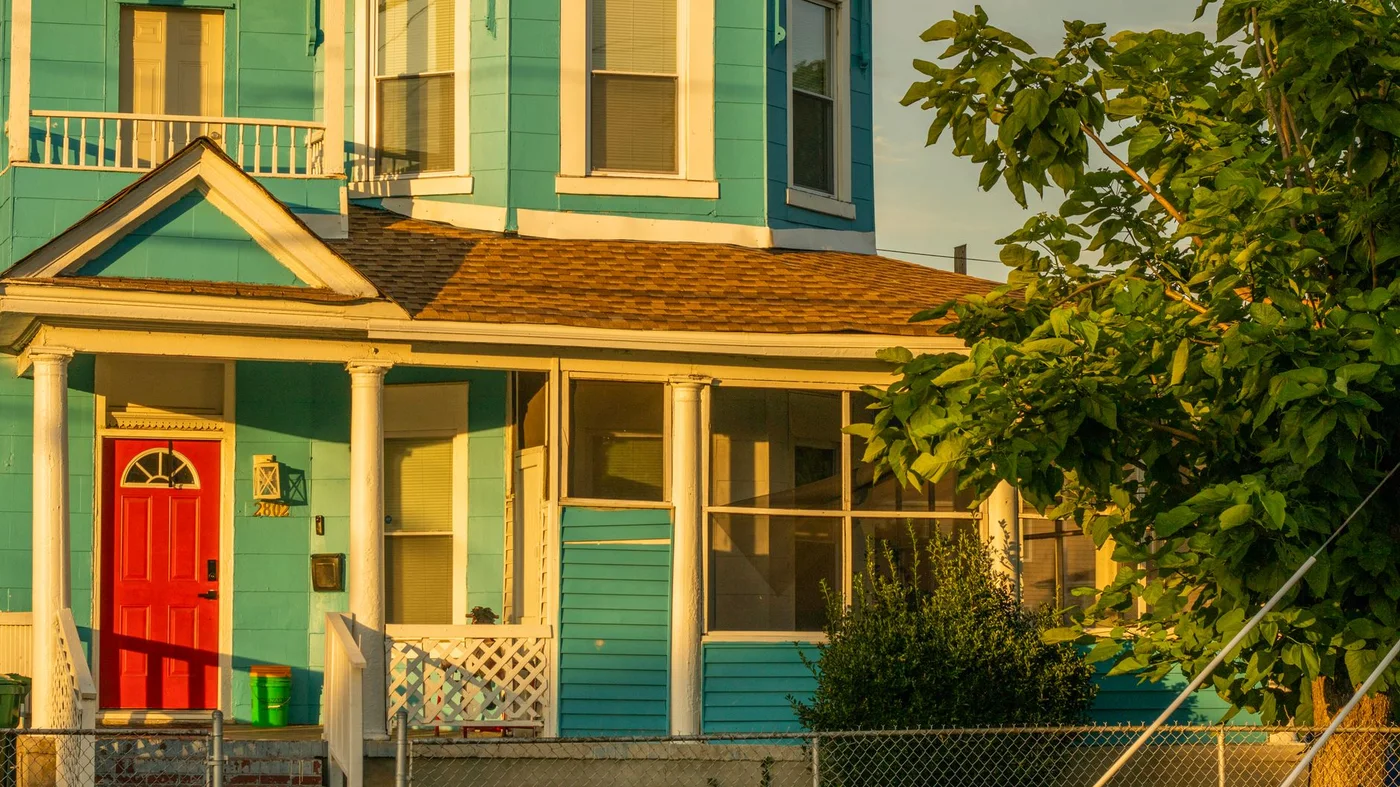
Older wood-frame house with a front porch and red door in Newport News, Virginia
Norfolk, Newport News and Richmond carry a lot of pre-1950 housing, and condition is the usual obstacle to a financed sale.

We Buy Houses Across Virginia

Select a city to learn more

Want to see the number before you decide anything?Tell us the address. The offer is free, there is nothing to sign, and if listing would net you more we can usually say so.
Get My Cash Offer or call (833) 330-1625
Asked in Virginia

Are "We Buy Houses" Companies a Ripoff?

Virginia sellers search this, and they search competitors by name alongside the word “legit”. We are one of these companies, so weigh what follows accordingly, but the industry does contain real problems and you should know what they look like.

The things that genuinely go wrong

  • The number moves. A high figure on the phone, then a reduction after an inspection, close to settlement when you have least room to walk away.
  • The buyer is not the buyer. Your contract is assigned to somebody else for a fee. Assignment is legal and common, but you should be told, and you should know who is actually bringing the money to settlement.
  • Pressure on the signature. Exploding deadlines, a contract in front of you before you have read it, discouragement from speaking to an attorney.
  • Outcome promises. Nobody can promise to stop a foreclosure or protect your credit. Those depend on your lender and on whether a settlement actually happens.

What to ask anyone, including us

  • Is this your own money, or will the contract be assigned?
  • What would cause this number to change between now and settlement?
  • Which settlement agent is handling it?
  • Can I take this to my own attorney before signing? A no is your answer.

Our offer is free, there is nothing to sign to get one, and if a listing would leave you better off we can usually say so on the call rather than after you have committed to something.

Cash Home Buyers Across Hampton Roads, Richmond, Northern Virginia and Every Virginia Metro

Virginia holds several unrelated markets. Northern Virginia runs on federal employment and contracting at price points nothing like the rest of the Commonwealth, Hampton Roads runs on the Navy, Richmond on its own economy, and the valley and southwest on something different again. We operate across all of them.

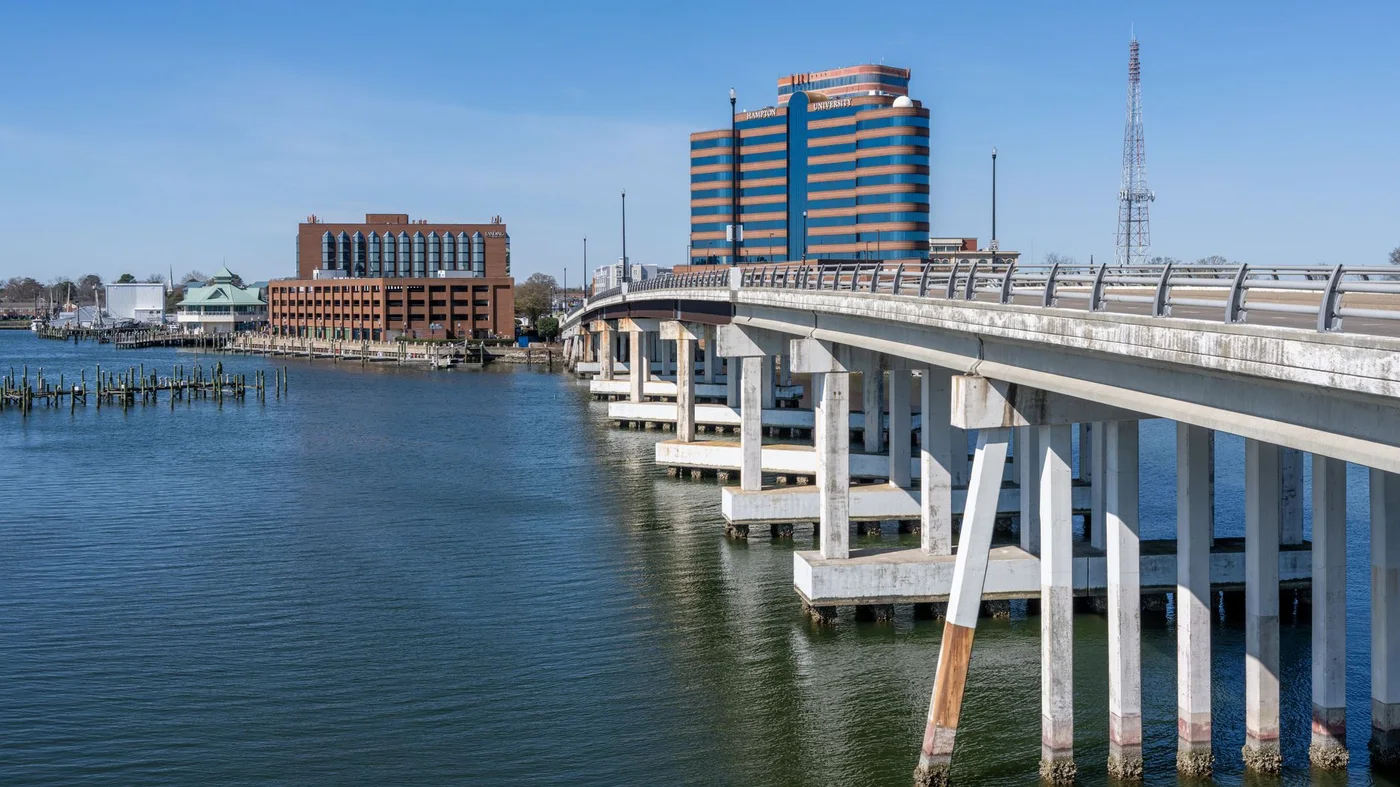
View across Hampton Harbor in Virginia with a bridge and waterfront buildings
Northern Virginia and the southwest behave like different markets, and a statewide median tells you little about either.

Hampton Roads

Virginia Beach, Norfolk, Chesapeake, Newport News and Hampton

The largest concentration of population in the Commonwealth and a market driven by the Navy and the shipyards. Constant military turnover means hard moving dates rather than flexible ones, and Norfolk and Newport News carry a lot of pre-1950 housing.

Sell Your House in Hampton Roads →

Richmond and the Tri-Cities

Richmond, Henrico, Chesterfield and Petersburg

Its own economy rather than an extension of anywhere else. Historic neighborhoods in the city with substantial older stock, and suburban Henrico and Chesterfield behaving quite differently from either.

Sell Your House in Richmond and the Tri-Cities →

Northern Virginia

Arlington, Alexandria, Fairfax, Loudoun and Prince William

Federal employment and contracting drive this market and its price points bear no relation to the rest of the Commonwealth. Arlington and Alexandria price like a different state entirely.

Sell Your House in Northern Virginia →

Fredericksburg and the Corridor

Fredericksburg, Spotsylvania and Stafford

The I-95 corridor between Richmond and the D.C. area, absorbing people priced out of Northern Virginia. Newer stock, long commutes and steady turnover.

Sell Your House in Fredericksburg and the Corridor →

Roanoke and the Valley

Roanoke, Salem and Botetourt

The largest market in western Virginia, at prices well below the eastern half of the state. Older housing stock and a buyer pool that thins quickly outside the city.

Sell Your House in Roanoke and the Valley →

Charlottesville and Central Virginia

Charlottesville, Albemarle and Lynchburg

A university market with a large rental component in Charlottesville itself, and a quite different economy down in Lynchburg. Rural parcels around both carry their own title complications.

Sell Your House in Charlottesville and Central Virginia →

The Shenandoah and the North

Winchester, Frederick and Harrisonburg

The valley up toward the West Virginia line, with agriculture, commuting toward the D.C. area and a mix of very old housing stock and newer development.

Sell Your House in The Shenandoah and the North →

Southside and Southwest Virginia

Danville, Martinsville, Bristol and the far southwest

The most affordable part of the Commonwealth by a wide margin. Thin comparable sales, long distances, and the highest share of inherited and vacant property we see in Virginia.

Sell Your House in Southside and Southwest Virginia →

Virginia Counties and Cities We Cover

From Loudoun in the north down to the Tidewater and west to the Cumberland Gap, our city pages span the state, and we evaluate property anywhere in the Commonwealth. Being inside the footprint is not the same as an offer. Location, property type, condition, marketability, title and our current buying criteria all decide whether we can make one.

Alexandria County
Amherst County
Arlington County
Augusta County
Bedford County
Bristol County
Campbell County
Charlottesville County
Chesapeake County
Chesterfield County
Colonial Heights County
Culpeper County
Danville County
Fairfax County
Falls Church County
Fauquier County
Fluvanna County
Fredericksburg County
Gloucester County
Hampton County
Hanover County
Harrisonburg County
Henrico County
Hopewell County
Loudoun County
Lynchburg County
Manassas County
Manassas Park County
Martinsville County
Montgomery County
Newport News County
Norfolk County
Petersburg County
Poquoson County
Portsmouth County
Prince William County
Radford County
Richmond County
Roanoke County
Salem County
Staunton County
Suffolk County
Virginia Beach County
Warren County
Waynesboro County
Williamsburg County
Winchester County
Do not see your town on the list?We evaluate property in every Virginia county and independent city, not only the ones with their own page.
Get My Cash Offer or call (833) 330-1625

Virginia Cities We Serve

Communities from the Potomac down to the North Carolina line. Our busiest Virginia markets are Virginia Beach, Richmond, Norfolk, Chesapeake, Arlington, Newport News, Alexandria, Roanoke, Hampton and Fredericksburg. Select your city for local detail.

Northern Virginia
Virginia Beach-Chesapeake area
Richmond area
Roanoke area
Lynchburg area
Blacksburg area
Staunton area
Charlottesville area
Other Virginia communities
Asked in Virginia

What "As-Is" Actually Means, and How Much a Cash Sale Costs You

“How much do you lose when you sell your house for cash” is one of the things Virginia sellers search alongside this page. Here is a straight answer.

You lose the difference between a prepared house and an unprepared one

A cash offer sits below what a repaired, staged, photographed house would fetch after a full marketing period. That gap is not a trick. It is the cost of the work not being done, the time not being waited out, and the risk not being carried by you. In a market appreciating at 5.4% a year that gap is real, and we would rather put it in writing than leave it vague.

What "as-is" genuinely covers

  • No repairs from you. Roof, HVAC, the crawl space nobody has looked at in years, all priced in rather than billed to you afterwards.
  • No cleaning out. Take what you want and leave the rest.
  • No lender on our side, so there is no appraisal to come in low and no underwriter deciding the property is uninhabitable a week before settlement.
  • An inspection still happens. We look at the house. Any company promising to buy sight-unseen is either not going to complete or is planning to renegotiate later.

What it does not cover

Your mortgage payoff, your prorated property taxes and the grantor's tax stay yours. Eagle pays the other closing costs, and there is no agent commission on a direct sale to us. It does not make your debts disappear.

When the arithmetic favors us, and when it does not

Two things decide it: whether you have the time to wait a sale out, and whether you have the money to put the house right before it goes on. Where you have both, a listing will normally beat us here, and we can usually say so on the call.

Where one of them is missing, and in Virginia that often means orders with a date on them or a house four hours away that nobody can get to, the comparison is no longer list price against cash price. It is a cash price now against months of carrying an empty house at a distance. In that situation we are not the fallback. We are the option that works.

Virginia Seller Situations: Foreclosure, Probate, Military Moves, Rentals and Vacant Property

These are the situations we run into most often in Virginia, and what we can and cannot do about each one.

⚠ Facing a Trustee's SaleCheck which notice period applies to you

The first thing to establish is which notice period applies to you. If the property is your home, it is generally the longer one, not the two weeks most pages quote. If it is a rental, a second property or anything other than owner-occupied residential, the shorter one applies. The laws section on this page sets out the detail.

The second is where the advertisement stands, because the sale can follow the last advertisement quickly. And the third is that Virginia gives nothing after the sale, so everything you can do sits before it.

A sale that closes and pays off the loan ends the matter. We cannot promise to stop a foreclosure or protect your credit, because that depends on your lender, the timing and whether a closing actually happens. Send us the notice and the dates and we will tell you honestly whether a sale is realistic, including when the honest answer is that you have more time than you thought and should use the HUD counseling named in the letter first.

Related guide: How to Sell Your House Fast Before Foreclosure

🏠 Inherited Property and ProbateVirginia probate, out-of-state heirs and rural parcels

An estate cannot convey clear title until the personal representative has authority to sell, and Virginia probate runs through the circuit court clerk on its own timetable. We work with executors regularly and the usual constraint is the court rather than the house.

The situation we see most in Virginia is an inherited house in the southwest or the Northern Neck with heirs living in Richmond, Northern Virginia or out of state entirely. Distance is the real problem: nobody can get there to maintain it, show it or deal with what has gone wrong since it was last occupied.

Older Virginia deeds also turn up boundary descriptions written in the language of an earlier century, which a surveyor rather than a lawyer usually has to resolve. Tell us where probate stands and we will work to it rather than asking you to have it finished first.

Related guide: How to Sell an Inherited House

⚓ Military Moves and PCS OrdersWhen the date is set by somebody else entirely

Virginia has one of the largest military populations in the country, through Hampton Roads, Quantico, Fort Gregg-Adams and the Pentagon, and it creates a situation the rest of our footprint rarely sees: a hard moving date set by orders rather than by choice.

That changes the arithmetic. A listing that takes 38 days on market plus a closing period may simply not fit inside the time you have, and carrying an empty house at a distance while it sits unsold is the outcome people are trying to avoid.

Tell us the report date early. It is the single most useful piece of information for working out whether a sale can realistically close in time, and if it cannot we can usually say so rather than let you find out late. Where the numbers work, a listing may still be better, and we will tell you that too.

Related guide: Selling Your Home Before a Job Relocation

🔑 Rentals, Tenants and Small MultifamilyWe buy occupied, and leases generally survive the sale

We buy occupied property. A tenant in place is not an obstacle and you do not need to remove anyone before talking to us. Existing leases generally survive a sale, and we would rather take the property with its tenancies intact than ask you to create a vacancy.

A great many Virginia rentals started as somebody's home before a posting or a job moved them, and were never meant to be an investment. Where deferred maintenance has reached the point that no lender will finance the house, that is squarely the case for a cash sale rather than a listing, because the pool of financed buyers is close to empty regardless of the asking price.

Bring the leases, the rent roll, the deposits and any arrears or disputes. Security deposits are the item most often overlooked and they have to be accounted for at closing.

Related guide: Selling a Rental Property With Tenants

💵 Divorce and Co-Owned PropertyBoth signatures, or we cannot proceed

A house is often the last asset to be settled and the one that keeps two people tied together after everything else is done.

The practical constraint is authority: both owners on title normally have to agree to a sale, and we cannot proceed on one signature where two are required. Where attorneys are involved we are happy to work through them, and where a decree already specifies what happens to the house, send it across and we will work to what it says.

We are not a party to the dispute and will not take a side in it. Our job is to give both of you the same number in writing so you can decide what to do with it.

Related guide: Selling a House During Divorce

Northern Virginia and the southwest are different markets entirely.We price against sales in your own county or city, because a statewide median tells you almost nothing about your street.
Get My Cash Offer or call (833) 330-1625

What Actually Happens on the First Call

People put off calling a company like ours because they do not know what they are walking into. Here is a real call, with the details that could identify anyone removed. We are not saying it was a Virginia seller, because we do not attach cases to states they did not come from.

From our own call records

A man called about his wife’s house. She had sent the inquiry, he was out running errands, and he thought he would get things started. Our acquisition manager noticed the inquiry was in her name, asked whether she was unable to take part, and when the answer was no, she simply asked me to call, he stopped the conversation there. Not for a signature. We talk to the owner. They booked a three-way call for once he was home, around his drive rather than our calendar.

What that first call is for, in his words: it is pretty basic, really more for us to find out about the property and the condition it is in. No offer on the spot, no paperwork, no pressure.

Anonymised from a recorded call. No names, no location, no property details, because the record holds none and we do not invent them. This account ends where the record ends, with a follow-up scheduled.

Virginia Real Estate Laws Every Seller Should Know

Virginia forecloses without a court case, and it has a reputation for being one of the fastest states in the country. For an owner-occupied home that reputation is built on the wrong number. Here is what generally applies before you sell, in plain language.

Before Any State Clock Starts: the Federal 120-Day Rule

Every state timeline on this page sits behind a federal one, and it is the single most useful thing to know if you have missed payments. Under Regulation X, 12 CFR 1024.41(f)(1), a mortgage servicer generally “shall not make the first notice or filing” required for a judicial or non-judicial foreclosure unless the borrower's mortgage loan obligation is more than 120 days delinquent.

That is roughly four months of missed payments before the state process is even allowed to begin. It is why a state sequence that looks alarmingly short on paper is usually longer in practice than the statute alone suggests.

The exceptions, because they are real. The rule does not apply where the foreclosure is based on a violation of a due-on-sale clause, or where the servicer is joining the action of a superior or subordinate lienholder. Small servicers are not exempt from this particular prohibition. Loan types and servicing arrangements vary, and some loans are outside Regulation X altogether.

So treat 120 days as the general floor rather than a guarantee, and work from the dates on your own paperwork. If a notice has arrived and you do not believe you are past that point, that is a question worth putting to a HUD-approved housing counselor or an attorney before you do anything else.

Sixty Days, Not Fourteen, If You Live There

This is the correction the whole page turns on. Virginia is widely described as one of the fastest foreclosure states in the country, and the figure people quote is fourteen days. That number is real, and it is not the one that applies to a house you live in.

Under Va. Code 55.1-321, written notice before a trustee's sale must be sent by certified or registered mail, and the period depends on the property:

Owner-occupied residential real estate60 days prior to the sale
All other deeds of trust14 days prior to the sale

Sixty days is not long, but it is more than four times what most pages tell a Virginia homeowner they have. The federal rule above generally sits in front of it as well.

The notice must also state the date, time and place of the sale and, for residential property, must include HUD counseling resources and your recent payment history. Those two items are worth reading before anything else in the envelope. Free HUD-approved housing counseling is available before you commit to anything, including to us.

Official source: Va. Code §55.1-321

The Advertisement Is Short, and There Is Nothing Afterwards

The advertisement of the sale runs on a much shorter clock than the notice, which is where Virginia's fast reputation comes from.

Under Va. Code 55.1-322, where the deed of trust specifies the advertisement, weekly publication requires “not less than once a week for two weeks” and daily publication “not less than once a day for three days, which may be consecutive days”. Where the deed of trust says nothing, the trustee must advertise “once a week for four successive weeks”, unless the property is in or near a city, where five different days of publication is deemed adequate.

The sale must then happen “no earlier than eight days following the first advertisement or more than 30 days following the last advertisement”.

And afterwards there is generally nothing. Virginia deed-of-trust foreclosures are non-judicial and there is normally no post-sale right of redemption, so the whole of your window sits before the sale. We have not read a governing provision for that and are not citing one, so confirm your own position with a Virginia attorney rather than relying on this page for it.

Official source: Va. Code §55.1-322

A Low Transfer Tax, and Who Pays It

Virginia's grantor's tax is genuinely cheap. Under Va. Code 58.1-802 it is “50 cents for each $500 or fraction thereof” where the consideration exceeds $100. That is about $1.00 per $1,000, roughly 0.1%, which puts Virginia alongside Georgia at the bottom of the range and a long way below states that charge a full percent or more. On a house at the statewide median it is a few hundred dollars rather than a few thousand.

Who pays it. The statute says the tax “shall be paid by the grantor, or any person who signs on behalf of the grantor”, so it is the seller's by default. It then expressly adds that “the grantor and grantee may arrange for the grantee to pay all or a portion of the tax”. So it is movable by agreement, and the contract controls.

Some Virginia regions add their own grantor's tax on top of the state rate. We are not publishing those figures because we have not read them, and your settlement agent will compute the actual number for your locality.

Disclosure and closing. Virginia has a Residential Property Disclosure Act, and we have deliberately not summarized its contents or exemptions here because we have not read it closely enough to state them. What holds generally is that selling as-is describes who pays for repairs, not what you may leave unsaid. Closings are conducted by settlement agents, which may be title companies or attorneys, and no attorney is required, which is one reason a clean Virginia file can close toward the shorter end of our range.

Official source: Va. Code §58.1-802, grantor's tax

General information, not advice. This section describes Virginia practice in general terms and was checked against the sources cited in September 2026. Laws, timelines and local procedures change, some Virginia regions add their own grantor's tax, and how any of it applies to your property depends on facts we have not seen. It is not legal, tax or financial advice, and it is no substitute for talking to a Virginia attorney, accountant or HUD-approved housing counselor about your own situation.
Asked in Virginia

If You Need to Sell Immediately in Virginia

Two things are worth knowing before you decide anything quickly.

You may have more notice than you were told

Virginia's reputation for speed is built on a notice figure that does not apply to a house you live in. For owner-occupied residential real estate the written notice before a trustee's sale is far longer, and the laws section on this page sets out the detail. If you have been working from two weeks, check the date on your own notice before you decide anything.

But there is nothing after the sale

Virginia gives no post-sale redemption period, so the whole of your window sits before the sale date. That makes it tight even with the longer notice, and it means the date on the notice is the one that governs every option you have.

What we can and cannot say

A sale that closes and pays off the mortgage ends the matter. We cannot promise to stop a foreclosure or protect your credit, because that turns on your lender, the timing and whether a settlement actually happens. Send us the notice and the dates and we will tell you straight whether a sale is realistic in the window you have. The HUD counseling resources named in your notice are free, and they are a good first call.

Told you only have two weeks?For a house you live in the notice period is generally far longer than that. Send us the letter and we will work out where you actually stand.
Get My Cash Offer or call (833) 330-1625

Virginia Housing Market Snapshot

Virginia is appreciating quickly, with only three months of supply. Figures below are Redfin statewide data for August 2026.

$448,034Median sale priceRedfin, August 2026
38 daysMedian days on marketRedfin, August 2026
+5.4%Year-over-year price changeRedfin, August 2026
35,799Homes for sale, up 8.5%Redfin, August 2026
29.6%Homes selling above list priceRedfin, August 2026
99.1%Sale-to-list price ratioRedfin, August 2026
Large older Tudor Revival house set back behind bare winter trees in Hampton, Virginia
Virginia homes sold in a median of 38 days in August 2026, with prices up 5.4% on the year.

A quick, appreciating market, and when that favors listing

The median sale price was $448,034 in August 2026, up 5.4% on the year, homes sold in a median of 38 days and supply sat near three months.

Two things decide whether listing is better for you: the time to wait a sale out, and the money to put the house right before it goes on. Where you have both, list it, and in a market appreciating this quickly we can usually say so without hesitating. Where one is missing, a cash sale is usually the stronger option rather than the weaker one.

If a foreclosure notice has arrived, the dates on it matter more than any market figure, and the laws section on this page explains which notice period applies to you.

Selling Just Over the Virginia Line?

Plenty of Virginia sellers own a second property, an inherited house or a former rental across a border, and the rules change the moment you cross it. Virginia forecloses without a court and gives no redemption after a trustee's sale. Its neighbors do not all work the same way. We evaluate property in all of these.

Maryland

North across the river, court-supervised rather than by trustee, with two clocks before a case can even be filed. See Silver Spring or Baltimore or Waldorf.

North Carolina

South of the line, where a clerk of court hearing sits inside what is otherwise a power-of-sale process. See Raleigh or Charlotte or Greensboro.

West Virginia

West through the mountains, non-judicial as well, with its own timetable. See Martinsburg or Charleston or Morgantown.

Tennessee

South west past Bristol, another trustee state with its own notice requirements. See Knoxville or Kingsport or Johnson City.

What Sellers Say About Working With Us

Amber MotaRated 5 out of 5
Quick and efficient! I highly recommend!
Mary Ann BowersoxRated 5 out of 5
Wonderful to work with and stayed in contact at all stages through the process. Thank you again for everything.

4.5 from 40 reviews on Google · read them all

2019

Founded, and headquartered in Columbus, Ohio.

1,000+

Transactions since 2019 across a 43-state footprint. Coverage does not mean every property qualifies.

A+

Eagle Cash Buyers, LLC is BBB Accredited with an A+ rating. Accreditation is not an endorsement. See the profile.

Have orders with a date on them?Tell us the report date on the first call. It is the single most useful thing for working out what can realistically close in time.
Get My Cash Offer or call (833) 330-1625

Ready to See What a Virginia Cash Sale Looks Like?

Sold as-is. No agent commission. Most transactions close in roughly 21 to 42 days.

Get My Free Cash Offer

Or call us: (833) 330-1625

Virginia Home Selling Questions, Answered Straight

Real answers about Virginia law, timelines and how the process actually works here.

How fast can you close on a Virginia home?

Most Eagle transactions close in roughly 21 to 42 days. Virginia closings are handled by settlement agents rather than requiring an attorney, so a clean file can sit toward the shorter end of that range. The timeline depends on title readiness, liens, mortgage payoffs, the grantor's tax and the property review. If you have a scheduled trustee's sale or a hard moving date, tell us early and we will say honestly whether it is realistic.

How quickly can I get an offer?

During business hours an initial no-obligation offer is often possible within minutes to a few hours once we have enough information about the property. Some houses need research, photographs or a walkthrough before we can put a number in writing. We would rather take an extra day and give you a figure we can actually perform on.

Is it true Virginia only gives two weeks' notice before a foreclosure sale?

Not for a house you live in, and this is the most important correction on the page. For owner-occupied residential real estate the written notice must be sent 60 days prior to the sale. The 14-day figure that gets quoted everywhere applies to other deeds of trust, not to your home. The laws section on this page has the detail, and a Virginia attorney can check your own dates.

Does Virginia foreclose through a court?

Generally no. Virginia foreclosures are non-judicial, conducted by a trustee under the deed of trust, so there is no lawsuit to answer and no hearing. That is why the notice requirements carry all the weight here, and for most federally covered residential mortgages the federal 120-day rule generally has to be satisfied before the sequence begins at all.

Is there a redemption period after a Virginia trustee's sale?

Generally no. After a non-judicial trustee's sale there is normally no right to buy the property back, so the whole of your window sits before the sale. We have not read a governing provision for that and are not citing one here, so confirm your own position with a Virginia attorney rather than relying on this page for it.

What is the grantor's tax and who pays it?

The state rate is 50 cents for each $500 of consideration or fraction of it, where the consideration exceeds $100. That is about $1.00 per $1,000, roughly 0.1%. The statute puts it on the grantor, so it is the seller's by default, and it expressly allows the grantor and grantee to arrange for the grantee to pay all or a portion, so it is movable by agreement. Some Virginia regions add their own grantor's tax on top and we are not quoting those figures because we have not read them.

Who conducts the closing in Virginia?

A settlement agent, which may be a title company or an attorney. No attorney is required, which is one reason a straightforward Virginia transaction can move on the shorter end of our range. Plenty of sellers still choose to have their own attorney, particularly where probate or a divorce decree is involved, and that is a sensible choice rather than an unusual one.

I have PCS orders. Can you close before my report date?

Often, and it is one of the most common reasons Virginia sellers come to us. Tell us the report date on the first call, because it is the single most useful piece of information for working out what is realistic. Most of our transactions close in roughly 21 to 42 days, so whether that fits depends on how much time you have and how clean the title is. If it does not fit we can usually say so rather than let you find out late, and if a listing would still work inside your window we will tell you that too.

Do you buy houses with tenants in them?

Yes. A tenant in place is not an obstacle and you do not need to remove anyone before talking to us. Existing leases generally survive a sale. A great many Virginia rentals started as somebody's home before a posting or a job moved them, and were never meant to be investments. Bring the leases, the rent roll, the deposits and any arrears or disputes.

Does selling as-is mean I do not have to disclose anything?

No. As-is describes who pays for repairs, not what you are allowed to leave unsaid. Ordinary obligations around misrepresentation do not switch off because a sale is as-is. We have deliberately not summarized Virginia's Residential Property Disclosure Act here because we have not read it closely enough to state it, and your settlement agent or a Virginia attorney should advise on your specific facts. We buy properties with serious problems every week, so telling us early costs you nothing.

Should I just list it instead?

It turns on two things: whether you have the time to wait a sale out, and whether you have the money to put the house right before it goes on. Where both are true, list it, and in Virginia we can usually say so without hesitating, because this market is appreciating quickly. In August 2026 the median sale price was $448,034, up 5.4% on the year, homes sold in a median of 38 days and supply sat near three months. Where one of those two is missing, a cash sale becomes the better answer and often the only one that closes: a house no lender will finance, orders with a date on them, an estate that needs settling, a trustee's sale already advertised with nothing behind it, repairs you cannot fund, or a title problem that has to be cleared before anyone can buy at any price.

What will you actually pay?

Less than a prepared house would fetch on the open market, and we will not pretend otherwise. You are trading price for speed, an as-is sale and a much shorter list of things that can go wrong. In a market appreciating this quickly that gap is real, which is exactly why we put it in writing rather than leaving it vague. What we will not do is give you a headline number on the phone and then reduce it after an inspection. The offer is free and there is nothing to sign to get one.

Oren Sofrin

Reviewed by Oren Sofrin, Founder and CEO of Eagle Cash Buyers

Oren has more than ten years in real estate, and he and the Eagle team have completed over 1,000 transactions. His market commentary has been quoted by MSN, Yahoo Finance, GOBankingRates and BiggerPockets. Last reviewed October 2026.

See How We Calculate Your Virginia Cash Offer

Get My Cash Offer →