Companies that buy houses as is fall into five types: iBuyers, franchise networks, local and regional investors, marketplaces, and direct buyers that may assign the contract. They differ in which houses they take, how they set the price and who ends up owning yours. To choose well, compare written net offers, not ads.
The companies that buy houses as is don't all work the same way. An iBuyer, a franchise network, a local investor and a direct buyer each set different limits on condition, charge in different ways and close at different speeds, and picking the right kind of buyer matters as much as picking the right name.
"As is" means you sell the house in its current condition and don't pay for repairs first. It doesn't mean the price ignores the condition. Most buyers in this guide work backward from what the house might be worth, subtracting repair costs, resale costs and a margin, so the real differences between companies show up in the fees, the fine print and the contract.
We should say this up front: Eagle Cash Buyers is one of these companies, so weigh our view with that in mind. We describe our own model in one section and compare the rest by type, without ranking anyone. The right buyer depends on your house, your timeline and your numbers.
What "As Is" Does and Doesn't Mean
Selling as is usually means the buyer takes the house with its defects, and you don't make repairs or upgrades to get it ready, which saves you the contractors, the cost and the months that preparing a house for a traditional listing can take. The buyer may still inspect it, and the contract decides what happens, and whether the price can change, if something turns up.
It doesn't usually erase your duty to disclose. Disclosure duties can still apply in an as-is sale, and the rules differ from state to state, so ask a real estate attorney what applies to you.
No company buys every house. Condition, location, price range and title problems all decide whether a given buyer can make an offer at all.
What As-Is Houses Look Like in Our Files
In the seller files Eagle Cash Buyers documented in 2026, about 10% involved a house in severe condition, such as a total loss after a fire, a house gutted to the studs or one that needed a hoarding cleanout. Most didn't reach that level, which is worth knowing, because "as is" covers far more than wrecks.
These are sellers who contacted a cash buyer, not a representative sample of all home sellers.
The Five Main Types of Companies That Buy Houses As Is
"We buy houses" is a slogan, not a business model, and two companies that use it can treat you very differently. Most of them fall into one of five models. Here is how each one generally works, and the trade-offs a seller should know about. The names below are examples of a model, not a ranking.
1. iBuyers
Opendoor is an example. These companies use technology to make an initial offer from your address and a few details, and they may then confirm the condition with an inspection. Each one sets its own limits on the homes, markets and price ranges it will buy, so ask whether your house fits before you spend time on it.
The FTC took action against Opendoor in 2022 over claims about its offers, fees and repair costs, and the company agreed to pay $62 million in refunds, as the FTC's consumer alert explains. The lesson for any seller is to check a company's claims against the written offer and to compare more than one kind of buyer. Our guide on cash buyers versus iBuyers goes deeper.
2. Franchise networks
These are national brands with independently owned local offices. A local owner may visit and make an offer after a walkthrough. Each office runs on its own. Your experience and your price can differ from one office to the next under the same brand name, so treat every office as its own company. Our look at the truth behind "we buy ugly houses" explains what that kind of slogan does and doesn't promise.
3. Local and regional investors
These are independent companies that buy with their own money and know the neighborhood. Quality ranges widely. Some are polished operations. Some are one-person shops. Ask for proof of funds and recent references. Get the offer in writing.
4. Marketplaces and investor networks
A marketplace collects the details of your house and sends them to several investors who bid. You compare offers side by side. That helps if you want competition, but ask who the actual buyer will be, whether the platform charges a fee, and who pays it.
5. Direct buyers that may assign the contract
Some companies buy the house themselves. Others sign a contract with you and then assign it to another buyer, who closes the purchase. Assignment is a feature of many investor contracts, and it should be disclosed in the agreement before you sign. Eagle works this way: we may buy directly or assign the contract, and the agreement tells you which before you commit.
Compare the Five Types at a Glance
Here are the five models side by side. The table compares how each type usually works, not any one company's fees or speed, because those change and only a written offer tells you the real figure.
| Type | Who sets the offer | Who ends up owning the house | Condition fit | Often suits | Ask about |
|---|---|---|---|---|---|
| iBuyer | A technology-based offer, then a possible inspection | The company | Set by each company | Homes that fit the company's limits | Service fee and repair deductions |
| Franchise network | A local owner after a walkthrough | The local office or its buyer | Varies by office | Sellers who want a local walkthrough | Differences between offices |
| Local investor | The investor after a walkthrough | The investor | Varies by company | Sellers who want to deal with one local buyer | Proof of funds and references |
| Marketplace | Several investors bidding | Whichever investor wins | Varies by investor | Sellers who want competing bids | Platform fees and who the buyer is |
| Direct buyer that may assign | The company after property and title review | The company or the buyer it assigns to | Varies by company | Sellers who want one point of contact and a set date | Whether the contract is assigned |
These are general patterns, and individual companies differ, so confirm every detail in writing before you rely on any of it, including the fees, the timeline and the contract terms.
Match the Buyer to Your Situation
Different situations put different things first. This table shows what matters most in each one, and what to ask before anything else.
| Your situation | What matters most | Ask first |
|---|---|---|
| House in good condition, no rush | Your net price | Would listing with an agent net more after repairs and carrying costs? |
| Major repairs or damage | Whether the buyer takes that condition at all | Do you buy houses in this condition, and who quotes the repairs? |
| A deadline, such as a move or an auction date | Certainty and timing | What is the realistic closing timeline, and who controls the date? |
| Inherited or probate property | How the buyer handles title and paperwork | What do you need from the estate, and what happens if the deed is not yet in my name? |
| Liens or back taxes | What comes out of your proceeds | Which payoffs are mine, and which costs do you cover? |
| You want the highest price | Competition between buyers | Can I compare several written offers side by side? |
| Tenants or a vacant rental | Whether the buyer takes the house with occupants or empty | Do you buy with tenants in place? |
These are general patterns. Every company sets its own limits, so confirm in writing.
How Investors Price Your House
You see the kitchen your family used. An investor sees a list of costs and a resale price. A dated bathroom, worn flooring or a roof near the end of its life are repair items on that list, not reasons to walk away, and a good investor can often estimate them quickly from photos and a short visit.
Many investors work backward. They start with what the house could sell for after repairs, then subtract the repairs, the cost of owning and reselling it and their own profit. Whatever is left is the offer. Cosmetic problems rarely scare them. Structural problems, a clouded title or a house that would be hard to resell can change the offer a great deal, and sometimes they decide whether there is an offer at all.
Here is a hypothetical example with round numbers, only to show the logic. Suppose a repaired house might sell for $200,000. The buyer estimates $30,000 in repairs, $20,000 for holding and resale costs and $25,000 for profit. That leaves an offer of $125,000. A buyer with a different repair estimate or a thinner margin would land on a different number.
Why Investors Buy
The plan for your house shapes the offer, so it helps to know which kind of investor you're talking to.
- Fix-and-flip investors renovate the house and resell it. They are often drawn to houses that need real work, because the renovation is their business.
- Buy-and-hold landlords keep the house as a rental, so they care about location and structure more than finishes.
- Investment companies buy at scale, and some sign a contract and assign it to another buyer, as described above.
How an Investor Sale Works, Step by Step
It's shorter than a listing. Here is the usual order of events.
- You reach out. You share the address and basic details, and you may be asked for photos or a short visit.
- The investor reviews the house. That means a walkthrough or photos, plus a look at the title and comparable sales.
- You receive an offer. Ask for it in writing, and ask how it was built.
- You compare and decide. Get more than one offer if you can.
- You sign a purchase agreement. Read the as-is wording and any clause that can extend the closing.
- Title work and closing. A title company or attorney checks for liens and clears the paperwork, then you sign and get paid.
Timelines vary by company and by how long title work takes. Ask for yours in writing, because a closing date that lives only in a phone call can drift without anyone deciding that it should.
What to Compare Before You Choose a Company
A headline offer tells you very little. Score every company you talk to with the same questions, and get each answer in writing before you commit to anything. A company that dodges two or three of them is telling you something, and it's better to hear it now than at the closing table.
- Who is buying. Is it the company you're talking to, or someone it will assign the contract to? Get the answer in writing.
- What you'll net. Ask for a written figure after every fee, repair deduction, mortgage payoff and lien, because a high offer with big deductions can net less than a lower offer with none.
- How the offer was built. Ask for the after-repair value, the repair estimate and the margin. Our guide on how cash home buyers calculate their offer shows the math.
- Proof of funds. A company that pays cash should be able to show it, with a bank statement or a letter from a financial institution. Ask before you commit to a closing date or move a single box.
- Timeline and control. Ask who picks the closing date and what happens if title work runs long, because a closing that can slip week after week is a closing you don't control.
- A written offer. No written offer, no comparison. Ask what the offer assumes about the house and what would change it, so a late price change doesn't surprise you.
- The contract. Read every page. Check the as-is wording, any warranties, extension clauses and assignment terms before you sign, and ask about anything that doesn't match what you were told.
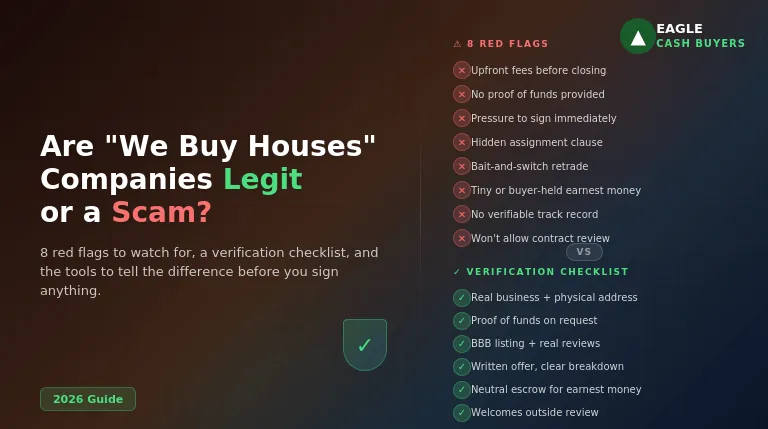
- Reputation. Look up the legal entity name and its state registration, check several review sites and see how long the company has operated, because a company that's hard to identify is hard to reach if something goes wrong. Our guide on whether we buy houses companies are legit lists the red flags.
- Pressure. A buyer who rushes you isn't working in your interest. If anyone pushes you to sign before your own attorney has read the agreement, slow down.
- Your own number. Get a rough idea of the house's market value first, so you know how far the offer sits below it.
How to Check Any Company Before You Sign
You don't need a lawyer to run these first checks. Most take a few minutes online.
- Find the legal name and look it up. Ask for the company's exact legal name, then search your state's business registry, which is often run by the Secretary of State. North Carolina's office, for example, explains how to search its business registration database.
- Read reviews in more than one place. Look at the company's BBB profile and at least one other review site, and read the complaints and how the company answered them.
- Never sign over your title on a promise. North Carolina's Department of Justice warns in its page on "We Buy Homes" scams to beware of anyone who asks you to sign over the title based only on their promises. A sale should run on a written purchase agreement.
- Close through a title company or attorney. Ask which one will handle the closing, then call it yourself using a number you found on your own.
- Don't pay to sell. The buyer pays you. Be wary of anyone who asks you for money up front to make an offer or hold your spot.
If something feels wrong after you've started, you can report it to your state attorney general's consumer protection office or to the FTC at ReportFraud.ftc.gov.
A Seller Who Read the Contract Out Loud
Real Seller Story
One seller in our files did what every seller should do with a purchase agreement: he read it line by line, on the phone, and asked about each clause. He was candid. "I'm not an expert in contracts, right?" he said.
The first thing he caught was a contradiction. The agreement asked him to state that the house was free of hazardous materials and material defects, while also selling it as is. If it's as is, he asked, why would he be warranting its condition? We brought an underwriter onto the call, the warranty language was removed, and a term was added stating that the clause was cancelled.
The second was a clause that let the closing extend week by week for title delays. He'd been burned before. He worried the house could stay tied up indefinitely. We explained that the extensions apply only to delays the buyer doesn't cause, such as probate, and we confirmed that in writing by text message.
Contracts differ from company to company, and ours won't match every other buyer's. That's the point. Read whatever you're handed, ask for changes in writing, and have your own attorney review it.
This story covers the contract conversation only, and details are limited on purpose to protect the seller.
Should You Fix Anything First?
A full renovation usually doesn't pay when the buyer plans to renovate anyway, since they may tear out whatever you've just installed. A few small steps can still help.
- Clear out trash and anything hazardous, so the buyer can see the actual house.
- Fix anything cheap and obviously broken, like a missing doorknob.
- Gather the deed, your mortgage statement and recent tax bills.
Don't overspend. A repair that costs you thousands may add far less to the offer, because the buyer has already priced the work using its own contractors' costs. You may still need to disclose known problems, and those rules vary by state. Our guide on how to sell my house as is covers what is worth doing before you sell.
Selling a Rental or an Inherited House
Often yes, with extra steps. If the house has tenants, your rights and theirs depend on the lease and on state and local law, and the buyer may take the house subject to those terms.
If you inherited the house, the sale generally can't close until the person selling has legal authority to sell, which may mean going through probate first. The process varies by state, so ask a local attorney. See how to sell an inherited house for what to expect. With either kind of house, liens, unpaid taxes or ownership questions can delay or cancel a deal with any buyer, so check them early.
Is Selling As Is to a Company Your Best Option?
Two things decide this: whether you have the time to wait out a listing, and whether you have the money to put the house right first. If you have both, listing with a good local agent can net more. Our comparison of a cash offer versus listing with an agent, which puts the costs of each route side by side, is a good place to start.
If either one is missing, selling as is to a company can be the better outcome, and sometimes the only one that closes. The price will be below what a repaired house might bring, because the buyer is paying for the repairs, the resale costs and the risk. That's the trade. Sometimes it's the right one.
The only comparison that matters is the buyer's number against what you would net from a traditional sale, after an agent's commission, your closing costs, any repairs a buyer's inspection might demand and the months of mortgage payments, taxes and insurance while the house sits. A job change, a divorce, an inherited house you can't maintain, a rental you're tired of managing and a looming deadline are all common reasons to choose the firmer date, and in each of them a quiet, direct sale can be worth more than a higher price that may take months to arrive.
Whichever way you lean, get more than one written offer. Our guide on where to get a cash offer and how to compare covers what to look at, and how to negotiate with a cash home buyer covers what to say.
Where Eagle Cash Buyers Fits
Eagle Cash Buyers, LLC is registered in Ohio and rated A+ by the BBB, and we've completed more than 1,000 real estate transactions. We evaluate properties in 43 states and buy houses in any condition, but whether we make an offer depends on the area, the value and whether the numbers work. We buy mobile homes only with the land. Our locations page lists the states, with guides such as selling a house fast in Ohio and in Florida.
Here is how we answer the same checklist we suggest you use on every company.
| Question | Eagle's answer |
|---|---|
| Who is buying? | We may buy directly or assign the contract. The agreement says which before you sign. |
| What do I pay? | No fees, no repairs, no closing costs, and no agent commission on a direct sale. Your mortgage payoff, any liens (including back taxes) and prorated property taxes come out of the sale proceeds. |
| Who pays transfer tax? | On a standard cash offer you pay it. On a Retail Max sale we pay it. The purchase agreement states who pays. |
| How fast can it close? | In as little as 21 to 42 days, or later if you need more time. You pick the date. |
| How does the price compare? | Our offer is below what a repaired house might bring. Get other offers and compare. |
| Who reviews the contract? | We encourage you to have your own attorney or agent read it. We're not attorneys, and we're not a lender. |
What is Retail Max? It is our second option for sellers who want a higher price and can wait. We put the house under contract at an agreed price above our straight cash offer and market it to an end buyer. You pay no agent commission, no closing costs and no approved repair or concession costs, and we pay the transfer tax. It needs showings, usually scheduled 24 hours ahead if the house is occupied, and it takes longer, because it depends on the end buyer and their financing. You usually net more than with a cash offer, but less than a full retail listing of a fixed-up house.
So "no fees" doesn't mean you take home the full price. What you net is the agreed price minus your own payoff, any liens and your prorated taxes, and on a standard cash offer the transfer tax as well. Ask us, or any buyer, for that net figure in writing.
Frequently Asked Questions
What is the best way to sell a house as is?
It depends on your time and money. If you can wait and afford some work, listing with an agent can net more. If you can't, get written offers from more than one type of buyer and compare what each sale would put in your pocket.
Who buys houses that need repairs?
Local investors, franchise offices and direct buyers may look at houses that need work, and each sets its own limits, as iBuyers do. No company buys every house, because title problems, location and price range also matter.
Do companies that buy houses as is pay market value?
Generally not. The offer is lower than what a repaired house might sell for, because the buyer takes on repairs, resale costs and risk. Compare written offers, and ask how each one was calculated.
Are companies that buy your house as is legit?
Many are legit. Some aren't, so look up the company's legal name in your state's business registry, ask for proof of funds and a written offer, never sign over your title on a promise, and have your own attorney read the contract before you sign.
How fast can a company that buys houses as is close?
It varies by company and by how long title work takes. Ask for the timeline in writing. With Eagle, closings can happen in as little as 21 to 42 days, or later if you need more time.
Can I negotiate with a company that buys houses as is?
Yes. You can question the offer and the contract terms, and you should ask for any change in writing and keep the written reply, because a verbal promise is hard to enforce.
Which company that buys houses as is pays the most?
It changes by house, location and condition, so no company pays the most every time. Get several written offers, then compare what you would net after fees, repairs and payoffs, because the highest headline number is often not the biggest check.
What is the best company to sell your house to?
There isn't one for every house. Search for local buyers and national networks near you, then run each one through the same questions above. Look for a verifiable legal name, reviews on several sites and a written offer, rather than relying on a ranking.